Tag: accounting

  • RV Park Ancillary Revenue: 5 Powerful Ways Marinas, Fuel, and Commissary Income Boost Your Cap Rate

    RV Park Ancillary Revenue: 5 Powerful Ways Marinas, Fuel, and Commissary Income Boost Your Cap Rate

    RV park ancillary revenue is one of the most underused levers in this business, and it is also one of the most overlooked during diligence. Buyers focus almost entirely on site rent, and while site rent is the core of the business, income from marinas, fuel sales, and commissary sales can meaningfully shift both your operating income and your eventual valuation.

    1. It Drops Nearly Straight to NOI

    This is what makes RV park ancillary revenue so powerful. Once the infrastructure exists, marina slips, a fuel pump, a small store, the incremental cost of serving an additional guest is low, so the revenue flows through to your bottom line with far less drag than site rent does. Industry research on ancillary income confirms the scale of the opportunity: the amount ancillary income contributes to net operating income can vary widely from a few percent to upwards of 10 percent. For an RV park already generating strong site rent, that additional 10 percent is not a rounding error. Foxen Administration

    2. It Compounds Through the Cap Rate Formula

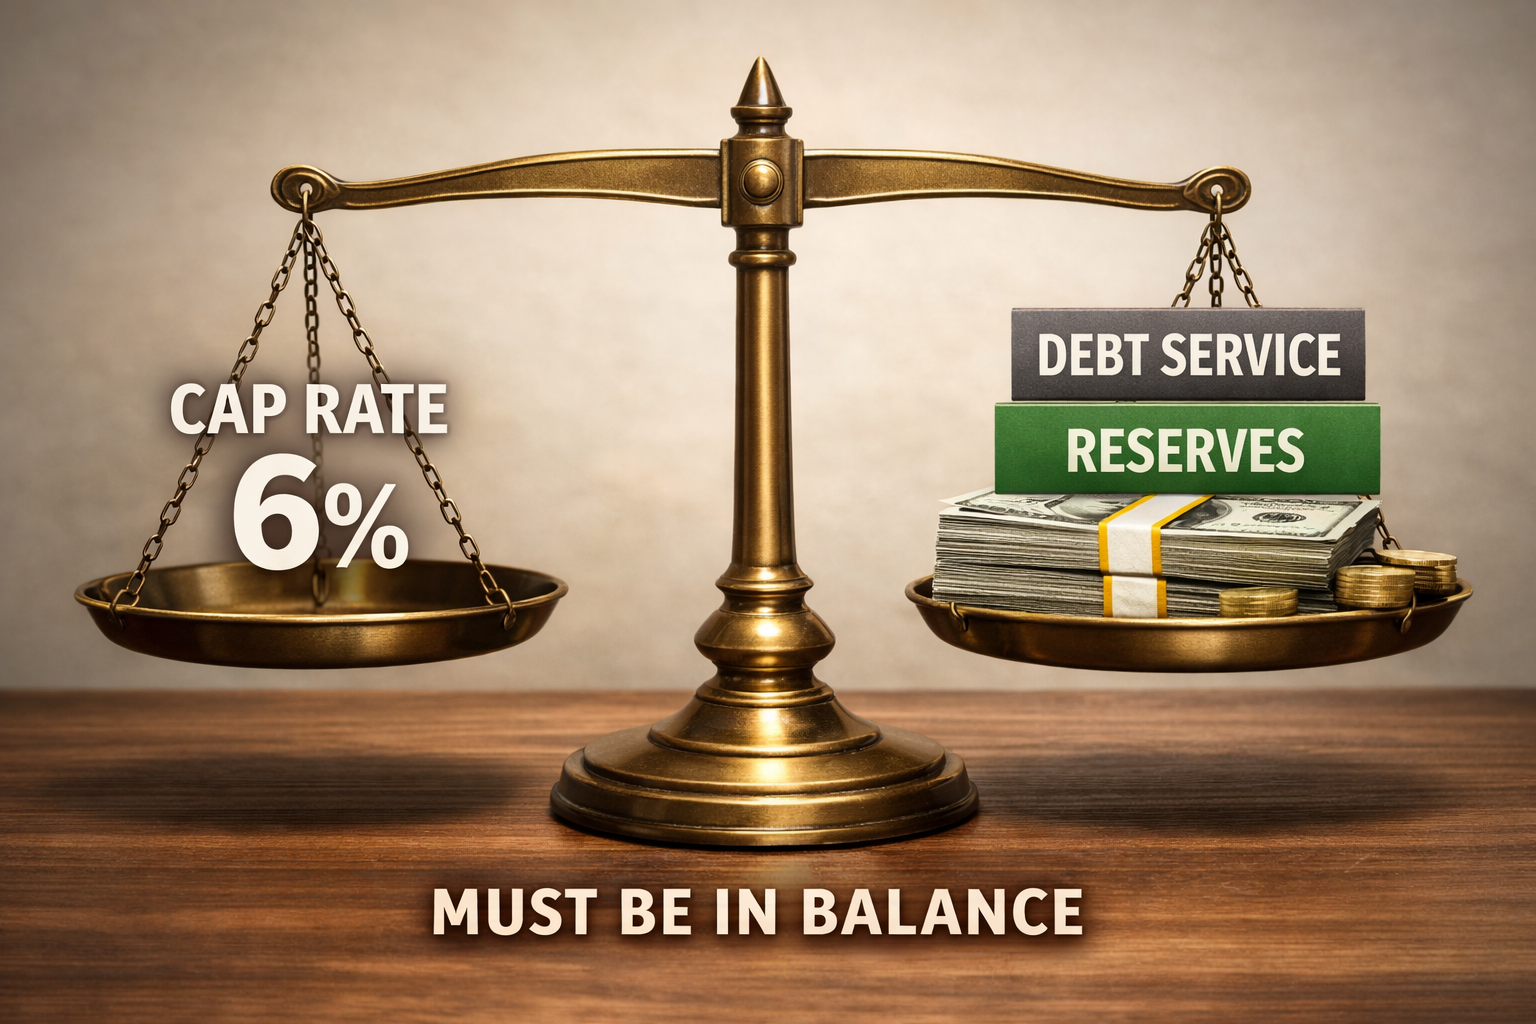
    A dollar of RV park ancillary revenue is worth more than a dollar in your pocket, because cap rate math multiplies every NOI improvement. At a 9 percent cap rate, an extra $10,000 in this income adds over $111,000 to your park’s implied value. This is exactly why sophisticated buyers dig into commissary, marina, and fuel numbers during diligence instead of treating them as a footnote.

    3. RV Park Ancillary Revenue Needs to Be Verified, Not Assumed

    Sellers sometimes bundle this revenue into a single “other income” line without breaking it out clearly, which makes it hard to know what is recurring versus what was a one-time boost. Rebuilding the real NOI number means separating RV park ancillary revenue into its actual components, marina slip fees, fuel margin, retail sales, so you know exactly what you are underwriting and what might not repeat under new ownership.

    4. Not All RV Park Ancillary Revenue Carries the Same Risk

    A marina generates fairly stable ancillary income tied to long-term slip rentals. Fuel margins can swing with commodity prices. Commissary and retail sales depend heavily on foot traffic and site occupancy. Treating all of these sources as equally reliable is a mistake, since a downturn in transient occupancy will hit your commissary sales far faster than it hits marina slip income.

    5. Building RV Park Ancillary Revenue Deliberately Beats Letting It Happen by Accident

    Owners who treat their store, fuel pump, or marina as an afterthought leave real money on the table. Deliberately growing this revenue, stocking what guests actually want, pricing fuel competitively, marketing marina slips to boaters beyond just RV guests, turns a passive amenity into an active profit center that shows up clearly in your revenue mix.

    What This Means for Your Next Deal

    If you are evaluating a park with a marina, fuel operation, or commissary already in place, do not skip past those line items to get to the site rent numbers. RV park ancillary revenue deserves the same diligence rigor as your primary rental income, because it can be the difference between an average deal and a genuinely strong one once you understand what it actually contributes to your return on investment.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    Further reading on how ancillary income affects property valuation is available from Foxen.

  • Cap Rate vs EBITDA Multiple: 5 Confusing Truths RV Park Buyers Get Wrong

    Cap Rate vs EBITDA Multiple: 5 Confusing Truths RV Park Buyers Get Wrong

    Cap rate vs EBITDA multiple is a comparison that trips up a lot of RV park buyers, especially as more listings and brokers start quoting EBITDA multiples alongside the traditional cap rate. Neither number is wrong, and neither one is more sophisticated than the other. They are two ways of expressing the exact same relationship, and once you understand how cap rate vs EBITDA multiple actually connects, a lot of the confusion disappears.

    Truth 1: A Cap Rate and an EBITDA Multiple Are Mathematical Inverses

    This is the entire foundation of the cap rate vs EBITDA multiple relationship. A cap rate is your income divided by price. A multiple is your price divided by income. They are inverses of each other, and the math confirms it directly: the cap rate is the reciprocal of the EBITDA multiple commonly used to value companies. Once that clicks, cap rate vs EBITDA multiple stops feeling like two competing systems and starts feeling like two dialects of the same language. Breaking Into Wall Street

    Truth 2: You Can Convert One to the Other Instantly

    Here is the shortcut that makes cap rate vs EBITDA multiple easy to navigate in real time. Divide 1 by the cap rate to get the multiple, or divide 1 by the multiple to get the cap rate. An 8 percent cap rate equals a 12.5x multiple. A 10x multiple equals a 10 percent cap rate. Once you know this conversion, you can compare any listing regardless of which number the broker chose to lead with.

    Truth 3: The Number a Broker Chooses to Lead With Is a Marketing Decision

    Brokers know that a lower cap rate and a higher multiple both sound more attractive, even though they can represent the exact same deal. A park priced at a 7 percent cap rate could just as easily be marketed as a 14x multiple, and the underlying value has not changed at all in the cap rate vs EBITDA multiple comparison. Do not let the framing of the number influence how you feel about the price before you have run your own cap rate analysis.

    Truth 4: NOI and EBITDA Are Not Always Calculated the Same Way

    This is where cap rate vs EBITDA multiple gets genuinely tricky, not because the math is hard, but because the inputs vary. Finding the real NOI number in an RV park deal often means rebuilding the seller’s figure from scratch, and EBITDA calculations carry their own inconsistencies around what gets added back. Two brokers can hand you two different numbers for the exact same park depending on what they chose to include, regardless of whether they call it NOI or EBITDA.

    Truth 5: Cap Rate vs EBITDA Multiple Does Not Replace Your Own Underwriting

    Both numbers are shorthand, and shorthand is exactly what gets buyers into trouble when they skip the underlying work. A cap rate or a multiple tells you how the market is framing a deal, not whether the deal actually works for you. Your own return on investment analysis still has to happen regardless of which number is printed on the listing.

    Putting Cap Rate vs EBITDA Multiple Into Practice

    Next time you see a listing quoted as an 11x multiple, do the quick math, divide 1 by 11, and you get roughly a 9 percent cap rate. That single conversion lets you compare it directly against every other cap rate deal you are evaluating, no matter how the broker chose to present it. Understanding cap rate vs EBITDA multiple is not about picking a favorite metric, it is about being able to speak both languages fluently so no listing catches you off guard.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    Full explanation of the cap rate and EBITDA multiple relationship is available via Breaking Into Wall Street.

  • Fractional CFO vs CPA: 5 Powerful Differences RV Park Owners Need to Know

    Fractional CFO vs CPA: 5 Powerful Differences RV Park Owners Need to Know

    Fractional CFO vs CPA is a question I get constantly from RV park owners, usually phrased as “don’t I already have someone for that?” The honest answer is almost always no, not for what a Fractional CFO actually does. Your CPA and a Fractional CFO serve different functions, and understanding the Fractional CFO vs CPA distinction is the first step toward knowing what your business actually needs.

    1. A CPA Looks Backward, a Fractional CFO Looks Forward

    This is the core of the Fractional CFO vs CPA distinction. A licensed CPA specializes in tax preparation, auditing, bookkeeping, and financial consulting, almost all of it grounded in reporting what already happened. A Fractional CFO spends most of their time on what happens next, cash flow projections, reserve planning, financing decisions. Both roles matter, but the Fractional CFO vs CPA comparison comes down to historical accuracy versus forward-looking strategy. Becker

    2. A CPA Files Your Taxes, a Fractional CFO Builds the System That Feeds Them

    Your CPA needs clean numbers to do their job well, and a Fractional CFO is often the one who builds the reporting system that makes those numbers clean in the first place. Your bookkeeper is not enough to keep your books audit-ready year round, and that gap is exactly where a Fractional CFO steps in. Nobody in the Fractional CFO vs CPA conversation should feel like they have to choose one over the other, they work best together.

    3. A CPA Is Reactive, a Fractional CFO Is Proactive

    CPAs typically engage a few times a year, tax season being the obvious example. A Fractional CFO is embedded in your business monthly, sometimes weekly, catching cash flow problems while they are still small. This proactive posture is a major piece of the Fractional CFO vs CPA difference, because the things your bookkeeper should be telling you but isn’t are usually things a Fractional CFO is already watching for on a regular cadence.

    4. A CPA Rarely Understands RV Park Seasonality, a Fractional CFO Should Live in It

    General accounting knowledge does not automatically translate to outdoor hospitality expertise. A CPA working across dozens of unrelated industries may not flag a seasonal cash flow risk that is obvious to someone who works exclusively with RV parks. This is where the Fractional CFO vs CPA question gets specific to your industry, not just your business size.

    5. A CPA Is Not Positioned to Be Your Strategic Partner, a Fractional CFO Is

    Working with entrepreneurs directly rather than treating every client the same is part of what separates a Fractional CFO from a CPA relationship built around compliance deadlines. The Fractional CFO vs CPA gap shows up most clearly here, in whether someone is simply keeping you compliant or actually helping you make better decisions. Having a CFO is like having a partner you don’t have to give up equity to.

    You Likely Need Both, Not One Instead of the Other

    The Fractional CFO vs CPA question is rarely an either-or decision. Your CPA keeps you compliant and files accurate returns. A Fractional CFO keeps your business financially healthy between those filings and helps you make the decisions that actually grow the business. Understanding what a Fractional CFO does day to day makes the Fractional CFO vs CPA distinction much easier to see, and much easier to act on.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    Full details on what CPA licensure actually covers are available via Becker.

  • RV Park CFO: 5 Powerful Things That Happen After Closing That You May Not Be Thinking About

    RV Park CFO: 5 Powerful Things That Happen After Closing That You May Not Be Thinking About

    An RV park CFO is not just a set of eyes during acquisition, gone the moment the deal closes. That is the most common misconception I run into, and it undersells what an RV park CFO actually does for an owner over time. Most people are not thinking about what an RV park CFO does after closing, because the acquisition gets all the attention and the real work happens quietly after everyone else has moved on.

    Most owners bring someone in to help underwrite the deal, and then assume the financial work is done once the keys change hands. It is not. The first three years of ownership are exactly when the financial decisions get harder, not easier, and that is where an RV park CFO earns their keep.

    1. An RV Park CFO Builds the Financial Systems Before Anything Else

    Before any strategic advice matters, the foundation has to exist. An RV park CFO makes sure the financial system is built correctly before you close, not scrambled together in month four once the reporting gaps become obvious. This groundwork is unglamorous, and it is also the single thing that determines whether every later decision is based on real numbers or guesswork.

    2. An RV Park CFO Runs the Monthly Financial Review So You Do Not Have To

    Ownership gets busy fast. Guests, staff, maintenance, all of it pulls attention away from the numbers. An RV park CFO builds the monthly financial review into a standing discipline, catching problems in month three instead of month eleven, when they are still cheap and easy to fix rather than expensive and urgent.

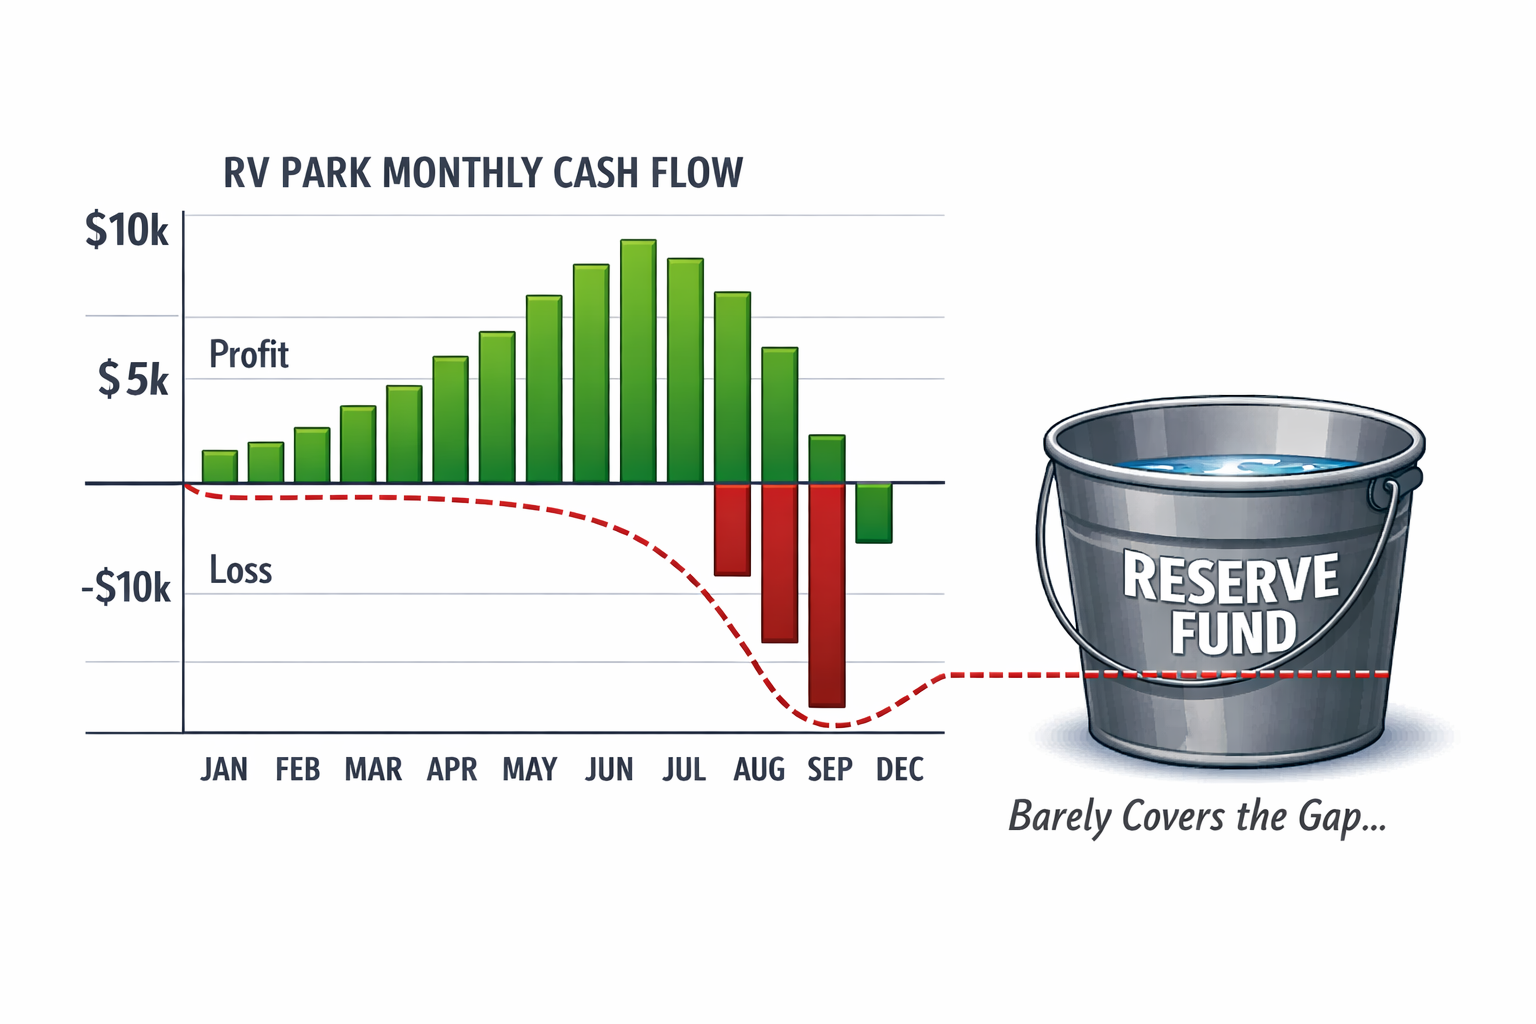
    3. An RV Park CFO Stress Tests Cash Flow Before the Off Season Arrives

    Seasonal businesses live or die by how well they prepare for the trough months. An RV park CFO models cash flow against your actual worst month, builds a real debt service reserve, and makes sure the business can survive its slowest stretch without a scramble. This is exactly the kind of forward-looking work that a bookkeeper focused on historical reporting simply is not positioned to do.

    4. An RV Park CFO Catches the Decisions a Generalist Advisor Would Miss

    Every business advisor is not the same, and outdoor hospitality has enough quirks, seasonality, site mix, capital reserve timing, that generic small business advice does not fully apply. Financial management resources like SCORE do a great job with general small business fundamentals, but an RV park CFO brings the specific context needed to apply those fundamentals correctly to a seasonal, capital-intensive outdoor hospitality asset.

    5. An RV Park CFO Prepares You for What Comes Next, Whether That Is Growth or Exit

    By year three, the questions change. Should you refinance? Add sites? Sell? An RV park CFO has been tracking your numbers long enough to answer those questions with real data instead of instinct, and that longitudinal view is something a one-time acquisition consultant never builds because they are gone before year one even starts.

    Why This Part of the Job Deserves More Attention

    The acquisition gets all the attention, but the years that follow are where an owner’s financial outcome actually gets decided. An RV park CFO who stays engaged after closing catches the small issues before they become big ones, keeps your reserve and cash flow honest, and gives you a real strategic partner as your ownership goals evolve. What a Fractional CFO actually is and what an RV park CFO does day to day are two very different questions, and the second one is where the real value lives, quietly, long after the closing table is a memory.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    For general small business financial management resources, SCORE offers free mentoring and educational content worth exploring alongside your RV park CFO relationship.

  • RV Park Revenue Mix: 5 Simple Truths About Transient vs Annual Sites Nobody Explains

    RV Park Revenue Mix: 5 Simple Truths About Transient vs Annual Sites Nobody Explains

    Your RV park revenue mix, the split between transient sites and annual sites, is one of the most misunderstood numbers in this business. Buyers glance at total occupancy and call it a day. Owners chase whichever booking fills a site fastest without thinking about what that choice does to their RV park revenue mix over time. Neither approach tells you what you actually need to know, and both leave real money and real risk sitting on the table.

    I look at RV park revenue mix on every deal I underwrite, and I look at it again with every ongoing client, because it is not a number you set once and forget. It shifts every season, and if nobody is watching it deliberately, it drifts toward whatever is easiest rather than what actually serves the business.

    Truth 1: A Strong RV Park Revenue Mix Is Not About Which Site Type Earns More

    The instinct is to ask which is better, transient or annual, and pick a side. That is the wrong question. A healthy RV park revenue mix is not about one site type beating the other, it is about balance. Transient revenue captures peak season upside, the premium nightly rates that come with high demand weekends and holiday weeks. Annual revenue provides stability through your slow months, when transient bookings all but disappear. The right RV park revenue mix uses both deliberately instead of drifting into whatever the market happens to fill first.

    Truth 2: Your RV Park Revenue Mix Directly Affects Your Risk Profile

    A park running 100 percent transient carries a completely different risk than a park with 30 percent of sites on monthly or annual contracts, even with identical trailing NOI. Lenders and buyers increasingly look past the top line and ask about the underlying RV park revenue mix, because sticky annual revenue holds up in a soft season in a way that transient revenue simply does not. If you are evaluating occupancy rate without also looking at the mix behind it, you are only seeing half the picture. Two parks can show the exact same occupancy percentage and carry entirely different risk depending on their RV park revenue mix underneath that number.

    Truth 3: Demand Is Not Going Anywhere, So the Mix Decision Matters More, Not Less

    Camping demand has stayed remarkably steady. The most recent industry research shows over 52 million North American households camped in 2025, exceeding pre-pandemic levels. That means the transient side of your RV park revenue mix has a real demand base behind it, but steady demand does not mean you should chase transient revenue exclusively. It means you have room to be selective about which sites stay transient and which convert, because you are not underwriting against a shrinking pool of campers. A stable RV park revenue mix built on real demand data is a far stronger foundation than one built on a guess about what next season might bring. PR Newswire

    Truth 4: Your Nightly Rate Should Inform Your RV Park Revenue Mix, Not the Other Way Around

    A lot of owners set their nightly rate first and let the RV park revenue mix fall out wherever it lands. That is backwards. Price your transient sites at what the market will actually bear, then look honestly at whether that rate, net of turnover and marketing cost, beats an annual lease on that same site.

    Here is a simple way to see it. If a transient site grosses $850 a month during peak season but only $200 a month for five off-peak months, its blended annual revenue may land close to what a $450 a month annual lease would deliver, minus all the turnover cost, cleaning, and vacancy risk the transient number carries with it. Let the real numbers decide your RV park revenue mix, not habit or whatever felt right when you first opened.

    Truth 5: OTA Dependency Skews Your RV Park Revenue Mix Without You Noticing

    Heavy reliance on booking platforms pushes owners toward a transient-heavy RV park revenue mix by default, simply because that is what the platform sells best. The real cost of OTA dependency includes this hidden effect on your mix, not just the commission fees you already know about. If your booking channels are quietly deciding your RV park revenue mix for you, it is worth stepping back and deciding on purpose instead of letting an algorithm optimize for its own commission rather than your long term stability.

    How to Actually Audit Your RV Park Revenue Mix

    Start by pulling your current site list and marking each site as transient or monthly/annual. Calculate what percentage of your total revenue comes from each category, not just what percentage of sites. Revenue percentage and site count percentage rarely match, and the revenue split is the number that actually matters for your RV park revenue mix. From there, identify which transient sites are underperforming relative to what an annual lease would deliver net of costs, and treat those as your first conversion candidates. Revisit this audit at least once a year, since your RV park revenue mix should evolve as your market, your costs, and your ownership goals change.

    Getting Your RV Park Revenue Mix Right

    Look at your site list the way you would look at an investment portfolio. Some sites should stay transient because peak demand justifies it. Others should convert to monthly/annual because the stability is worth more than the upside. I wrote about exactly how to make that site by site call in RV park annual site conversion, which walks through the full comparison in detail. Your RV park revenue mix is not a number that happens to you, it is a decision you can and should actively manage, one that shows up directly in your valuation the next time you go to sell.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    Full data on camping demand trends is available in the KOA Camping & Outdoor Hospitality Report.

  • RV Park Loan Structure: 5 Dangerous Blind Spots Buyers Miss Before They Sign

    RV Park Loan Structure: 5 Dangerous Blind Spots Buyers Miss Before They Sign

    Your RV park loan structure comes up in nearly every conversation I have with buyers, and almost every one of those conversations starts the same way. They ask what structure is “best,” as if there is one right answer, when the real question is which RV park loan structure fits this specific deal, this specific buyer, and this specific park’s cash flow pattern.

    There is no universal answer, and buyers who go looking for one usually end up with a structure that fits the lender’s preferences better than their actual deal.

    Blind Spot 1: Assuming Agency Financing Is an Option

    This one catches buyers off guard constantly. Fannie Mae and Freddie Mac dominate financing for manufactured housing communities, but their programs explicitly exclude RV parks entirely. Freddie Mac’s own manufactured housing loan guidelines state plainly that no RV resorts are allowed under the program. If your RV park loan structure conversation starts with agency debt, it is starting in the wrong place. SBA 7(a) financing and specialty commercial lenders are where the real options live. Multifamily Loans

    Blind Spot 2: Not Understanding How Seller Carry Fits Into the Structure

    Seller financing sounds simple until you are the one negotiating the terms. Analyzing a seller carry deal means understanding how it interacts with your senior debt, not just whether the interest rate sounds reasonable. A seller carry piece that looks generous on paper can quietly weaken the overall structure if it is not stacked correctly against your primary loan.

    Blind Spot 3: Underestimating What a Zero Down Structure Actually Costs You

    Zero down deals get buyers excited, and they should also make buyers cautious. The hard truths about zero down RV park financing usually involve higher rates, tighter covenants, or a seller carry piece stacked on top of primary debt in a way that strains cash flow the moment occupancy dips. A zero down RV park loan structure is not free money, it carries a different risk profile entirely.

    Blind Spot 4: Not Stress Testing It Against a Slow Season

    Every RV park loan structure needs to survive your worst month, not your average month. Buyers who build around peak season assumptions are setting themselves up for exactly the kind of trouble that shows up on an SBA loan default analysis. The right structure accounts for seasonality from day one, not as an afterthought once payments are already due.

    Blind Spot 5: Treating It as Someone Else’s Job to Figure Out

    This is the one I see most often. Buyers hand the whole thing entirely to their lender or broker and assume the terms offered are the only terms available. They rarely are. A full pre-qualification package built correctly gives you leverage to negotiate your RV park loan structure, not just accept whatever is presented first.

    Why This Is Exactly Where a Fractional CFO Earns Their Fee

    Your RV park loan structure touches every other number in your deal, your DSCR, your reserve requirements, your first year cash flow, your exit timeline. Getting it wrong does not just cost you at closing, it follows you through every month of ownership. This is precisely the kind of decision where a second set of experienced eyes, someone who has underwritten the structure independently of the lender or the seller, changes the outcome.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    Full details on Freddie Mac’s manufactured housing loan exclusions are available via Multifamily.Loans.


  • RV Park Deferred Maintenance: The 5 Brutal Surprises Hiding Behind Every “Move-In Ready” Park

    RV Park Deferred Maintenance: The 5 Brutal Surprises Hiding Behind Every “Move-In Ready” Park

    RV park deferred maintenance is the line item that quietly wrecks more first year budgets than any other single issue I see in this business. Buyers walk a park, everything looks fine on the surface, and three months after closing they are staring at a $40,000 electrical upgrade nobody flagged during diligence.

    Deferred maintenance does not announce itself. It hides behind a working pedestal that will not pass code, a septic system that functions until it does not, and roads that look fine until the first hard freeze. RV park deferred maintenance is exactly the kind of cost that separates a buyer who underwrote the deal correctly from one who is scrambling to cover an unplanned capital expense in year one.

    Why RV Park Deferred Maintenance Directly Affects What You Should Pay

    This is not just an operational headache, it is a valuation issue. Real estate transaction guidance is direct about this: deferred maintenance directly reduces a property’s fair market value, and buyers and their appraisers adjust the offer price downward by the estimated cost to cure the deferred items. If you are not identifying RV park deferred maintenance during diligence, you are almost certainly overpaying, whether or not the seller disclosed anything. Barnes Walker

    Mistake 1: Relying on a Visual Walkthrough Instead of a Real Inspection

    A walkthrough tells you what is visible. RV park deferred maintenance often lives underground, in septic lines, electrical panels, and water infrastructure that a casual walk will never surface. What to look for in RV park utility infrastructure goes well beyond a visual check, and skipping that depth is exactly how RV park deferred maintenance gets missed until it becomes an emergency.

    Mistake 2: Trusting the Seller’s Maintenance Log Without Verification

    Sellers do not always track RV park deferred maintenance accurately, and sometimes they do not track it at all. A maintenance log that shows nothing outstanding does not mean nothing is outstanding, it might just mean nobody wrote it down. Cross reference the log against your own inspection findings and treat any gap as a red flag worth investigating further.

    Mistake 3: Underestimating How Fast Small Issues Become Expensive Ones

    RV park deferred maintenance compounds. A small roof leak left alone becomes structural rot. A minor electrical issue left unaddressed becomes a full panel replacement. The maintenance cost surprises that ambush new owners are almost always issues that could have been caught and priced during diligence, before they had years to compound into something far more expensive.

    Mistake 4: Not Pricing RV Park Deferred Maintenance Into Your Offer

    Finding deferred maintenance during diligence only helps you if you actually use it. Too many buyers document the issues, feel good about having “caught” them, and then make an offer that does not reflect the real cost to cure. Your due diligence checklist should feed directly into your offer price, not just sit in a folder as documentation.

    Mistake 5: Skipping a Professional Property Condition Assessment to Save Money

    A full property condition assessment costs money upfront, and it is one of the cheapest insurance policies you will buy during an acquisition. Professional assessors typically price documented RV park deferred maintenance as an immediate repair cost, often escrowed at the closing table rather than left as an assumption. Skipping this step to save a few thousand dollars on diligence can cost you tens of thousands after closing.

    How to Actually Handle RV Park Deferred Maintenance During Diligence

    Get a real inspection, not a walkthrough. Verify the seller’s maintenance records against what you actually find. Price every identified issue and build it into your offer or your closing escrow. And do not assume small issues will wait, because RV park deferred maintenance rarely waits, it compounds.

    Get the number wrong here and everything downstream becomes wrong with it. The appraised value is wrong, the debt service coverage ratio is wrong, the loan gets sized incorrectly, and years down the road the septic system still needs replacing whether your underwriting acknowledged it or not. RV park deferred maintenance does not disappear because it was left out of the model, it just waits.

    Buyers who take this seriously during diligence walk into ownership with a real capital plan instead of a surprise. Buyers who skip it find out the hard way, usually in their first winter, exactly what RV park deferred maintenance costs when nobody priced it ahead of time.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    Further reading on how deferred maintenance is priced during property condition assessments is available from MMCG Investments.

  • RV Park Reserve: 6 Essential Steps to Build a Debt Service Cushion Before Your Off Season Hits

    RV Park Reserve: 6 Essential Steps to Build a Debt Service Cushion Before Your Off Season Hits

    An RV park reserve is not optional if you own a seasonal business, and yet most owners never build one on purpose. They assume the strong months will carry them through the weak ones, and then February arrives and the reserve that was supposed to exist turns out to be whatever happened to be left in the checking account.

    That is not a reserve. That is luck, and luck runs out.

    Why an RV Park Reserve Matters More Than You Think

    Nationwide research on small business cash reserves paints a sobering picture. The median small business holds just 27 cash buffer days in reserve, meaning half of all small businesses hold an average daily cash balance that would cover fewer than four weeks of outflows if their income stopped. For a seasonal business like an RV park, where entire months can pass with minimal transient revenue, 27 days of cushion is nowhere near enough. JPMorgan Chase

    Real estate businesses tend to hold more cushion than the median, but an RV park reserve still has to be built deliberately. It does not happen by accident, and it does not happen just because your peak season was strong.

    Step 1: Calculate Your True Off Season Burn Rate

    Before you can size a reserve, you need to know exactly what your park costs to run during your slowest months. Pull your operating expenses for your worst two or three consecutive months and treat that number as your baseline burn rate, not your annual average.

    Step 2: Set Your RV Park Reserve Target in Months, Not Dollars

    A dollar figure that sounded like plenty two years ago may not cover today’s costs. Set the target as a number of months of off season burn rate instead, typically three to six months depending on how severe your seasonality runs. Revisit that target every year as your expenses change.

    Step 3: Separate the Reserve From Your Operating Account

    Reserve funds that live in the same account as daily operating cash get spent. It happens gradually and it happens without anyone deciding to do it. Move your RV park reserve into a separate account entirely, ideally one that is slightly harder to access than a debit swipe.

    Step 4: Fund It During Peak Season on Purpose

    Do not wait to see what is “left over” at the end of a strong month. Build a specific transfer into your peak season monthly financial review that moves a set percentage of revenue directly into the reserve before anything else gets spent.

    Step 5: Stress Test the Reserve Against Your Worst Month, Not Your Average Month

    Your RV park reserve needs to hold up against the worst month your books have actually shown, not a smoothed average across the year. If it would cover an average month but fall short during your actual trough, the target is too low.

    Step 6: Keep Capital Expenses Out of It

    Your reserve exists to cover operating shortfalls, not capital expenditures. Mixing the two means you will not know your true operating cushion, and a surprise capital repair can wipe out the fund meant to carry you through a slow month. Keep separate tracking for each.

    What Happens Without a Real RV Park Reserve

    Owners without one end up making expensive decisions under pressure, drawing on high interest credit, delaying necessary maintenance, or missing a debt service payment during a slow month that a properly sized reserve would have covered without incident. A well funded RV park reserve is not a luxury for a seasonal business, it is the difference between a rough winter and a defaulted loan.

    Build it in one deliberate step at a time, fund it during your strong months, and stress test it every year against your actual worst stretch, not an optimistic average.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    Full research on small business cash buffer days is available from the JPMorgan Chase Institute.

  • RV Park Bookkeeping First 90 Days: 7 Essential Systems That Save You From a Year of Cleanup

    RV Park Bookkeeping First 90 Days: 7 Essential Systems That Save You From a Year of Cleanup

    RV park bookkeeping in the first 90 days is where most new owners either build a business they can actually manage or bury themselves in a mess they will spend years digging out of. I have watched both happen, and the difference almost always comes down to whether RV park bookkeeping got set up in week one or got pushed to “whenever things calm down.”

    Things do not calm down. You close on a park, guests keep arriving, vendors keep invoicing, and if your RV park bookkeeping is not set up before day one, you are reconstructing three months of transactions from memory by the time you realize you need it.

    Why RV Park Bookkeeping Cannot Wait Until You Feel Settled

    Every seller’s financials look different from your financials the moment you take over. The seller’s RV park bookkeeping reflected their chart of accounts, their categorization habits, and often their own shortcuts. You are starting a new set of RV park bookkeeping, not inheriting theirs, and the first 90 days is when that new system either gets built correctly or gets built badly under pressure.

    This is also the window the IRS cares about most. Federal recordkeeping guidance is clear that your recordkeeping system should include a summary of your business transactions, made in your business books, and your books must show your gross income as well as your deductions and credits. Waiting to set up RV park bookkeeping properly does not just cost you clarity, it puts your deductions at risk if you cannot reconstruct clean records later. Internal Revenue Service

    The 7 Essential RV Park Bookkeeping Systems for Your First 90 Days

    1. Open a dedicated business bank account on day one. If you are still running park expenses through a personal account or your old business account from a different entity, stop immediately. RV park bookkeeping starts with a clean separation between personal and business money, full stop.

    2. Build a real chart of accounts before you record a single transaction. A generic QuickBooks template will not capture what actually matters for an RV park. Your chart of accounts needs to separate site rent revenue by type, utility reimbursements, store or amenity income, and every major expense category specific to outdoor hospitality. RV park bookkeeping built on a generic template creates messy reports for the next three years.

    3. Set up the connection between your PMS and your books. Whatever reservation or property management software you are running, it needs to feed into your RV park bookkeeping cleanly, either through direct integration or a consistent manual process. This is where a lot of RV park bookkeeping quietly breaks down, because reservation revenue and booked revenue drift apart within weeks if nobody is reconciling them.

    4. Reconcile your bank account weekly for the first 90 days, not monthly. Your bank balance can lie to you if you are not checking it against your RV park bookkeeping regularly, especially with deposits arriving from multiple sources like OTAs, direct bookings, and long-term tenants. Weekly reconciliation in the early months catches errors while they are still small.

    5. Establish a monthly financial review before you need one. Do not wait for a crisis to look at your numbers. A structured monthly financial review built into your RV park bookkeeping from month one means you catch problems in week five, not month eleven.

    6. Get your 1099 and vendor documentation collected up front. Every contractor doing work on your park during those first 90 days, landscaping, septic, electrical, needs a W-9 on file before you cut the first check, not after. Good RV park bookkeeping treats this as a requirement, not a preference, and it is far easier to collect at the start of the relationship than to chase down later.

    7. Decide on your reserve and capex tracking method immediately. RV park bookkeeping that lumps capital expenses in with operating expenses makes it nearly impossible to see your true operating performance. Set up separate tracking for reserves and capital spending from the very first month.

    What Skipping RV Park Bookkeeping Early Costs You Later

    It is almost always more expensive to fix RV park bookkeeping months later than to build it correctly from day one. Reconstructing three or four months of transactions means digging through bank statements, guessing at categorizations, and often losing legitimate deductions because the documentation was never collected properly in the moment. A real financial system built before you close costs a fraction of what it costs to clean up messy RV park bookkeeping later. I recently worked with a client who took over an existing LLC, and the books needed $6,700 in cleanup work before I could even begin regular bookkeeping.

    The first 90 days of RV park bookkeeping is not glamorous work, but it is the foundation everything else sits on. Get your RV park bookkeeping right now, and your monthly reviews, your tax filings, and your eventual exit all get easier. Get it wrong, and someone, possibly me, ends up untangling it later.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

    Full IRS guidance on business recordkeeping requirements is available at irs.gov.

  • RV Park Annual Site Conversion: 5 Proven Moves Institutional Buyers Are Making That Mom and Pop Owners Can Steal

    RV Park Annual Site Conversion: 5 Proven Moves Institutional Buyers Are Making That Mom and Pop Owners Can Steal

    RV park annual site conversion is the smart move the biggest players in outdoor hospitality have been making for years, and most small owners still are not doing it on purpose. RV park annual site conversion has become one of the clearest gaps between how institutions run parks and how independent owners run parks.

    I look at RV park deals every week, and I still see the same pattern. A park has forty sites, all of them booked nightly or weekly through an OTA, and the owner treats every single one of those bookings as a win. It is not. Filling a site with transient guests night after night is the hardest way to earn revenue in this business, and it is often the least profitable way too. RV park annual site conversion exists precisely to solve that problem.

    Why RV Park Annual Site Conversion Became an Institutional Strategy

    Sun Communities, one of the largest owners of RV communities in North America, has publicly reported on RV park annual site conversion for years. Starting in 2020, they proactively converted over 8,000 sites from transient to annual, improving the consistency of earnings and the durability of cash flows in the portfolio. That is not a small test. That is a company-wide repositioning of how they generate revenue, built entirely around annual site conversion at scale. Investing.com

    The math behind annual site conversion is simple once you see it laid out. A transient site depends on daily or weekly turnover, marketing spend, cleaning between stays, and constant occupancy management. An annual site gets rented once and stays rented, usually for a full year or longer, with a predictable monthly payment and almost no turnover cost. One is a hotel room. The other is closer to a small apartment lease. That is the entire case for RV park annual site conversion in one comparison.

    That said, even Sun Communities has recently pulled back from aggressive annual site conversion. Their more recent guidance shows a shift toward a more balanced mix between transient and annual, using data to decide site by site rather than converting everything possible. That nuance matters. RV park annual site conversion is a tool, not a rule, and the institutions figured that out after several years of pushing hard on it.

    What RV Park Annual Site Conversion Means If You Are Buying a Park

    If you are underwriting a deal right now, the site mix on the rent roll tells you more about future annual site conversion potential than the RV park occupancy rate ever will. A park that shows 95 percent occupancy sounds great until you realize every one of those sites is a nightly rental dependent on weather, gas prices, and whatever online travel agent dependency the seller has built the business around.

    When I underwrite a deal, I am looking for how much of the current NOI comes from sticky, contracted revenue versus revenue that could disappear the moment a competitor drops their rate. A park with even 20 to 30 percent of sites already converted to annual is a fundamentally different risk profile than a park running 100 percent transient, even if the trailing NOI on paper looks identical. Untapped annual site conversion potential should show up directly in how you think about RV park valuation and where you land on cap rate.

    What RV Park Annual Site Conversion Means If You Already Own a Park

    You do not need to be a REIT to steal the RV park annual site conversion strategy. If you own a park right now, walk your site list and ask a simple question for each one: is this site earning what it could as an annual site, or is it earning what it currently earns as a transient site, and which number is bigger once you account for turnover, cleaning, marketing, and vacancy risk?

    Not every site should convert. Peak season transient revenue on a well located site can outperform an annual lease, especially in destination markets with strong weekend and holiday demand. That is exactly why Sun Communities moved away from converting everything and toward a data driven approach to annual site conversion. The move is not “convert every site.” The move is “know your numbers well enough to choose correctly, site by site.”

    This is where a real financial system matters more than most owners expect. You cannot make an annual site conversion decision off a gut feeling about which sites “always seem full.” You need a clean nightly rate breakdown against annual lease comparables in your market, and you need it broken out cleanly in your books, not buried in one lump revenue line.

    Here is how to actually run the RV park annual site conversion comparison, site by site.

    Step 1: Pull the trailing 12 months of actual revenue for that specific site. Not the park average, not what you charge on paper. What that site actually collected, including every discount, every empty week, and every cleaning fee you had to eat between bookings. This is the raw data every RV park annual site conversion decision has to start with. Most owners are shocked at this number once they isolate it. A site that “feels full” is often full at a discounted rate half the time, not full at rack rate.

    Step 2: Subtract the real cost of running it as a transient site. This means the cleaning and turnover labor between every stay, the portion of your OTA commission tied to that site’s bookings, the marketing spend allocated to keep it filled, and a reasonable estimate of the vacancy days you are not tracking closely enough. Owners consistently underestimate this line, and it is exactly what makes RV park annual site conversion look better once the true cost is on the table. Turnover cost on a 40 percent annual occupancy pattern adds up fast when you actually itemize it instead of eyeballing it.

    Step 3: Price out the annual lease alternative for that same site. Call two or three comparable parks in your market, or check what long-term RV lot rents are running locally, and get a real monthly number. Multiply by 12. Subtract essentially nothing for turnover, since an annual tenant might turn over once every year or two instead of every few days. This is the number you are actually weighing against transient revenue in every RV park annual site conversion decision.

    Step 4: Compare net, not gross, this is the core of any RV park annual site conversion decision. This is the step almost everyone skips. A transient site that grosses $9,000 a year might net $6,200 after turnover costs and vacancy. An annual site at $450 a month nets close to $5,400 with almost no additional cost to you. On paper the transient number looks bigger. Net, they are nearly identical, and the annual site carries a fraction of the operational headache and none of the seasonal risk.

    Step 5: Weight for seasonality and location. A site on your best lake view row during peak season might genuinely outperform annual conversion, and should probably stay transient. A site near the entrance, by the dumpster, or in a section that fills last should usually convert first. This is exactly the sorting exercise Sun Communities does at scale to guide RV park annual site conversion, just applied to a park with dozens of sites instead of thousands.

    Do this math for every site, and you end up with a ranked list instead of a guess. That ranked list is what actually tells you which sites to convert first, which ones to leave alone, and how much annual site conversion is worth to your specific park rather than to the industry in general.

    The RV Park Annual Site Conversion Advantage Nobody Talks About

    Here is the part that should genuinely change how you think about acquisitions. If you can identify a park where the seller has left obvious annual site conversion opportunity on the table, you are not just buying current cash flow. You are buying a proven path to increase revenue without adding a single site, without a capital project, and without waiting on a rezoning or expansion approval.

    That is exactly the kind of value-add story institutional buyers build acquisition models around, and RV park annual site conversion is available to a buyer with forty sites just as much as a buyer with four hundred. The difference is whether you know to look for it and whether you have the financial systems in place to actually execute and track annual site conversion after you close.

    If you want to go deeper on how RV park financials actually work, everything I have written on acquisitions, bookkeeping, and cash flow lives in the RV Park Resource Library. And if you want the full framework for evaluating a deal from first look through your first ninety days of ownership, that is exactly what I built into From Offer to Operation, available on Gumroad or by searching Amazon for the title.

  • RV Park Pricing Around Events: 5 Powerful Moves Most Owners Miss

    RV Park Pricing Around Events: 5 Powerful Moves Most Owners Miss

    Right now, RV parks near World Cup host cities are seeing exactly the kind of demand spike that most owners either miss entirely or only half capture. Supply near host cities more than tripled for the June host window this year, and nightly rates across those markets ranged anywhere from 41 dollars to over 220 dollars a night depending on the property. That is a massive spread, and the difference between the low end and the high end almost always comes down to one thing, whether the owner actually thought through RV park pricing around events or just left their rates where they always are.

    Here is the mistake I see constantly. An owner knows a big event is coming, a festival, a sporting event, a regional fair, something that is going to pull outside visitors into the area who need somewhere to park an RV. And then nothing changes. Same nightly rate, same booking rules, same site allocation, as if the demand spike simply is not happening. RV park pricing around events is one of the most straightforward revenue opportunities in this entire business, and it gets left on the table constantly.

    Why RV Park Pricing Around Events Gets Overlooked

    Most day to day pricing advice in this industry focuses on baseline strategy, seasonal rate tiers, long term stay discounts, weekday versus weekend rates. All of that matters, but it is built around predictable, recurring patterns. A major local event is a different animal entirely, a short, sharp demand spike that does not fit neatly into a seasonal pricing calendar, and RV park pricing around events requires a completely different kind of attention than your standard seasonal adjustments.

    Part of the problem is timing. Owners often find out about a nearby event the same way everyone else does, close to when it happens, instead of tracking event calendars for their region months in advance. By the time the demand is obvious, the window to plan RV park pricing around events properly has already narrowed. Hotels in the same markets typically start adjusting rates weeks or months ahead of a known event. RV parks, by comparison, often react only once the phone starts ringing.

    There is also a hesitation factor. Raising rates around a big event can feel uncomfortable, like you are taking advantage of a captive audience. But this is standard practice across every part of the hospitality industry, and RV park pricing around events done well is not about gouging guests, it is about matching your rate to actual demand the same way hotels, short term rentals, and airlines have done for decades.

    What Smart RV Park Pricing Around Events Actually Looks Like

    It starts with tracking regional events well in advance. Concerts, sporting events, festivals, and conferences near your market all create demand spikes you can plan for if you know about them early. RV park pricing around events only works if you have enough lead time to actually adjust rates and booking rules before demand hits.

    It adjusts nightly rates to reflect real demand, not guesswork. A modest rate increase during a known high demand window is standard across hospitality. RV park pricing around events should reflect the same principle hotels use every day, higher demand justifies a higher rate, and guests expect this during major events.

    It protects your regular guests from being squeezed out entirely. Smart RV park pricing around events does not mean selling every single site to event traffic at premium rates. Holding back a portion of your inventory for regular guests and long term stays protects the relationships that keep your park full the other 350 days of the year.

    It adjusts minimum stay requirements, not just nightly rates. Many hotels and short term rentals require minimum multi night stays during major events to maximize revenue per booking. RV park pricing around events can use the same tool, requiring a two or three night minimum during a known demand spike instead of accepting single night bookings that leave gaps in your calendar.

    It gets communicated clearly, not sprung on guests at checkout. Rate changes during high demand periods should be visible at the time of booking, not a surprise. Transparent RV park pricing around events protects your reviews and your reputation just as much as it protects your revenue.

    How to Build a Real Event Pricing Strategy

    Build a running calendar of regional events, not just a mental note. Local tourism boards, chamber of commerce calendars, and event ticketing sites all publish schedules months ahead of time. This is the foundation RV park pricing around events actually depends on.

    Set your rate increases in advance, tied to specific dates. Decide your event pricing tiers before the demand hits, not in the moment. If cash flow planning during your regular season already feels reactive rather than proactive, my post on RV park cash flow planning covers a similar shift from reacting to planning ahead.

    Track your booking pace leading into a known event. If reservations are filling faster than usual as an event approaches, that is your signal to adjust rates further before you sell out at yesterday’s price.

    Keep your books clean enough to actually measure whether it worked. RV park pricing around events only proves its value if you can see the revenue lift clearly afterward, which depends on financials that are current and properly segmented. I covered why that segmentation matters in my post on RV park bookkeeping.

    Loop event pricing into your broader financial picture, not just a one-off decision. A well planned event pricing strategy adds real, measurable revenue across a season, and that revenue should show up in the same models you use for reserves and debt service. This is exactly the kind of forecasting work I build into ongoing Fractional CFO support for park owners.

    RV park pricing around events is one of the simplest revenue tools available in this business, and it is also one of the most consistently ignored. The RV Industry Association’s research hub is a solid outside resource if you want to track broader demand trends shaping your regional market beyond just individual events.

    If you want help building an actual event pricing calendar and connecting it to your broader financial plan, that is exactly the kind of work I do. Reach out at PVIFinancial.com.

    For more on running a profitable, well managed park, check out my Resource Library, and grab a copy of my book From Offer to Operation: The Complete RV Park Investor’s Guide, also available on Amazon.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • RV Park Staff Turnover: 5 Alarming Costs Job Boards Never Mention

    RV Park Staff Turnover: 5 Alarming Costs Job Boards Never Mention

    Search for anything on RV park staff turnover and you will land almost entirely on job board content and hiring guides. What a manager’s job responsibilities look like, how many years of experience a candidate should have, how to write a better job posting. All useful in its own way, but almost none of it treats RV park staff turnover as what it actually is, a direct hit to your bottom line that shows up in your financial statements whether you are tracking it or not.

    Here is what gets missed. Every time someone walks out the door, whether it is a front desk employee, a maintenance worker, or a park manager, that departure carries a real dollar cost. Recruiting time, onboarding, training, the productivity gap while someone learns the job, and the guest experience dip that happens along the way. RV park staff turnover is not just an HR headache. It is a financial event, and treating it as anything less means you are almost certainly underestimating what it costs you every single year.

    Why RV Park Staff Turnover Gets Treated as an HR Problem Instead of a Financial One

    Most of the content written on this topic comes from staffing platforms and recruiting sites, and it shows. The focus stays on job descriptions, interview tips, and experience levels, which makes sense given who is writing it. But RV park staff turnover has a real number attached to it, and that number belongs in your financial planning, not just your hiring checklist.

    Hospitality as a broader industry sees annual turnover rates far higher than most other sectors, and seasonal outdoor hospitality businesses like RV parks often see even sharper swings, with full seasonal staff turning over more than once a year. Industry research on hospitality turnover puts the replacement cost per hourly position anywhere from several thousand dollars up into the tens of thousands once you account for recruiting, training time, and the productivity gap during the learning curve. None of that shows up as a line item labeled “turnover” on a typical P&L, which is exactly why RV park staff turnover is so easy to underestimate until you actually sit down and calculate it.

    There is also a guest experience cost that compounds the financial one. A new front desk hire fumbles a check-in. A new maintenance worker takes longer to spot a problem an experienced one would have caught immediately. RV park staff turnover does not just cost you in payroll and training, it costs you in the reviews and repeat bookings that depend on a smooth, consistent guest experience. I covered a version of this connection in my post on why your books and your guest experience are actually the same thing, and staffing consistency is a huge part of that same equation.

    What RV Park Staff Turnover Actually Costs You

    Direct replacement costs add up fast, even for seasonal roles. Recruiting, advertising, background checks, and onboarding time all carry a real dollar figure per hire, and RV park staff turnover in seasonal roles means paying that cost repeatedly across a single operating season.

    Training time pulls your best people away from their own work. Every new hire needs someone experienced to train them, and that time comes directly out of a manager or senior staff member’s productive hours. RV park staff turnover quietly taxes your most capable people even when they are not the ones leaving.

    The productivity gap during onboarding is real and measurable. A new hire is rarely as efficient as the person they replaced for the first several weeks. RV park staff turnover means paying full wages during a period of below average output, which is a cost that rarely gets modeled into a seasonal staffing budget.

    Guest experience takes a measurable hit. Businesses with high staff turnover in hospitality settings see noticeably more service related complaints than businesses with stable teams. RV park staff turnover shows up in your reviews just as much as it shows up in your payroll costs.

    A manager who is not empowered to fix small problems will struggle to reduce turnover on their own. If your manager can observe a staffing problem but has no real authority to address pay, scheduling, or working conditions, RV park staff turnover becomes a cycle that repeats every season regardless of how good your hiring process is.

    How to Actually Reduce What RV Park Staff Turnover Costs You

    Calculate your actual turnover cost instead of estimating it. Multiply your average replacement cost per position by the number of departures you had last season. Most owners are surprised by the real number once they run it, and that number belongs in your annual budget the same way any other operating expense does.

    Separate voluntary turnover from expected seasonal departures. Not all turnover is a problem. Seasonal workampers finishing their term is expected. Employees leaving mid-season because of pay, scheduling, or management issues is the piece worth investigating and fixing.

    Give your on-site manager real authority, not just responsibility. A manager who can adjust scheduling, address a pay concern, or resolve a working condition complaint on the spot can prevent a departure that a manager without that authority cannot. This connects directly to the same enforcement authority gap I wrote about in my post on RV park rule enforcement, where staff and guests both notice when someone in charge does not actually have the power to fix things.

    Build turnover costs into your seasonal staffing budget, not just your payroll line. If you know roughly what RV park staff turnover costs you per position, you can budget for a realistic number of replacements each season instead of being caught off guard by the total at year end. This is exactly the kind of modeling I build into ongoing Fractional CFO work with clients.

    Track the guest experience impact, not just the financial one. If your reviews start mentioning inconsistent service during a season with high turnover, that is not a coincidence. Watching both numbers together gives you a much clearer picture of what is actually happening in your business than looking at either one alone.

    RV park staff turnover is not just a staffing inconvenience you solve with a better job posting. It carries a real, calculable cost that touches your payroll, your training time, your guest reviews, and ultimately your occupancy. The Society for Human Resource Management’s research on how to reduce turnover through retention strategies is a solid outside resource if you want a broader framework for how these costs get measured across industries, even though it is not written specifically for outdoor hospitality.

    If you want help calculating what staff turnover is actually costing your park, or building that number into your annual budget, that is exactly the kind of work I do. Reach out at PVIFinancial.com.

    For more on running a profitable, well managed park, check out my Resource Library, and grab a copy of my book From Offer to Operation: The Complete RV Park Investor’s Guide, also available on Amazon.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • RV Park Loan Prequalification: The 9 Essential Documents My Lender Required and How to Get Each One Ready

    RV Park Loan Prequalification: The 9 Essential Documents My Lender Required and How to Get Each One Ready

    RV park loan prequalification is where most first-time buyers get their first real reality check. Not at the offer stage. Not at due diligence. At the moment their lender says “send me these documents” and the buyer realizes they do not have half of them ready.

    This is not a list of vague categories like “financial documents” or “proof of funds.” This is the actual list my lender required from me before they would move forward on an acquisition, item by item, along with what each one needs to say about you and how to get it in shape before you are asked for it. RV park loan prequalification moves fast once your paperwork is in order, and it stalls out completely when it is not. If there is one skill worth building before you ever call a broker, it is treating RV park loan prequalification like a project with a checklist, not a mystery box a lender hands you later.

    Why RV Park Loan Prequalification Happens Before You Find the Park

    Most buyers think the order of operations is: find a park, fall in love with it, then go get financing. That is backwards, and it costs people deals.

    A serious seller or broker wants to know you can actually close before they take your offer seriously, especially on a park that is priced right and getting attention from more than one buyer. RV park loan prequalification, done before you are under contract, tells a seller you are a real buyer and not someone testing the market. It also tells you, before you fall in love with a specific property, whether your financial picture supports the size of acquisition you are looking at.

    If you want to understand what your lender is doing with these numbers once they have them, read What a Lender Actually Looks at Before Approving an RV Park Loan. This post picks up before that conversation even starts, at the paperwork stage of RV park loan prequalification.

    The Core Document List Every Buyer Needs

    This is the baseline list. Every buyer going through RV park loan prequalification with an SBA-backed lender should expect to produce these six items regardless of how simple or complex their financial situation is.

    1. Last Three Years of Personal Tax Returns

    Your lender wants your complete personal filings, all schedules included, not just the summary pages. This is the single most scrutinized document in RV park loan prequalification because it is the hardest number to manipulate. Lenders trust a tax return more than almost anything else you can hand them, because it is the version of your finances you already swore was accurate to the IRS.

    How to get this ready: pull your full returns directly from your accountant or your own records, not a summary from your tax software. If any year included a one-time gain or loss, a business sale, a large capital gain, have a short written explanation ready. Underwriters ask about anomalies, and a buyer who can explain a number before being asked looks far more prepared than one who gets caught off guard.

    2. Personal Financial Statement

    This is a snapshot of everything you own and everything you owe, assets and liabilities, as of a specific date. Most lenders use their own form for this, usually SBA Form 413, so ask your lender for their preferred version rather than assuming a generic template will work.

    How to get this ready: list every asset at a realistic current value, not what you paid for it or what you hope it is worth. Include real estate, retirement accounts, business ownership stakes, vehicles, and cash. On the liability side, list every mortgage, loan, and line of credit with current balances. Round numbers and vague estimates slow this step down. Have actual statement balances in front of you when you fill this out.

    3. SBA Form 1919, the Borrower Information Form

    This is the SBA’s official borrower information form, and it is a required piece of RV park loan prequalification for any SBA 7(a) loan. It collects your basic identifying information, ownership structure, and background questions the SBA uses to run eligibility and background checks.

    How to get this ready: have your business legal name and structure clearly defined before you sit down to fill this out, along with identifying information for every owner with 20 percent or more equity in any entity involved in the deal. If you are buying through an LLC you are forming for this acquisition, know that structure and your ownership percentage before you start the form. The SBA’s own Form 1919 page has the current version if you want to see exactly what it asks before your lender sends it to you.

    4. Resume or Business Background Form

    Lenders want to see that you, or someone on your team, has relevant experience running a business, managing real estate, or operating in hospitality. You do not need to have owned an RV park before. I have never owned one myself and it has not stopped me from doing this work at a high level. What you do need is a clear, honest account of your professional background and why it positions you to run this specific asset.

    How to get this ready: write this like a business resume, not a job-search resume. Emphasize ownership experience, management experience, financial literacy, and any transferable skills, construction, hospitality, property management, customer service at scale. If you are partnering with someone who brings the operational experience you lack, say so directly. Lenders would rather see an honest gap covered by a partner than a resume stretched to hide one.

    5. Purchase Agreement or Letter of Intent

    Your lender needs to see the actual deal you are trying to finance: price, terms, and the specific property. Without this, RV park loan prequalification stays theoretical. A pre-approval based on your financials alone tells you what you can likely qualify for. A pre-approval with a signed LOI or purchase agreement attached is what actually moves a deal toward closing.

    How to get this ready: make sure the LOI or purchase agreement includes the full legal description of the property, the purchase price, any seller financing terms, and a financing contingency that gives you enough time to complete underwriting. This is another part where buyer’s often get tripped up, it often takes some time to get the documents you need from the seller to complete the underwriting, it is rarely something that comes together in just a few days. A financing contingency that is too short is one of the most common ways buyers accidentally box themselves into a bad negotiating position later in the deal.

    6. Three Months of Bank Statements for Down Payment

    Your lender needs to verify that your down payment funds are real, sourced, and seasoned, meaning they have been sitting in your account for a reasonable period rather than appearing the week before closing. This is a standard part of RV park loan prequalification and one lenders are strict about, because unseasoned funds are a common flag for undisclosed debt.

    How to get this ready: pull three consecutive months of statements for the account holding your down payment funds. If a large deposit shows up in that window, from a gift, a business distribution, or the sale of an asset, have paperwork ready to explain the source. An unexplained large deposit is one of the fastest ways to add weeks to your timeline.

    If You Own Other Businesses: Three More Items

    If you currently own any other business, your lender needs a complete picture of those entities too, because their financial health affects your personal financial position and your capacity to take on new debt. This is the part of RV park loan prequalification that catches experienced entrepreneurs off guard, since it can feel like the lender is auditing every business you touch instead of just the one you are trying to finance.

    7. Last Three Years of Tax Returns for Every Affiliate Business

    Any business you own, in whole or in part, needs its own three years of returns submitted alongside your personal returns. This is not optional, and skipping an entity because it feels irrelevant to the RV park deal is one of the fastest ways to get your file flagged for missing information partway through underwriting.

    How to get this ready: make a list of every entity you have ownership in, no matter how small the stake, before you are asked. Pull complete returns for each one, including all schedules. If one of your businesses had a rough year, be ready to explain why in plain terms.

    8. Debt Schedule for Each Business Entity

    A debt schedule lists every loan, line of credit, and financing obligation each of your businesses carries, current balance, monthly payment, and remaining term. Lenders use this to calculate your total debt exposure across every entity you control, not just the one applying for this loan.

    How to get this ready: build a simple table for each entity, lender name, original amount, current balance, monthly payment, interest rate, and maturity date. If you do not already keep this updated, this is worth building as a permanent document you maintain going forward, not just something you produce once for this loan. It comes up again at renewal and at every future financing conversation, RV park loan prequalification or otherwise.

    9. 2025 and 2026 Year-to-Date Profit and Loss Statements

    Your lender wants to see how each affiliate business is performing right now, not just what the historical tax returns show. A P&L that is trending up or down tells your lender something a two-year-old tax return cannot.

    How to get this ready: pull a clean, accrual-based P&L for both the full 2025 year (or the last year) and the current year-to-date period for every business entity. If your books are cash basis or messy, this is the moment that catches up with you, because a lender reviewing sloppy financials mid-underwriting is a lender who slows down or asks harder questions. If your bookkeeping is not in a state you would want a stranger reviewing right now, that is worth fixing before you start RV park loan prequalification, not during it.

    What This List Actually Tells You

    Look at this list as a whole and a pattern becomes obvious. RV park loan prequalification is not really about the RV park. It is about you, and about whether your financial life is documented, consistent, and easy to verify. The park itself gets underwritten separately, through the process I described in How to Evaluate an RV Park Deal. This list is the other half of the equation, the half that is about you as the borrower, and it is the half most buyers spend the least time preparing for.

    Buyers who treat RV park loan prequalification as a box to check the week before they need it almost always lose time, and sometimes lose the deal entirely while a more prepared buyer moves faster. Buyers who build this file in advance, before they are even looking at a specific park, walk into a seller conversation able to say they are ready to close, and mean it. That single difference in preparation is what separates a smooth RV park loan prequalification from one that drags on for months.

    If you want to understand how a specific lender structure like SBA financing actually works once your prequalification file is complete, read SBA Loan for RV Park: 7 Critical Things Every Buyer Must Know Before Applying. And if seller financing is part of your structure, RV Park Financing: 5 Hard Truths About Zero Down Deals and Seasonality is worth reading before you assume a lower down payment solves everything.

    Build This File Before You Need It

    Do not wait until you have a signed LOI to start pulling these documents together. Build this file now, while you are still searching, so that when the right park comes along you can move on it immediately. RV park loan prequalification done in advance is one of the most underrated competitive advantages a buyer can have in this market.

    If you want a second set of eyes on your RV park loan prequalification file before you submit it to a lender, or want help getting your affiliate business financials into shape for review, that is exactly the kind of work I do. Reach out at PVIFinancial.com. And if needed, I can also recommend a lender who is very familiar with RV park loans, which can save you a lot of time.

    If you have not picked up a copy yet, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ walks through the full acquisition process, including financing, in more depth. Grab it on Gumroad or search my name on Amazon.

    And check the RV Park Resource Library for the rest of the acquisition series if you want to keep building your knowledge before you make an offer.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • RV Park Due Diligence Cost: The $298,100 Difference Between a Generic Checklist and a Real One

    RV Park Due Diligence Cost: The $298,100 Difference Between a Generic Checklist and a Real One

    Every RV park due diligence checklist online tells you the same thing. Check the septic system. Review the leases. Look at the insurance. Pull the utility bills. Get an environmental report.

    What none of them tell you is what happens in your bank account when you skip one of those steps. A checklist item without a dollar amount attached to it is just a suggestion. You can talk yourself out of a suggestion when you are three weeks into a deal and excited about closing. It is a lot harder to talk yourself out of a $58,000 line item. That is the real RV park due diligence cost, not just a list of things to inspect.

    So instead of another generic list, here is the RV park due diligence cost breakdown. Same checklist items you have seen everywhere else, but with the actual dollar consequence attached to each one, using an example park I will call Blue Heron RV Park, 54 sites, to walk through the math.

    Why Generic Checklists Don’t Actually Protect You

    I have looked at the checklists on the bigger RV park sites and the pattern is always the same. “Inspect the septic system.” “Review the leases.” “Check the insurance coverage.” True statements, all of them. But a buyer reading that list has no idea whether skipping any one item costs them $2,000 or $200,000. Without that number, every item on the list feels optional, and that is exactly why RV park due diligence cost needs to be spelled out, not implied. My checklist here has the numbers next to every item, because the number is the whole point.

    If you want the fuller 10-item version of this checklist first, I already wrote the RV Park Due Diligence Checklist. This post picks up where it leaves off and answers the question that one didn’t: what does each miss actually cost you.

    Item 1: Septic and Wastewater System Age

    Generic checklist: “Inspect the septic system.”

    RV park due diligence cost: A 54-site park on a shared septic system that is past its 20-year design life is not a maintenance item, it is a replacement project. At Blue Heron, a licensed inspector found the drain field failing on two of three leach fields. Replacement cost for a system this size runs $50,000 to $65,000. I used $58,000 as the number that lands in year one if the buyer does not catch this before closing.

    Item 2: Electrical Panels and Site Pedestals

    Generic checklist: “Check the electrical infrastructure.”

    RV park due diligence cost: Blue Heron’s pedestals were original to a 1998 build, rated at 30 amp when most RVs on the road now need 50 amp service to run air conditioning and appliances at the same time. Upgrading 54 pedestals plus the panel that feeds them runs $22,000. Skip this and you are turning away the exact guests who pay the highest nightly rates.

    Item 3: Road Base and Paving Condition

    Generic checklist: “Walk the property and note deferred maintenance.”

    RV park due diligence cost: Cracked, unmaintained roads are easy to miss on a broker tour scheduled on a sunny afternoon. At Blue Heron, the internal roads had not been resurfaced in over a decade, and with 54 sites the road network covers real ground, not a driveway. A geotechnical estimate for base repair and resurfacing across the full internal road system came in at $84,000. That is a number the seller’s P&L will never show you, because deferred maintenance does not show up as an expense until you are the one paying for it.

    Item 4: Long-Term Tenant Lease Terms

    Generic checklist: “Review all leases.”

    RV park due diligence cost: Eleven long-term tenants at Blue Heron were locked into month-to-month agreements with no rate escalation clause, some unchanged in four years while market rates in the area climbed 18 percent. That gap works out to $11,400 a year in revenue the park is leaving on the table before you even factor in the cost of renegotiating those terms after closing. If you want to understand why the seller’s numbers and your numbers are never the same thing, that is the whole idea behind why the seller’s pro forma is not your pro forma.

    Item 5: Insurance Coverage and Flood Zone Status

    Generic checklist: “Confirm adequate insurance coverage.”

    RV park due diligence cost: An independent insurance quote at Blue Heron came in $8,200 a year higher than the seller’s current policy, once flood zone designation and full replacement cost coverage were factored in properly. Sellers frequently carry legacy policies that have not been updated to reflect current replacement costs or flood maps. That gap does not show up until you are the one signing the renewal.

    Item 6: Environmental and Wetland Designation

    Generic checklist: “Order an environmental report.”

    RV park due diligence cost: A Phase 1 environmental assessment for Blue Heron ran $15,000, and it is not an optional line item you can skip to save money. Wetland encroachment or a prior gas station on an adjacent parcel can turn into a mitigation cost or an insurance and financing problem that follows the property for years. The SBA’s own guidance on buying an existing business points to this same principle: due diligence has to cover the physical condition and the paperwork, not just the profit and loss statement, before you commit capital.

    Item 7: Owner Labor Not Reflected in the P&L

    Generic checklist: “Verify the management structure.”

    RV park due diligence cost: This is the one that shows up in almost every deal I underwrite. The seller at Blue Heron worked the front desk, coordinated all maintenance, and handled bookkeeping personally for eleven years, and none of that labor appears as an expense anywhere in the financials. Replacing that labor with hired staff at market rate costs $72,000 a year. I wrote an entire post on this exact pattern, The $312,000 Mistake, because it is the single biggest gap between what a park looks like it earns and what it actually earns once you have to pay someone to run it.

    Item 8: Deferred Amenity Maintenance

    Generic checklist: “Inspect common area amenities.”

    RV park due diligence cost: The pool liner, bathhouse fixtures, and laundry equipment at Blue Heron were all original to the property and past their useful life. Bringing those amenities current runs $27,500. Amenities are the first thing to get deferred by an owner trying to protect their bottom line in the final years before a sale, which is exactly why they need a hard look, not a walkthrough glance.

    What the Real RV Park Due Diligence Cost Looks Like

    Here is the RV park due diligence cost, item by item, added up:

    ItemCost
    Septic system replacement$58,000
    Electrical panel and pedestal upgrade$22,000
    Road base and resurfacing$84,000
    Long-term lease revenue gap (annual)$11,400
    Insurance coverage gap (annual)$8,200
    Environmental assessment$15,000
    Owner labor not in P&L (annual)$72,000
    Deferred amenity maintenance$27,500
    Total year-one impact$298,100

    That is the difference between a checklist that tells you to look at something and a checklist that tells you what happens if you don’t. None of these numbers show up on the seller’s P&L. All of them show up in your bank account in year one if you do not catch them first.

    If you want to see how these same gaps affect the actual valuation and cap rate on a deal once you rebuild the NOI properly, that is exactly what I walked through in The $312,000 Mistake. And if you want the full system for how I evaluate a park before I ever get to this level of detail, start with how to evaluate an RV park deal.

    Do This Before You Make an Offer

    Every item on this list has a dollar figure attached to it, because RV park due diligence cost only protects you when it is specific enough to negotiate with. A buyer who walks into a seller call with “your septic system needs replacing” has a weaker negotiating position than a buyer who walks in with “your septic system needs a $58,000 replacement, and here is the inspector’s report.”

    If you are underwriting a park right now, run your own numbers through the free NOI calculator at PVIFinancial.com before you make an offer. And if you want a second set of eyes on a specific deal, acquisition underwriting starts at just $99 for a deal screen, and a full underwrite is priced depending on complexity.

    If you have not picked up a copy yet, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ covers the full due diligence and underwriting framework this RV park due diligence cost breakdown is built on. Grab it on Gumroad or search the title on Amazon.

    And check the RV Park Resource Library for the rest of the due diligence series if you want to go deeper before you close.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • Fractional CFO for Your RV Park: 5 Critical Things Generic Guides Miss

    Fractional CFO for Your RV Park: 5 Critical Things Generic Guides Miss

    Search for anything on fractional CFO services and you will land on the same handful of articles, over and over. Pricing guides, cost breakdowns, KPI dashboard checklists, all written with a very specific business in mind, usually a venture backed startup or a growing eCommerce brand. A fractional CFO for your RV park needs almost none of what those articles focus on, and almost all of what they leave out entirely.

    Here is the mismatch. Generic fractional CFO content assumes a business with fairly even monthly revenue, a straightforward cap table, and financial questions centered on burn rate or ad spend efficiency. An RV park is a seasonal, real estate anchored, debt heavy operating business, and having a fractional CFO for your RV park means working completely differently than that generic advice ever anticipated.

    Why Generic Fractional CFO Advice Does Not Fit RV Park Owners

    Almost every pricing guide and service breakdown I have come across treats “fractional CFO” as a single, interchangeable service regardless of industry. Monthly retainer, KPI dashboard, budget versus actual, strategy calls. Those pieces genuinely matter, and I built my own service tiers around a similar structure. But real seasonality, real debt structure, and real acquisition underwriting sit on top of that basic framework, and almost nothing written for a general small business audience covers that layer at all.

    Take seasonality. Most fractional CFO content treats cash flow forecasting as a fairly even monthly exercise with the occasional slow quarter. An RV park can see months where revenue swings dramatically from one season to the next, and that swing has to get modeled against fixed debt service and payroll obligations that do not shrink just because occupancy does. I covered why this specific gap trips up new owners in my post on why a full park does not always mean healthy cash flow, and that same seasonal mismatch is exactly what having a fractional CFO for your RV park is meant to catch, something a generic SaaS dashboard would never surface.

    There is also the acquisition side. General fractional CFO guides are written for businesses that are already operating and simply want ongoing financial management. Having a fractional CFO for your RV park often means bringing that person in before the business is even purchased, rebuilding a seller’s NOI, stress testing debt service, and helping a buyer decide whether a specific deal is actually worth the risk. That is a completely different skill set than monthly bookkeeping oversight, and it is almost never mentioned in the generic pricing breakdowns that dominate search results on this topic.

    Why Monthly Eyes on Your Numbers Protect Your Investment

    Here is the part that almost nobody talks about, including me until now. Most owners do not think about their financials until something is already wrong. A slow season runs longer than expected, a reserve dips lower than planned, an expense creeps up unnoticed for months, and by the time it shows up as a real problem, it is already expensive to fix. Nobody calls a CFO when things are going fine. They call one after the surprise.

    Having a fractional CFO for your RV park can remedy this. It is not really about a monthly report showing up in your inbox. It is about someone with a trained eye actually looking at your numbers every single month, catching the small drift before it becomes a real problem, and telling you the truth about what is happening in your business while there is still time to do something about it. That kind of ongoing oversight protects the investment you have made in the property itself, not just your monthly cash position.

    There is a real cost argument here too. Fixing a financial problem that has been building quietly for six months almost always costs more than catching it in month one would have. This is exactly how a good fractional CFO for your RV park pays for themselves. Having a fractional CFO for your RV park turns the expensive surprises into rare events instead of routine ones.

    And if you have investors or a lending partner involved in the deal, this matters even more. Investors do not just want a return, they want confidence that someone is actually watching the numbers on their behalf, month after month, not just at tax time or when a problem finally surfaces. Having a fractional CFO for your RV park gives investors exactly that kind of confidence, and clean, current financials paired with a consistent monthly review are a huge part of what keeps that relationship healthy over the life of the deal.

    What a Fractional CFO for Your RV Park Actually Needs to Do

    Having a fractional CFO for your RV park should mean layering seasonality, debt structure, and acquisition underwriting on top of the basic monthly reporting work, not treating those as optional extras.

    Model seasonality against fixed obligations, not average monthly cash flow. A generic CFO dashboard smooths revenue into a monthly average. When you have a fractional CFO for your RV park, they will show you exactly how a slow shoulder season interacts with a fixed mortgage payment, seasonal payroll, and a reserve fund that has to survive the gap.

    Understand blended debt structures, not just a single loan. Many RV park deals combine seller carry with a bank loan, each with different rates, terms, and balloon schedules. When you have a fractional CFO for your RV park, both pieces get tracked separately, something a generic small business CFO template rarely accounts for.

    Support acquisition underwriting, not just ongoing bookkeeping oversight. Generic fractional CFO services usually start after a business is already running. Having a good fractional CFO for your RV park is often just as valuable before you buy, rebuilding the seller’s numbers and stress testing the deal before you sign anything.

    Speak the language of private lenders and seller carry, not just bank underwriting. A lot of RV park financing runs through seller notes and private capital rather than a conventional bank loan alone. Having a fractional CFO for your RV park who actually speaks that language comes from experience underwriting and originating private loans, not from a generic CFO certification.

    Connect the books to the guest experience, not just the spreadsheet. Financial oversight has to account for how staffing, pricing, and rule enforcement decisions actually show up in the numbers. Having a fractional CFO for your RV park means someone who treats the business as a real operation, not a faceless set of accounts.

    How to Find a Fractional CFO for Your RV Park That Actually Fits

    Finding the right person for this comes down to asking a few specific questions most people never think to ask.

    Ask what industries they have actually worked in, not just what services they offer. A generic fractional CFO can build you a KPI dashboard. Having a fractional CFO for your RV park who already understands seasonality, occupancy metrics, and debt structures specific to outdoor hospitality matters more than a polished service menu.

    Ask whether they can help before you buy, not just after. If you are still shopping for a park, having a fractional CFO for your RV park who can rebuild NOI and stress test a deal before closing is worth more than one who only picks up work once you already own the property. My post on what actually separates a good RV park deal from one that sinks you covers this exact underwriting layer in more detail.

    Ask how they think about reserves for a seasonal business specifically. A three to six month reserve rule pulled from a generic small business template does not automatically fit a business with sharp seasonal swings. I go deeper on this specific gap in my post on RV park reserve fund mistakes.

    Ask whether bookkeeping and CFO strategy are connected or separate. If your books are inconsistent, no amount of CFO level strategy sits on a solid foundation. Having a fractional CFO work closely with whoever handles your books month to month, or handle both together (which I do), is exactly the gap I wrote about in what good bookkeeping actually looks like.

    Ask for a straight answer on cost relative to the complexity of your business. SCORE’s financial management guidance for small businesses is a reasonable outside reference point for what small business financial oversight should cover in principle, even though it is not written with RV parks specifically in mind.

    Having a fractional CFO for your RV park is not the same as hiring a generic small business CFO who happens to also take on a campground client. It is a specific combination of seasonality modeling, blended debt structure knowledge, acquisition underwriting experience, and private lending perspective, paired with a monthly set of eyes that catches problems while they are still small and cheap to fix. That is what having a fractional CFO for your RV park should actually deliver, not just a KPI dashboard with your logo on it.

    If you want a fractional CFO who already understands seasonality, debt structure, and acquisition underwriting specific to RV parks, and who will actually be looking at your numbers every month instead of just at tax time, that is exactly the work I do. Reach out at PVIFinancial.com.

    For more on running a profitable, well managed park, check out my Resource Library, and grab a copy of my book From Offer to Operation: The Complete RV Park Investor’s Guide, also available on Amazon.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • RV Park Deal Worth Buying: 5 Critical Truths Cap Rate Alone Won’t Tell You

    RV Park Deal Worth Buying: 5 Critical Truths Cap Rate Alone Won’t Tell You

    Ask most acquisition content what makes an RV park deal worth buying, and you will get the same answer over and over. Look at the cap rate. Some of the more well known voices in this space go as far as saying RV parks are bought and sold on one attribute alone, current income, full stop. That is a simple story, and simple stories sell well, but it leaves out almost everything that actually determines whether a specific deal is right for a specific buyer.

    Here is the problem with stopping at cap rate. Two parks can carry the identical cap rate and be completely different investments once you look at how each one is financed, how each seller structured their terms, and how much cushion each buyer actually has if a season goes sideways. An RV park deal worth buying on paper for one buyer can be a genuine mistake for another buyer looking at the exact same number.

    Why Cap Rate Alone Does Not Tell You If a Deal Is Worth Buying

    Most of the well known voices in this industry treat the deal evaluation question as a pure income exercise. Find the NOI, apply a cap rate, compare it to what similar parks have sold for, and you have your answer. I actually walked through a full six step version of this kind of evaluation in my post on how to evaluate an RV park deal, and the income side absolutely matters. But an RV park deal worth buying is never just about the income number in isolation.

    The piece almost nobody talks about is what happens to that same cap rate once you layer in the actual debt structure behind the deal. A park priced at an 8 percent cap rate financed with 50 percent seller carry at a low fixed rate behaves completely differently than the same park financed entirely through a variable rate SBA loan. The income number stays the same. The risk profile does not. This is exactly the gap I dug into in my post on how to analyze a seller carry deal, because the terms behind the number change everything about whether that number is actually safe.

    There is also a persistent habit in RV park content of treating the seller’s NOI as gospel. I have written before about the mistake of accepting a seller’s NOI without rebuilding it yourself, and that mistake alone can make an otherwise reasonable cap rate look far better than the deal actually is. An RV park deal worth buying starts with a number you trust, not a number the seller handed you.

    What Actually Separates a Good Deal From a Deal That Sinks You

    It has debt service your rebuilt NOI can actually cover with room to spare. Lenders look at debt service coverage ratio for exactly this reason, and it is worth borrowing that discipline even if you are financing part of the deal with seller carry. A healthy debt service coverage ratio gives you a buffer, not just a break even number, and that buffer is a huge part of what makes an RV park deal worth buying instead of one that barely survives a normal season.

    It has terms that match your actual risk tolerance, not just a low headline rate. A low interest rate on a seller note does not matter much if the balloon comes due in three years and you have no clear plan to refinance by then. The terms behind the number matter just as much as the number itself when you are deciding whether this is an RV park deal worth buying.

    It has a reserve plan built in before you sign, not figured out after closing. I covered the specific mistakes that show up here in my post on RV park reserve fund mistakes, and this is one of the clearest places where a technically good cap rate deal turns into a genuine problem, because the buyer never planned for a slow season on top of debt service. No deal is an RV park deal worth buying if the reserve plan only exists on paper.

    It has a seller’s numbers you have personally rebuilt, not just accepted. The real NOI, once you strip out one time addbacks, owner perks, and optimistic assumptions, is the number that actually determines whether the deal works. An RV park deal worth buying is built on a number you can defend to a lender, not a number that looked good in a broker package. That single distinction is often what separates an RV park deal worth buying from one that quietly falls apart six months in.

    It fits your specific financial position, not a generic buyer profile. A deal that makes sense for a buyer with six months of reserves and low personal overhead can be a stretch for a buyer without that cushion, even at the exact same price and cap rate. What makes it an RV park deal worth buying depends on who is buying it, not just what the numbers say in isolation.

    How to Actually Test Whether a Deal Is Worth Buying

    Rebuild the NOI yourself before you compare cap rates. Do not use the seller’s number as your starting point. Strip out addbacks and one time items and build your own trailing twelve months from the real bank statements. This step alone is often what separates an RV park deal worth buying from one that only looks good on the surface.

    Model your actual debt service, piece by piece. If seller carry is part of the structure, map out the rate, the amortization, and any balloon separately from a bank loan, rather than treating debt as one flat number. An RV park deal worth buying holds up under this level of detail, not just at the headline rate.

    Run a downside scenario before you get emotionally attached. Take your rebuilt numbers and test what happens if occupancy comes in 15 to 20 percent below your forecast during your slowest months, and check whether debt service and reserves both survive that scenario. A deal that only pencils out in the best case is not an RV park deal worth buying, it is a bet on nothing going wrong.

    Compare the deal to your own risk tolerance, not a generic buyer profile. The number that tells you if you are overpaying is not universal. It depends on your own reserves, your other obligations, and how much room you actually have if the deal goes sideways.

    Get a second set of eyes on the underwriting before you commit. A deal that looks solid on a broker’s one page summary can look very different once someone rebuilds the numbers independently, and that gap is often the whole difference between an RV park deal worth buying and one you will regret. This is exactly the kind of review my work as a fractional CFO is built around, catching the gap between what a deal looks like on paper and what it actually means for your specific financial position.

    An RV park deal worth buying is not defined by a single cap rate number floating in isolation. It is defined by rebuilt numbers you trust, debt structured in a way that leaves you room to breathe, and a downside scenario you have already tested before you sign anything. The Debt Service Coverage Ratio overview from Chase is a solid outside primer if you want a general framework for how lenders think about this before you layer in the RV park specific numbers.

    If you are working through a deal right now and want a second set of eyes on whether it actually holds up once the real numbers are rebuilt, that is exactly the kind of work I do. Reach out at PVIFinancial.com.

    For more on running a profitable, well managed park, check out my Resource Library, and grab a copy of my book From Offer to Operation: The Complete RV Park Investor’s Guide, also available on Amazon.

    ~Wendi | Fractional CFO | PVIFinancial.com

    Want to be notified when Claude responds?

  • 5 Critical Reasons RV Park Bookkeeping Is More Than Tax Prep

    5 Critical Reasons RV Park Bookkeeping Is More Than Tax Prep

    Almost every article on RV park bookkeeping I have come across says some version of the same thing. Get on QuickBooks. Segment your revenue by site type. Do not miss your deductions. Hand it all to a CPA who understands campgrounds. That advice is fine as far as it goes, but it all points toward the same finish line, getting your tax return filed correctly. Nobody is talking about what your books are supposed to do for you the other eleven months of the year.

    Here is the problem with that framing. RV park bookkeeping done well is not a once a year exercise that exists to keep the IRS happy. It is the foundation every other financial decision in your business rests on, your pricing, your staffing, your reserve planning, and eventually your resale value. When your RV park bookkeeping only gets discussed as a tax prep chore, it is easy to start treating your monthly numbers as a formality instead of the tool they actually are.

    Why Most RV Park Bookkeeping Content Stops Short

    I read through a stack of accounting firm blogs recently, and the pattern was consistent. Get on the right software. Segment revenue correctly. Track expenses carefully. Do not miss depreciation on new amenities. All of that is genuinely useful, and I am not knocking accurate bookkeeping. But almost none of it connected RV park bookkeeping to the decisions an owner actually makes throughout the year.

    RV park bookkeeping that only exists for tax purposes tends to get updated in batches, sometimes monthly, sometimes quarterly, sometimes only right before the CPA needs it. If you are three months behind on reconciliation, you are making pricing and staffing decisions off of memory and gut feel instead of actual numbers. That gap is exactly where a lot of preventable mistakes happen, not from bad intentions, just from treating your financials as a compliance task rather than an operating tool.

    There is also a financing angle almost nobody in this space writes about. Lenders and buyers do not just want your books accurate at tax time. They want a clean, current, defensible set of financials whenever a refinance opportunity comes up or whenever you decide to sell. If your RV park bookkeeping is only cleaned up once a year, you end up scrambling every time an opportunity shows up on a timeline you did not control.

    What RV Park Bookkeeping Actually Needs to Do for You

    It should give you a reliable read on cash position at any point in the year. Tax prep only cares about your annual totals. Good RV park bookkeeping means knowing your cash position this month, not just in April, so you can make staffing and spending decisions with real information instead of guesswork.

    It should support pricing decisions, not just report on them after the fact. If your RV park bookkeeping is segmented properly by site type and revenue stream, you can see which parts of your business are actually driving profit and which are dragging on it. That level of detail is what lets you adjust pricing with confidence instead of guessing.

    It should make refinancing or resale a non-event, not a scramble. Buyers and lenders both want a clean T-12 and consistent monthly financials. RV park bookkeeping that has been maintained consistently all year means you can respond to an opportunity in days instead of spending weeks reconstructing a year of transactions.

    It should catch problems while they are still small. A misclassified expense or an accidental revenue drop is much easier to fix in the month it happens than after twelve months have piled up. Financials that are current month to month act like an early warning system, not just a historical record.

    It should connect back to your original underwriting. The DSCR and cash flow assumptions you modeled when you bought or financed the park should be numbers you can actually check your real performance against. RV park bookkeeping that is only built for tax season rarely gets structured in a way that makes this comparison easy.

    How to Build RV Park Bookkeeping That Does More Than File Your Return

    Get your books current every month, not just before tax season. If you are more than 30 days behind on reconciliation, you are making decisions blind. Monthly closes are the foundation of RV park bookkeeping that actually helps you run the business.

    Segment revenue by site type and income stream. Site fees, long term stays, retail, and ancillary income all behave differently and deserve their own categories. This is one of the more common gaps I see in RV park bookkeeping that has only ever been set up for tax filing rather than decision making. If pricing is where you feel the most uncertainty right now, my posts under Revenue and Pricing go deeper into using that segmented data well.

    Build a monthly reporting habit, not just an annual one. A simple monthly package, income statement, cash position, and a few key metrics, turns your RV park bookkeeping into something you actually use. I covered why this kind of regular review matters just as much for cash reserves in my post on RV park cash flow planning.

    Keep your books ready for a lender or buyer at any time. You never know exactly when a refinance opportunity or a serious buyer will show up. Staying current all year means your RV park bookkeeping is never caught reconstructing a year of transactions under a deadline.

    Bring in help for the parts that are not your strength. Some owners are excellent operators who struggle with the financial side, and that is completely normal. If your RV park bookkeeping needs a fractional CFO layer on top of clean books, that is exactly what my Fractional CFO Services are built around. And if enforcement and day to day operations feel just as loose as your books, my post on RV park rule enforcement covers that side of the business in detail.

    RV park bookkeeping is not something you do so your CPA has an easier April. It is the information system your entire business runs on, from pricing to staffing to reserves to eventually walking into a sale with confidence instead of a scramble. The SBA’s general guidance on managing your finances is a reasonable starting point if you want an outside framework, available at sba.gov, but it is written for small businesses broadly. Layering the RV park specific structure on top, segmented revenue, monthly closes, and a direct line back to your underwriting, is where good RV park bookkeeping actually starts paying for itself.

    If your books are more of a once a year scramble than a monthly habit, that is exactly the kind of system I help owners build. Reach out at PVIFinancial.com.

    For more on running a profitable, well managed park, check out my Resource Library, and grab a copy of my book From Offer to Operation: The Complete RV Park Investor’s Guide, also available on Amazon.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • 5 Critical Gaps in Most RV Park Cash Flow Planning Advice

    5 Critical Gaps in Most RV Park Cash Flow Planning Advice

    RV park cash flow planning shows up in almost every buyer guide and financing blog in this industry, and it almost always says the same three things. Forecast your revenue by month. Set aside savings during peak season. Consider a line of credit for the gaps. That advice is not wrong. It is just incomplete, and incomplete cash flow advice is exactly what leaves new owners exposed the first time a slow season runs longer than expected.

    I read through a stack of these articles recently, from accounting firms, financing companies, and general outdoor hospitality blogs. Every single one told readers to build a reserve fund. Almost none of them told readers how much reserve is actually enough, or walked through what happens to that reserve once real debt service, real payroll, and a real bad season hit it at the same time. That gap is the whole reason RV park cash flow planning needs more than a checklist of good habits.

    Why Generic RV Park Cash Flow Planning Advice Falls Short

    Most of what passes for RV park cash flow planning online is small business advice with an RV park label attached to it. Forecast your revenue. Track your expenses. Keep three to six months of operating costs in reserve. That is sound general guidance, but it treats every seasonal business the same way, whether you are running a snow cone stand or a 150 site RV resort carrying a seven figure acquisition loan.

    The problem is that RV park cash flow planning done right has to account for your specific debt structure, your specific seasonality curve, and your specific capital needs, not a generic three to six month rule pulled from a small business workshop. A park with 50 percent seller financing at a fixed rate behaves completely differently under stress than a park financed with a variable rate SBA loan. A destination park with a long, predictable peak season behaves differently than a park that depends on a handful of local events to fill gaps. None of that shows up in the generic version of the advice.

    There is also a habit in this industry of treating RV park cash flow planning as something you do once, usually right after closing, and then set aside. Build the forecast, set up the reserve, move on. Real cash flow planning is not a one time exercise. It is a living model you revisit every quarter, because your occupancy trends shift, your debt service stays fixed, and your reserve either grows or shrinks depending on how disciplined you actually are between now and next season.

    What Most RV Park Cash Flow Planning Content Leaves Out

    It rarely stress tests the reserve against your actual debt service. Plenty of advice tells you to build a reserve fund. Almost none of it asks whether that reserve would survive a season where occupancy comes in 15 or 20 percent below your forecast while your mortgage, seller note, and payroll obligations stay exactly the same. RV park cash flow planning that skips this step gives you a reserve number that feels safe on paper and might not be safe at all.

    It rarely accounts for seller financing or blended debt structures. A lot of RV park deals include seller carry alongside a bank loan, sometimes with different rates, different amortization schedules, and different balloon terms. Generic cash flow advice treats debt service as one flat number. Real RV park cash flow planning has to model each piece separately, because a seller note coming due at the wrong time can undo months of careful reserve building.

    It rarely separates operating reserves from capital reserves. Most advice lumps all savings into one bucket labeled “reserve fund.” In practice, the cash you need to cover a slow month is a different pool than the cash you need for a new roof on the bathhouse or a septic repair. Blending the two is one of the fastest ways to think you are covered when you are not.

    It rarely models a downside scenario with real numbers. General cash flow guidance likes to mention planning for a slow season in the abstract. RV park cash flow planning that actually protects you means running an occupancy downside of 15 to 20 percent through your specific revenue and expense numbers and checking whether you can still make debt service and payroll without touching your capital reserve.

    It rarely connects cash flow planning back to your original underwriting. The DSCR and cash on cash return you modeled before you bought the park should not be a one time exercise you never look at again. Real RV park cash flow planning revisits those same numbers regularly and asks whether your actual performance still supports the assumptions you underwrote at purchase.

    How to Build RV Park Cash Flow Planning That Actually Holds Up

    Separate your reserves into two buckets. Keep an operating reserve sized to cover a genuinely bad season, and a separate capital reserve sized to cover deferred maintenance and unexpected capital repairs. If you are still working through your acquisition, my posts under Acquiring an RV Park walk through how to size capital reserves during due diligence, before you are relying on guesswork after closing.

    Run a real downside scenario, not a vague one. Take your actual monthly revenue and expense numbers and model a 15 to 20 percent occupancy shortfall through the slowest months of your season. If your reserve and your debt service do not both survive that scenario on paper, RV park cash flow planning has more work to do before you feel comfortable.

    Model your debt service piece by piece, not as one number. If you are carrying seller financing alongside a conventional loan, map out exactly when each payment is due, at what rate, and when any balloon comes due. I covered a version of this kind of blended debt modeling in my post on RV park rule enforcement, where the same discipline of not treating everything as one flat category matters just as much for staffing decisions as it does here for debt.

    Revisit your numbers quarterly, not once a year. RV park cash flow planning is a living process. If your occupancy trend is drifting from what you modeled at acquisition, that is information you want three months into a slow trend, not nine months in when the reserve is already thin. My Fractional CFO Services work with clients on exactly this kind of ongoing quarterly review.

    Get your bookkeeping clean enough to trust the numbers you are modeling. None of this works if your monthly financials are inconsistent or delayed. If your books are not giving you a reliable, current picture, my Bookkeeping and Financial Systems posts cover how to get that foundation solid first.

    Pressure test your pricing before you lean on debt to fill the gap. Sometimes the fastest way to strengthen a cash flow position is smarter seasonal pricing rather than a bigger reserve. My Revenue and Pricing posts go deeper into adjusting rates without hurting your guest experience or your occupancy.

    RV park cash flow planning is not a box you check with a generic reserve fund and a monthly forecast spreadsheet. It is a specific, ongoing discipline built around your actual debt structure, your actual seasonality, and your actual downside risk. The advice that stops at “build a reserve fund” leaves out the exact math that tells you whether your reserve would actually survive the season that tests it.

    If you want your RV park cash flow planning built around your real numbers instead of a generic small business rule of thumb, that is exactly the kind of modeling I do with clients. The SBA’s own guidance on managing your finances is a useful general starting point if you want an outside framework, found at sba.gov, but it is written for small businesses broadly, not RV parks specifically, so layering the seasonal and debt structure detail on top is where the real protection comes from.

    If you want help stress testing your reserve, modeling your debt service, or building a cash flow plan that actually holds up in a bad season, that is exactly the kind of work I do. Reach out at PVIFinancial.com.

    For more on running a profitable, well managed park, check out my Resource Library, and grab a copy of my book From Offer to Operation: The Complete RV Park Investor’s Guide, also available on Amazon.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • RV Park Investing: 3 Deals on My Desk Proving This Is Not the Passive Income Play You Think It Is

    RV Park Investing: 3 Deals on My Desk Proving This Is Not the Passive Income Play You Think It Is

    Right now I have 5 RV park deals on my desk, and every single one is teaching me something about RV park investing.

    A three park portfolio in Florida, one motorcoach resort and two long term parks. A waterfront destination park in Oklahoma. And a river property in North Carolina with an equestrian vibe, acres of trails, and a guest experience that is genuinely hard to put a cap rate on.

    All three are in active underwriting at different stages. All three have shown me something different this month. And all three have reminded me why RV park investing is one of the best opportunities in commercial real estate right now, and also one of the most misunderstood asset classes I have worked in.

    Here is what I want to say before we go any further. RV park investing is not passive income. I know that is not what you read on most investing blogs, and I know the pitch sounds great: land, cash flow, outdoor recreation tailwinds, and a fragmented market full of mom and pop operators who have not raised rates in ten years. All of that is true. But so is this: RV parks are businesses, not mailbox money, and the investors who treat them like mailbox money are the ones who call me six months after closing wondering why the numbers do not look like the offering memorandum.

    I just talked to a seller who took over a park using creative financing with no payments due for twelve months. The plan was to come in, make updates, add amenities, and get the park running the way they envisioned it. Six months in, they have barely made a dent in the construction list, and they have not done a single thing on the marketing side. Their reasoning? They do not want guests to be disappointed by the noise and the unfinished state of the property.

    I understand the instinct, but here is the reality: they now have six months left before payments kick in, no revenue coming in to cover what is coming, and no pipeline of guests being built. That is not a renovation strategy. That is a countdown clock. RV park investing rewards owners who treat it like the business it is from day one, not from the day they feel ready.

    I built my last company working fourteen hour days. I am not scared of hard work and I love the entrepreneur life. But I want you to go into RV park investing with eyes wide open, because the upside is very real, and so is the work required to capture it.

    Now let me tell you what my desk looks like this week.

    RV park investing is not one asset class, it is actually several

    One of the biggest mistakes I see buyers make in RV park investing is assuming all parks underwrite the same way. They do not, and the three deals I am working right now make that point better than anything I could say in theory.

    The Florida portfolio is the clearest example. One motorcoach resort and two long term parks, all under the same ownership, all in the same general market, and all three are completely different animals financially. The motorcoach resort runs premium nightly rates, attracts a higher income traveler, and lives and dies by its amenity stack and online reputation. The two long term parks run on monthly site rent, have lower per site revenue, and operate more like a mobile home park than a traditional campground. Same seller. Same state. Completely different underwriting. This is one of the most important things to understand about RV park investing before you ever make an offer.

    The Oklahoma waterfront park is a destination play. Location is doing a lot of the heavy lifting there, and the questions I am asking are about durability, what holds this park together when the peak season ends and what the off season expense structure actually looks like. Every destination park in RV park investing has a version of this question hiding underneath the surface numbers.

    The North Carolina river property is something else entirely. Equestrian trail access, acreage, a lifestyle amenity that you genuinely cannot replicate. The question there is not whether guests love it, they do, it is whether the financial infrastructure exists to support what it is trying to be. That is a different kind of red flag in RV park investing, not fraud, not deception, just a gap between the experience the park delivers and the systems behind it.

    Each of these deals requires a completely different underwriting lens. If you want to go deeper on how to think through deal types before you make an offer, my RV Park Resource Library has a growing list of posts on acquisition analysis, due diligence, and financial modeling, and it grows daily.

    Gross income is not the whole story in RV park investing

    One of the Florida sellers sent me her financials early in the process. Software reports, a T-12, and P&Ls. Clean presentation. Organized. On the surface it looked like exactly what I needed.

    I asked for the occupancy reports from her reservation software.

    She said she already gave me all the income.

    I explained that I did not need the income number. I needed to know how it was earned.

    It took a full week to get those reports. A week of back and forth, explaining that gross income alone does not tell me whether revenue came from 80% occupancy at market rates, or 40% occupancy at premium rates, or a handful of long term tenants subsidizing a park that transient guests are not actually choosing. Those are three completely different businesses with three completely different risk profiles, and they can all produce the same gross income number on a P&L.

    This is not a knock on the seller. She was not hiding anything. She genuinely did not understand why the number was not enough. But that gap, between what income looks like on paper and how it was actually earned, is where deals get mispriced in RV park investing, and where buyers who skip this step get hurt.

    If you want to see what happens when a buyer accepts income at face value without rebuilding the revenue picture, I wrote about exactly that in The $312,000 Mistake. It happens more than you think.

    Revenue mix is the most underrated number in RV park investing

    Once you have the occupancy data, the next question in RV park investing is what is driving the revenue and whether that revenue is durable.

    A park with 70% long term tenants looks stable on paper. Monthly site rent, predictable cash flow, low turnover. But long term tenants also cap your upside, limit your ability to raise rates quickly, and in some cases represent a cultural dynamic that is genuinely hard to change after closing. Buyers who underwrite long term parks at transient rates are making a serious error in RV park investing, and I see it more often than I should.

    A park that is 80% transient looks exciting on paper. Nightly rates, strong average daily rate, flexible pricing. But transient revenue is seasonal, weather dependent, OTA dependent in some cases, and requires active management of reservations, marketing, and guest experience. That is not passive. That is hospitality.

    Understanding your revenue mix before you close is not optional in RV park investing. It is the difference between buying what you think you are buying and buying something that only looks like it on the surface. For more on how to pressure test the revenue picture before you make an offer, Buying a Mom and Pop RV Park: 7 Hidden Risks That Destroy First Year Cash Flow is worth reading next.

    Seasonality is a cash flow problem, not just a calendar problem

    Every buyer in RV park investing knows parks can be seasonal. What fewer buyers model correctly is what seasonality actually does to cash flow over a twelve month period, and that gap is where first year owners get into real trouble.

    Here is a simplified version of what I look at. Say a park generates $1,200,000 in annual revenue. Sounds solid. But if 70% of that revenue ($840,000) comes in five months and the other 30% ($360,000) comes in seven months, the cash flow picture looks completely different from the annual number. Fixed costs like debt service, insurance, property taxes, and minimum staffing do not take the winter off. They run all twelve months.

    A park with $1,200,000 in annual revenue and $780,000 in annual fixed costs including debt service looks fine on an annual DSCR. But if $65,000 of those fixed costs hit in January and revenue that month is only $28,000, you have a liquidity problem, not a profitability problem. Those are different issues with different solutions, and most buyers I work with in RV park investing never model the monthly cash flow picture before closing.

    The North Carolina equestrian property I am looking at right now has this exact dynamic. Beautiful park, loyal guests, strong reviews. The monthly cash flow model is where the real conversation starts. For more on how to run this kind of stress test, How to Calculate Break-Even for Your RV Park walks through the math step by step.

    RV park investing is a great opportunity if you treat it like a business

    I said it at the top and I will say it again. RV park investing is one of the best opportunities in the market right now. The fundamentals are genuinely strong: fragmented ownership, under-managed assets, a growing base of RV owners and outdoor recreation enthusiasts, and a financing environment where a lender who does these loans every day can structure an acquisition that works for your specific deal. The RVIA publishes current data on RV shipments and industry growth that is worth bookmarking if you want the macro picture.

    But the investors who win in RV park investing are the ones who go in understanding that they are buying a business, not a check. The parks that perform are the ones with owners who are engaged, financially literate, and willing to do the work of running a hospitality operation with real estate underneath it.

    I built a company working fourteen hour days. I am not telling you that to brag. I am telling you because I want you to know that when I say RV park investing requires real work, I am not trying to scare you off. I am trying to set you up for success. The upside is absolutely there. So is the work. And if you go in knowing both of those things, you are already ahead of most buyers I see in this market.

    If you want help understanding what a deal actually looks like financially before you make an offer, deal screening starts at just $99 and a full acquisition underwrite is priced depending on complexity. Reach out at PVIFinancial.com.

    Related reading:

    For the full acquisition framework in one place, my book From Offer to Operation: The Complete RV Park Investor’s Guide is available for immediate download Here at Gumroad or by searching the title on Amazon.

    Check out the RV Park Resource Library for the full list of posts, updated daily.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • RV Park SBA Loan Default: 6  Harsh Truths Every Owner Needs to Know

    RV Park SBA Loan Default: 6 Harsh Truths Every Owner Needs to Know

    I’ve spent eight years lending my own money against real estate, and one pattern shows up every single time I hear of someone else’s deal going sideways. The people who get hurt worst are the ones who never modeled what failure actually looks like before they signed.

    RV park SBA loan default is a version of that same pattern, and it’s one I underwrite for the same way I underwrite lending risk. You sign the personal guarantee before you’ve collected a single site fee, and most buyers never sit down and map out what happens if the numbers stop working. That’s backwards, and it’s the single biggest gap I see when I review acquisition financials for RV park clients.

    Here’s the part that catches people off guard. The SBA guarantee on your loan protects your lender. It does nothing for you. Let me say that again because it is worth repeating. It does nothing for you. If the park underperforms and the loan can’t be serviced, an RV park SBA loan default can reach your personal cash, non exempt home equity, brokerage accounts, tax refunds, wages, and your future ability to borrow through SBA, FHA, VA, or USDA programs.

    None of that means an SBA 7(a) loan is a bad tool. For most buyers it’s still the best financing option on the table. It just means the downside needs to be underwritten with the same rigor as the upside, and that’s exactly the gap this post is meant to close.

    Why RV park SBA loan default is a long tail risk, not a rare one

    I compare every acquisition I review against my own lending book, where secured first position loans run around 11% annually. That benchmark forces a question most buyers skip: does this deal clear the bar after you account for what happens if it doesn’t perform?

    The SBA doesn’t publish a clean acquisition specific default number, since RV parks get lumped in with startups, expansions, and working capital loans in their reporting. But the cumulative default rate for the 7(a) program over a full 10 year loan term runs close to 8.73%, and most RV park acquisition loans are 10 year notes. Annual purchase rates (what SBA pays lenders on defaulted guarantees, as a share of the active portfolio) have sat in the 1.0% to 1.4% range over the last three fiscal years, with charge off rates well under 1%.

    Translate that into plain terms. Most RV park loans do not end in default. But across a full decade, the odds are high enough that ignoring the tail risk is a mistake, not a shortcut.

    The sequence behind RV park SBA loan default, and where it actually starts

    A missed payment is not the same thing as default, and default is not the same thing as an RV park SBA loan default that follows you home for years. Understanding where one ends and the other begins is the first real defense against RV park SBA loan default risk.

    Delinquency starts the day a payment is late. Default is a breach of the loan documents, which can include missing a payment, letting insurance lapse, moving pledged collateral without approval, or filing bankruptcy. Neither one automatically means the lender has stopped working with you.

    Acceleration is the real turning point. That’s when the lender calls the full loan balance due immediately instead of just the missed payments. Everything before acceleration is about fixing the loan. Everything after is about the lender recovering the debt, and that shift in posture is what actually defines an RV park SBA loan default in practice.

    Once acceleration happens, liquidation follows: collecting receivables, selling equipment and vehicles, and in some cases foreclosing on pledged real estate. This stage is where an RV park SBA loan default stops being a paperwork problem and starts being a recovery process. For loans approved after May 14, 2007, federal rule lets a lender ask SBA to honor the guarantee once a borrower is 60 days delinquent and uncured, but only after the business’s personal property, meaning equipment, inventory, vehicles, and receivables, has been liquidated first. That’s a narrower bar than most owners assume facing an RV park SBA loan default. It does not mean every personal asset gets swept before SBA steps in.

    The DSCR number that tells you how close you actually are to RV park SBA loan default

    Most buyers run a single base case debt service coverage ratio and call it done. I don’t think that’s rigorous enough for a business as seasonal as an RV park, where one bad summer or one new competitor down the road can move revenue more than people expect, and can turn a comfortable loan into an RV park SBA loan default candidate faster than owners think.

    Here’s the stress test I actually run: solve for the revenue level where DSCR falls to exactly 1.0x, using contribution margin instead of a flat expense ratio.

    Say a park runs $1,600,000 in annual revenue, with operating expenses at 42% of revenue and fixed costs of $665,000. Annual SBA debt service is $165,000, which puts EBITDA around $263,000 and DSCR at roughly 1.6x, a healthy looking number on paper.

    Now solve for the floor. Fixed costs plus debt service, divided by the 58% contribution margin, comes out to about $1,431,000. That means the park can only absorb about a 10.6% revenue decline before debt service coverage breaks. If a park depends on one or two long term tenants or a single seasonal event for a meaningful chunk of revenue, that 10.6% cushion disappears fast, and RV park SBA loan default risk moves from theoretical to real. I go deeper on running this exact math in How to Calculate Break-Even for Your RV Park.

    What SBA guaranty purchase actually means for RV park SBA loan default, and what it doesn’t

    This is where I see the most confusion, even among buyers who’ve done their homework everywhere else on RV park SBA loan default risk.

    Say a park’s loan balance sits at $2,200,000 when things fall apart. Liquidating business assets recovers $310,000, leaving a deficiency of $1,890,000. If SBA’s guaranteed share is 75%, SBA reimburses the lender $1,417,500.

    It’s tempting to read that as, “SBA covered most of it, so I only owe the rest.” That’s not how it works. SBA’s payment goes to the lender, not to reducing your debt. You still owe against the full $1,890,000 deficiency. What changes is who holds the claim, since SBA now has a 75% interest in that deficiency and the lender keeps the remaining 25%. If a later settlement collects $500,000 from you directly, that splits roughly $375,000 to SBA and $125,000 to the lender at that same ratio. The total owed doesn’t shrink just because SBA wrote a check to your lender.

    Once the deficiency is set, an Offer in Compromise becomes the path forward if the debt can’t be paid outright. That’s an ability to pay analysis, not a negotiation over what discount feels fair, built around personal financial statements, tax returns, bank and brokerage records, and a home equity review. If it’s not resolved at that stage, it can move to Treasury, where collection tools expand to wage garnishment, tax refund offsets, credit reporting, and in some cases DOJ referral, and the same debt gets considerably harder to unwind.

    What I check before a client signs an SBA note to keep RV park SBA loan default off the table

    I underwrite RV park deals the same way I underwrite my own lending positions, looking for the failure case first, because that’s where RV park SBA loan default risk actually hides.

    I diligence the lender before I diligence anything else in the financing stack. How many RV park or ETA acquisition loans has this lender actually closed? What does their deferment process look like when a borrower calls early? What’s their track record on purchase and recovery for comparable deals? For more on what a good lender is actually evaluating, see What a Lender Actually Looks at Before Approving an RV Park Loan.

    I price customer and revenue concentration explicitly instead of hoping it holds. If a handful of long term sites or one seasonal contract carry a large share of revenue, that gets reflected in the purchase price, an earnout, or seller financing terms, not just noted and ignored.

    I treat working capital as a form of debt protection. A park that needs $400,000 to run through its slow season and closes with $150,000 hasn’t been bought efficiently, it’s been bought with a liquidity gap baked in.

    I use seller financing as a shock absorber wherever the seller will agree to it. A note on standby or interest only terms creates real breathing room that a note amortizing on day one does not. I break down how to structure these terms in How to Analyze a Seller Carry Deal.

    I insist on a cash reserve that doesn’t get touched, whether that’s three to six months of debt service or a minimum balance held after every closing cost, even when the SBA loan itself doesn’t require one. I’ve watched what happens when owners skip this step in RV Park Reserve Fund Mistakes.

    And I verify the earnings the way a lender should, not the way a lender will settle for. Owner add backs, seasonal timing, deferred maintenance, and one good summer dressed up as a trend all need to be pressure tested before the purchase price gets locked in. I wrote about exactly what goes wrong when this step gets skipped in The $312,000 Mistake.

    So how much do you actually owe once RV park SBA loan default happens?

    These are the three questions I get asked most often about RV park SBA loan default once the deficiency stage arrives.

    Q: If my loan balance is $2,200,000 and the park defaults, do I owe the whole $2,200,000, even after SBA pays my lender?

    A: No. Liquidating business assets recovers a chunk of that first, in the earlier example, $310,000, which brings the number down to a $1,890,000 deficiency. That deficiency, not the original loan balance, is what you actually owe.

    Q: Once SBA pays the lender its guaranteed share, does that reduce what I owe?

    A: No, and this is the misconception I run into most. SBA’s payment reimburses the lender. It doesn’t forgive you or shrink the deficiency. It just changes who holds the claim to that $1,890,000 going forward, split between SBA and the lender according to their guaranteed percentage.

    Q: So what’s the one number that actually matters here?

    A: The deficiency after collateral liquidation. That’s the figure that follows you personally through the guarantee, not the original loan amount and not the SBA’s reimbursement to the lender.

    The bottom line on RV park SBA loan default

    RV park SBA loan default follows a predictable sequence: delinquency, a workout window if you engage early, acceleration if you don’t, liquidation, SBA guaranty purchase, a deficiency, and either a settlement or a slow slide toward Treasury collection. Not every owner goes through every stage of RV park SBA loan default. Plenty cure early, restructure, or sell the park as a going concern before it gets anywhere close to this.

    But the guarantee itself never disappears just because SBA steps in to reimburse the lender, and that’s the single fact every RV park SBA loan default case eventually comes back to. Understanding that now, while the park is performing and there’s no pressure on the clock, is worth far more than trying to learn it during a workout call.

    If you want a second set of eyes on a deal’s DSCR, working capital position, or lender terms before you sign, that’s exactly the kind of work I do at PVIFinancial.com.

    Related reading:

    For structuring a purchase the right way from the start, check out my RV Park Resource Library (https://pvifinancial.com/rv-park-resource-library/), and for the full walkthrough on underwriting an acquisition, my book From Offer to Operation: The Complete RV Park Investor’s Guide is available on Gumroad here: https://wendipvifinancial.gumroad.com/l/kqmyb or by searching the title on Amazon.

    For more on how SBA guaranty purchase and recovery actually works at the program level, Live Oak Bank (https://www.liveoakbank.com/) is a solid outside resource, since they’re one of the largest SBA lenders in the country.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • Buying an RV Park: A Practical 2026 Roadmap From First Look to First 90 Days

    Buying an RV Park: A Practical 2026 Roadmap From First Look to First 90 Days

    Buying an RV park looks simple from the outside. Find a park, check the cap rate, get a loan, collect the site rent.

    The reality has more moving parts, and the buyers who get hurt are the ones who skip steps. I underwrite these deals for a living, and this roadmap walks through the major stages of buying an RV park, from the market itself to your first 90 days as an owner.

    Why RV Parks Are Attracting Investors in 2026

    The demand side keeps growing. The RV Industry Association reports over 11 million American households now own an RV.

    Remote work turned full-time RV living into a real option for working professionals. Boomers are retiring into the lifestyle, and Millennials are the fastest-growing buyer group.

    The supply side barely moves. Most counties make new park zoning very difficult, and some existing parks get converted to housing developments and disappear.

    Growing demand plus near-fixed supply is the backdrop for anyone buying an RV park right now.

    One caution: an RV park is not passive income. It is part commercial real estate, part hospitality business. The land appreciates like real estate, but the revenue behaves like a hotel, with seasonality, reviews, and guests who expect service. That is why parks can outperform passive real estate, and why they demand more of you.

    Site Mix: What Actually Drives the Money

    Two 100-site parks can have completely different earning power. Site mix is the biggest reason, and it is the first thing I study when buying an RV park.

    Full hookup sites (water, sewer, electric) are the premium product. Typical nightly rates run $50 to $80 in most markets, higher at destination resorts.

    Partial hookup sites rent meaningfully lower. Tent and primitive sites lower still.

    Converting a partial site to full hookup typically costs $5,000 to $15,000 per site, and it is one of the cleanest value-add plays in the asset class.

    Electrical service matters just as much. Modern rigs need 50-amp power. A park stuck on 30-amp pedestals is invisible to the highest-paying guests, and upgrades run a few thousand dollars per site. Count the 50-amp sites yourself when buying an RV park, and never take the listing’s word for it.

    Guest mix is the other half of the equation. Monthly long-term guests provide stable income at lower rates, usually a few hundred to $1,500 per month. Nightly transient guests pay far more but disappear in the off-season, and balancing the two is a core decision in buying an RV park.

    Neither is better in the abstract. What matters is knowing which business you are actually buying.

    Clearly break down your revenue mix. Site rent is usually 70 to 85 percent of total revenue. The rest comes from cabins, the camp store, laundry, and fees. Cabins deserve special attention, because they rent for double or triple a site and open the park to people who do not own an RV at all.

    Occupancy Is a Curve, Not a Number

    The occupancy pattern depends entirely on where the park sits, and reading it correctly is step one in buying an RV park.

    Snowbird markets (Florida, desert Southwest): full all winter, quiet all summer.

    Northern parks: most revenue lands between Memorial Day and Labor Day, some close completely for winter.

    Year-round markets: steadier occupancy, often in the 70s and 80s.

    Highway travel-route parks: lower overall, swinging with the seasons.

    None of these patterns is a problem by itself. But you need to see the pattern clearly before you commit.

    Plot the trailing 24 to 36 months of revenue by month before you even think of writing an offer. If the seller cannot produce monthly numbers, that tells you something too. Buying an RV park without seeing the revenue curve is buying blind.

    The Seller’s Books Will Be Messy. Plan on It.

    Here is what nobody tells you about buying an RV park: the financials you receive will almost never be usable as-is.

    Most parks run cash basis books in QuickBooks, or a shoebox. The P&L often includes the owner’s truck, health insurance, sometimes groceries.

    Revenue gets recorded when deposits hit the bank, not when the stays happened. That distorts seasonality and makes year-over-year comparisons meaningless, which is a real problem when buying an RV park.

    Before you can value anything, rebuild the revenue on an accrual basis and strip the personal spending out of the expenses. In my underwriting work, that reconstruction regularly moves NOI by 10 to 20 percent, in either direction.

    Every number that follows, the price, the loan, the returns, sits on top of that rebuilt NOI. Get it right first.

    Valuation: Cap Rates and What Parks Actually Trade For

    RV parks are valued on cap rates: NOI divided by purchase price. Rough 2026 ranges by park quality:

    Destination resorts with premium amenities: 5 to 7 percent

    Quality established parks: 7 to 9 percent

    Standard parks: 8 to 10 percent

    Value-add and heavily seasonal parks: 10 to 13 percent or higher

    Lower cap rate means higher price for the same income. The higher cap rates on rougher parks are compensation for risk and work, not free yield.

    Expense ratios are the other half of NOI. Well-run parks operate at 30 to 45 percent of revenue. When a broker package shows 25 percent on a full-amenity park, expenses are missing, usually a management fee, real maintenance, and reserves.

    A quick worked example. A 90-site park: 70 full hookups averaging $55 a night at 58 percent occupancy is about $820,000. Twenty partial sites add roughly $72,000. Cabins, store, laundry, and fees add about $61,000. Gross revenue lands near $953,000.

    At a realistic 42 percent expense ratio, NOI comes in around $553,000. At a 9 cap the park is worth about $6.1 million. At an 8 cap, $6.9 million. Small assumption changes move big money when buying an RV park.

    That $800,000 spread between two defensible cap rates is why you never anchor on the broker’s number when buying an RV park.

    The trap: a package showing a 9 cap on pro forma NOI might be a 6 cap on real trailing numbers. Underwrite off verified trailing twelve month actuals, adjusted for a market-rate management fee even if you plan to self-manage. Every lender and every future buyer will apply that fee whether you did or not.

    Due Diligence When Buying an RV Park: What to Inspect and Verify

    Infrastructure first. These are the systems that carry six-figure price tags when they fail.

    Water: well or municipal, capacity at peak weekends, pipe age, testing history, compliance.

    Sewer: municipal, septic, or hybrid, capacity at full occupancy, dump station condition. Septic surprises are expensive and slow to fix.

    Electric: amps per site, pedestal condition, code compliance.

    Roads and pads: drainage, pad length for modern rigs. Road repair commonly runs $1,000 to $3,000 per site when it comes due.

    Amenities: pool code compliance, bathhouse condition, Wi-Fi infrastructure. Guests now treat Wi-Fi as a utility, not a perk.

    Environmental: a Phase 1 assessment is cheap insurance. Pull the FEMA flood maps, get flood insurance quotes, and ask directly about flooding history. Parks sit near water on purpose, and flood exposure changes your insurance cost, which changes your NOI.

    Permits and zoning: confirm the use is legal, the permits transfer, and no moratorium blocks expansion.

    Budget honestly for what you find. Most parks carry $50,000 to $500,000 in deferred capital needs at acquisition. A first 24-month capex budget of 5 to 15 percent of purchase price is a reasonable planning range when buying an RV park.

    Then the financial diligence, which is what actually kills deals:

    Verify the occupancy claim. Pull the reservation system export and reconcile it against bank deposits and tax returns. When the sources disagree, the claim is unverified, and unverified occupancy gets underwritten down, not taken on faith.

    Question flat rate history. A park that has not raised rates in five years is not automatically upside. Sometimes the market will not bear more. Sometimes the monthly guests leave the moment you try.

    Check the customer base. Repeat guest percentage, geographic origin, and reviews across Google, Campendium, and Good Sam tell you whether the revenue is durable. A park living off one annual event or one aging group of monthlies has concentration risk the P&L never shows.

    Financing: What to Expect in 2026

    SBA 7(a) does the heavy lifting for owner-operator deals up to $5 million. Down payments start around 15 percent for a first-time buyer, repayment stretches as long as 25 years when real estate is involved, and rates adjust with the market rather than staying fixed. Details are at the SBA 7(a) loan page.

    Specialty lenders in outdoor hospitality understand seasonal revenue instead of panicking at it. A generalist lender who has never seen a seasonal curve will slow your deal down at best. If you want a referral to lenders who know this asset class, contact me at PVIFinancial.com.

    Conventional commercial lending takes over on larger deals, roughly $5 million and up, at 25 to 35 percent down.

    Seller financing deserves real attention when buying an RV park. It can cover up to 50 percent of the purchase price, and a seller note on standby can help complete an SBA capital stack. After eight years as a private money lender with over $4 million deployed in first trust deeds, I can tell you a seller willing to carry paper is signaling confidence in their own park, and the note terms are as negotiable as the price.

    Here is what you should internalize about financing: the lender underwrites the deal independently. If your numbers came from the broker’s pro forma, the appraisal will find the gap 60 days into escrow, after your diligence money is spent.

    Buyers who show up with clean, accrual-based, verified financials close faster and negotiate better.

    Where the Real Upside Lives

    Every listing promises upside. Here is where it actually exists, in rough order of reliability:

    Below-market rates. If comparable parks genuinely charge more, raising rates to market is real upside. It takes two or three seasons of gradual increases, not one jump, and only after you have verified the comps.

    Hookup conversions. Partial to full hookup raises per-site revenue substantially when the water and sewer systems can support it.

    Modern operations. Online booking and a real website capture occupancy a phone-and-paper operation loses.

    Amenity additions. Cabins, a proper camp store, expanded laundry. Each adds its own revenue and supports higher site rates across the board.

    Guest mix optimization. Shifting the monthly-versus-transient balance toward what the market rewards moves revenue without touching a single rate.

    The discipline is simple: model each play before you pay for it. Upside you pay the seller for is not upside, it is just price. Buying an RV park at a basis where the value-add belongs to you is the entire game.

    Run It Like an Underwriter, Not a Fan

    Before I finish underwriting any park, the model has to answer five questions:

    What is the verified NOI today? What does real debt service look like? What is the year-one cash-on-cash return? What capital does the park need in the first 24 months? And what has to be true for this deal to beat what the same money earns elsewhere?

    That last question matters most. Buying an RV park is not the goal. Buying the right park at the right basis is the goal, and the discipline to walk away is the most valuable skill in the process.

    Your First 90 Days as an Owner

    Weeks 1 and 2: move the reservation system and bank accounts, update insurance, honor every existing reservation, meet the staff one on one before changing anything.

    Weeks 3 and 4: walk the infrastructure yourself, compare the site mix to what you underwrote, read every review from the past two years.

    Month 2: build your capex priority list from what you now see up close. Review rates with real data. Hold rate changes until at least day 90.

    Month 3: start the strategy work. Marketing improvements, first capital projects, relationships with the county and local businesses.

    And from day one, set up real books. Clean accrual accounting from your first day means you never inherit the mess you just untangled from the seller, and your numbers become the rare set a future buyer’s underwriter does not have to rebuild.

    If buying an RV park is the offense, the financial systems behind it are the defense. Championships get won on defense.

    Common Questions About Buying an RV Park

    How much money do I need?

    Plan on roughly 15 to 20 percent down for an SBA deal as a first-time buyer, plus closing costs, off-season working capital, and a real capex reserve. On a $2 million park, total liquidity of $450,000 to $600,000 is a realistic target.

    What is a good cap rate?

    There is no single number. Destination resorts trade at 5 to 7 percent, established parks at 7 to 9, standard parks at 8 to 10, value-add parks at 10 or above. What matters is that the cap rate sits on verified NOI, not the broker’s pro forma.

    Can I do this with no experience?

    Yes, people do it every year. The ones who succeed try to keep the existing staff through the transition and get professional help on the numbers before they buy, not after something goes wrong. Experience helps, but discipline matters more in buying an RV park.”

    How long does buying an RV park take?

    My lender says they can close in 45-60 days, but it can be up to 90 to 150 days from signed letter of intent to close on an SBA deal if the financial information is not well organized. The search before that can take months, because most listed parks are priced for a buyer who does not check the math.

    Is an RV park passive income?

    No. It is an operating hospitality business. You can hire management, but a market-rate management fee belongs in your underwriting either way.

    What kills most deals?

    Financials that do not survive verification. Occupancy claims the records do not support, pro forma expenses missing a management fee and reserves, and rebuilt NOI coming in far enough below asking that the deal no longer pencils.

    Go Deeper

    I wrote From Offer to Operation: The Complete RV Park Investor’s Guide to walk through the entire acquisition process in detail, from the first broker call through your first season of ownership. It is also on Amazon if you search the title.

    The Resource Library has dozens of posts organized by topic, including deeper dives on valuation, operating expenses, and financing.

    And if you are looking at a specific park right now and want the numbers verified before you commit real money, that is exactly the kind of work I do. Reach out at PVIFinancial.com.
  • RV Park Financing: 5 Hard Truths About Zero Down Deals and Seasonality

    RV Park Financing: 5 Hard Truths About Zero Down Deals and Seasonality

    RV park financing gets pitched as easy money more often than any other part of this business. Zero down, seller carries the whole thing, cash flow from day one. It sounds great right up until you understand what kind of business an RV park actually is, and how a loan behaves when it is attached to income that moves with the calendar. Zero down is not a strategy in this asset class. It is a countdown. Let me walk you through why, and more importantly, how to prepare for the seasonality that makes these properties different from almost everything else you could buy. Getting RV park financing right starts long before you ever fill out a loan application.

    An RV park is not an apartment building with a signed twelve month lease. Income swings hard, season to season, site to site. A park can do 65 or 70 percent of its annual revenue between April and September. That is not a flaw, it is the business model. But a loan payment does not take the winter off, and that mismatch between lumpy income and fixed debt service is where undercapitalized buyers die. Here are five hard truths about how RV park financing really works.

    Truth 1: Lenders price RV park financing around seasonality, and you should too

    Ask any lender who actually does outdoor hospitality what worries them most about these properties and seasonality is at or near the top of the list. Occupancy in July tells them very little about your ability to make the February payment. That is why RV park financing gets underwritten on trailing twelve month revenue rather than a hot summer quarter, why lenders discount transient income more than long term site income, and why they want to see monthly financials, not just an annual P&L. If your lender is going to look at your income month by month, you need to look at it month by month first. Before you ever apply for a loan, build a twelve month cash flow model for the specific park you are buying, using its actual monthly history, not an annualized average. An average hides the exact months that will hurt you. Smart RV park financing starts with knowing your monthly numbers before the bank asks for them.

    Truth 2: DSCR is your survival margin, not a box to check

    Debt service coverage ratio is the number that decides whether you sleep at night, and it sits at the center of every RV park financing decision. DSCR is your net operating income divided by your annual loan payment. Most lenders want at least 1.25x on an RV park, meaning the park earns 25 percent more than the loan payment. That 25 percent is not profit padding, it is the cushion that carries you through the slow months that are coming whether you plan for them or not. Here is the part most buyers miss: annual DSCR can look fine while monthly DSCR is a disaster. A park with $90,000 of NOI and a $72,000 annual payment covers at 1.25x on paper. But if $60,000 of that NOI shows up between April and September, then October through March produces $30,000 of NOI against $36,000 of payments. You are negative for six straight months and you make it up in summer, if summer cooperates. One rainy season, one gas price spike, one road construction project on the highway that feeds your park, and the annual number stops mattering. When I underwrite a park, I calculate coverage month by month for exactly this reason, and I stress test occupancy down 10 and 20 percent to see where the deal breaks. This is why RV park financing has to be underwritten monthly, not annually.

    Truth 3: Zero down RV park financing destroys the math before you get the keys

    Run the RV park financing numbers on a real example. Say a park is priced at $1,000,000 with $90,000 of verified NOI, a 9 cap, a reasonable deal on its face. Finance it with 25 percent down at 7.5 percent on a typical 25 year amortization and your loan is $750,000, your payment is roughly $66,500 a year, and your DSCR is a healthy 1.35x. That is real cushion, room for a soft season, a repair, a vacancy stretch. Now finance the same park with zero down. The loan is $1,000,000, the payment jumps to roughly $88,700 a year, and the park earns $90,000. Your DSCR is 1.01x. You clear about $1,300 for the entire year, before a single vacancy, a single repair, or a single slow month. That is not cash flow, that is a rounding error standing between you and default. Every dollar of rent is spoken for before you touch it, in a business where the rent does not hold still. One soft summer and you are feeding the property out of pocket to keep something that was sold to you as passive income. The down payment was never the obstacle. It was the cushion. Zero down RV park financing removes that cushion and calls it a feature.

    Truth 4: The balloon payment is where zero down deals actually die

    Most seller carried RV park financing deals and many bank loans carry a balloon, commonly at year three or five. Here is what that looks like on the zero down version of our example. After three years of payments on that $1,000,000 note on a 25 year amortization, you still owe about $954,000, because early payments are almost entirely interest. Now the balloon comes due and you need to refinance. A new lender will typically lend 70 to 75 percent of appraised value on a park. If the park still appraises at $1,000,000, the most they will hand you is around $700,000 to $750,000. You owe $954,000. You need to show up with roughly $200,000 to $250,000 in cash to close the gap, on a property that has been eating your lunch money every winter. You do not have it, so the park goes back to the person who sold it to you. He keeps the payments you made. You keep the lesson. This is not a rare outcome, it is the designed outcome of a zero down balloon structure on a thin margin asset. If you take seller financing, and seller financing done right can be a genuinely good tool, negotiate a term long enough to season the property and build equity, and know your refinance math before you sign, not at month 30. The balloon is where RV park financing punishes hope and rewards preparation.

    Truth 5: Reserves and a monthly plan are the real down payment on survival

    Preparing financially for seasonality is not complicated, but almost nobody does it. Here is the framework I use. First, build the month by month cash flow model I mentioned above, using at least two years of the park’s actual monthly revenue if you can get it. Identify your worst stretch, usually a run of three to five consecutive negative months. Second, fund a reserve account before closing that covers that entire gap, plus a margin. At minimum I want to see three months of debt service plus fixed operating costs sitting in cash on day one, and for a heavily seasonal park, six months is not paranoid, it is professional. Third, hold a separate capital expenditure reserve, because septic systems, electrical pedestals, and well pumps do not check your occupancy calendar before they fail. Fourth, treat summer cash like it belongs to winter, because it does. A simple discipline of sweeping a fixed percentage of peak season revenue into the reserve account every month will do more for your survival than any occupancy hack. And on the loan side, shop RV park financing structures that respect seasonality. An SBA 7(a) loan can get you into a park with as little as 10 to 15 percent down on a fully amortizing term up to 25 years with no balloon, which removes the single deadliest feature of these deals. You can read how the program works directly at the SBA’s 7(a) loan page, and lenders like Live Oak Bank specialize in outdoor hospitality and understand seasonal income when they underwrite. The right RV park financing structure plus a funded reserve is what turns a seasonal business into a stable one.

    What smart RV park financing actually looks like

    Buy for stable income, verified from real monthly financials, not a broker’s pro forma. Buy with real equity, 20 to 30 percent down, so the loan payment fits inside the income with room to breathe and so you have something to refinance against when the term ends. Buy with coverage, 1.25x annually and positive or fundable monthly, stress tested before you commit. And walk into closing with reserves already funded, because the slow season is not a risk, it is a certainty with a date on the calendar.

    If you want to go deeper on any of this, my Resource Library at PVIFinancial.com/rv-park-resource-library has guides on acquisition, cash flow management, and financial systems for park owners.

    And if you are evaluating a purchase right now, my book, From Offer to Operation: The Complete RV Park Investor’s Guide, walks through the entire process from underwriting to your first year of operations. It is on Gumroad and you can also find it on Amazon by searching the title.

    If you are looking at a deal and you want the RV park financing numbers run before you sign, the DSCR, the seasonal cash flow model, the refinance math, that is exactly the kind of work I do. Reach out at PVIFinancial.com.
  • RV Park Mail Policy: The 1 Simple Rule That Protects Your Business From a Costly Legal Nightmare

    RV Park Mail Policy: The 1 Simple Rule That Protects Your Business From a Costly Legal Nightmare

    RV park mail policy is one of those operational details that feels minor until the moment it is not. Most owners set it up once and forget about it, or worse, never set it up at all. And then one day they have a guest who has been on site for six weeks who enrolled their kid in the local school using the park address, has their driver’s license updated to your address, and is receiving government benefits at your location. Now you have a problem that no park rule can fix quickly.

    Here is what you need to understand about why your mail policy matters more than almost any other operational decision you will make.

    RV park mail policy is a legal classification issue, not just a convenience issue

    The difference between a transient lodging facility and a residential property is not just about how long people stay. It is about what evidence exists that someone considers your park their home. Courts, school districts, government agencies, and landlord-tenant law all look at the same kinds of evidence when making that determination. Mail is at the top of that list.

    When a guest uses your park address to receive mail, especially mail tied to identity and residency like a driver’s license, school enrollment, government benefits, tax documents, or utility bills, they are building a paper trail that supports a claim that your park is their primary residence. That paper trail does not disappear when you ask them to leave. It becomes the foundation of a legal argument that you no longer have the right to remove them the way you would remove a hotel guest who overstays their welcome.

    This is why your RV park mail policy is a legal classification decision first and an operational rule second.

    When a guest becomes a tenant your options change dramatically

    This is the part that blindsides new park owners. In most states the legal distinction between a transient guest and a residential tenant determines what process you have to follow to remove someone from your property. A transient guest at an RV park can typically be removed under your park rules with relatively short notice. A residential tenant, even one living in an RV, is entitled to full eviction proceedings under landlord-tenant law.

    Full eviction proceedings mean written notices with legally required waiting periods, court filings, hearings, potential continuances, and in some cases months of delay while someone continues to occupy a site you need back. It means legal fees. It means your hands are tied while the situation gets worse. And it means other guests are watching how you handle it.

    The moment a guest can demonstrate residency at your park, whether through mail, school enrollment, a state ID, or any other official document, you have potentially lost the legal high ground that protects your ability to operate as a transient RV park rather than a residential landlord.

    Your RV park mail policy is the first line of defense against this exact scenario playing out in your park. This is exactly why your RV park mail policy needs to be airtight before your first guest ever checks in.

    A strict no mail policy is your first line of defense

    The good news is this is entirely preventable with a clear, consistently enforced policy established from day one. Your park rules should state explicitly that no mail, packages, or deliveries of any kind may be received at the park address. No exceptions. No special circumstances. No accommodating the guest who swears it is just one package.

    When guests push back, and some will, the answer is simple. There are alternatives that work just as well for them and protect your business at the same time. A P.O. box at the local post office costs very little. UPS Store and PostalAnnex locations offer mail receiving services. Amazon lockers are available in most areas for package delivery. These options exist precisely for people whose living situation does not include a permanent mailing address.

    Your no mail policy should be in your park rules, reviewed and signed by every guest at check-in, and enforced without exceptions. The moment you make an exception for one guest you have created a precedent in your RV park mail policy that every other guest can point to.

    What about long term monthly guests?

    This is where it gets more complicated and where a lot of park owners get into trouble. If you have monthly guests who are essentially living in your park full time, the mail policy conversation becomes part of a much larger question about how you are legally classifying those guests and what your state’s laws say about extended stay residents.

    In many states a guest who stays beyond a certain threshold, sometimes 30 days, sometimes longer, may already be entitled to tenant protections regardless of whether they receive mail at your address. If that is your situation you need to know it now, not when you try to remove someone.

    The safest approach for parks with long term monthly guests is to work with an attorney in your state to understand exactly where the legal line is between a transient guest and a residential tenant, structure your lease agreements accordingly, and build your mail policy as one piece of a larger legal framework designed to protect your classification and your rights as an operator. The National Association of RV Parks and Campgrounds is also a good resource for understanding industry standards around guest classification and park operations.”

    A strict no mail policy alone will not protect you if your overall operation looks residential. It has to be part of a consistent, documented approach to how you manage extended stay guests from check-in to check-out.

    A well structured RV park mail policy is one piece of that framework but it cannot do the job alone.

    Put it in writing before you need it

    The time to establish your RV park mail policy is not when you have a problem. It is before your first guest ever checks in. If you are acquiring a park that has been operating without a clear mail policy, or worse one that has been allowing mail delivery, address it immediately. Update your rules. Communicate the change clearly to all current guests with adequate notice. And document everything.

    If you already have guests who have been receiving mail at your park address, talk to an attorney who specializes in landlord-tenant law in your state before you take any action. The situation may be more complicated than a simple rule change can fix, and you want to handle it correctly rather than create additional legal exposure in the process of trying to solve the first problem.

    For more on the financial and legal risks that new owners inherit when they acquire a park with informal policies in place, read The Hidden Financial Risks of Buying a Mom-and-Pop Operation and Long-Term RV Guests Are Taking Over: 5 Ways It Breaks Your Books.

    Documenting and consistently enforcing your RV park mail policy from day one is what keeps you protected.

    The bottom line

    Your RV park mail policy is not a minor operational detail. It is a legal protection that preserves your ability to operate as a transient RV park, remove problem guests, and avoid the time, expense, and stress of residential eviction proceedings. One clear rule, enforced consistently from day one, protects your business, your team, and every guest who is there for the right reasons.

    A clear RV park mail policy enforced from day one is one of the simplest and most powerful protections available to any park operator.

    If you want help thinking through the operational policies and financial systems that protect your park from day one, that is exactly the kind of work I do. Reach out at PVIFinancial.com and let’s make sure your park is set up to operate the way you intend it to.

    If you are setting up your park for the first time or tightening up operations after an acquisition, my book From Offer to Operation: The Complete RV Park Investor’s Guide covers the operational and financial systems every new owner needs from day one, including a comprehensive 60-point due diligence checklist. It is available on Gumroad and on Amazon, just search the title.

    And if you want to browse all of my posts on RV park finance, operations, acquisitions, and bookkeeping organized by topic, visit the PVI Financial Resource Library.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • SBA Loan for RV Park: 7 Critical Things Every Buyer Must Know Before Applying

    SBA Loan for RV Park: 7 Critical Things Every Buyer Must Know Before Applying

    An SBA loan for RV park acquisition is one of the most accessible and powerful financing tools available to outdoor hospitality investors, and one of the most misunderstood. Buyers hear that SBA loans require only 10% down and assume the path to closing is straightforward. It is not always. There are eligibility rules, lender-specific interpretations, deal structure requirements, and common mistakes that derail an SBA loan for RV park transactions at every stage of the process.

    Getting an SBA loan for RV park financing right means understanding the rules before you apply, choosing the right lender before you are under contract, and structuring your deal in a way that actually qualifies. This post walks you through the seven most critical things every buyer needs to know before they pursue SBA financing for an RV park acquisition.

    Here are the seven things every buyer must know before applying for an SBA loan for RV park financing:

    1. Not every RV park qualifies for SBA financing

    The first thing to understand about an SBA loan for RV park acquisition is that eligibility is not automatic. The SBA has specific rules about what types of properties and businesses qualify, and RV parks have a particular requirement that many buyers do not know about until it is too late.

    To qualify for an SBA loan for RV park financing, more than 50% of the park’s revenue must come from short term stays of 30 days or less. This sounds simple but it creates real problems for parks with a significant base of long term or monthly tenants. If your target park has 60% of its revenue coming from monthly or seasonal guests who stay longer than 30 days, it may not qualify for SBA financing regardless of how strong the financials look.

    The 50% short term stay requirement is also interpreted differently by different lenders. Some count monthly tenants as short term. Others do not. This is one of the reasons choosing the right SBA lender for RV park financing is so critical. For more on what lenders look at when evaluating a deal, read What a Lender Actually Looks at Before Approving an RV Park Loan.

    2. The SBA 7(a) and SBA 504 are very different products

    Many buyers pursuing an SBA loan for RV park acquisition do not realize there are two distinct SBA programs and that they work very differently from each other.

    The SBA 7(a) loan is the more flexible of the two. It can be used for business acquisitions including goodwill, working capital, equipment, and real estate. Loan amounts go up to $5 million with repayment terms up to 25 years for real estate. For first time buyers the 7(a) typically requires 10 to15% down, making it the most accessible SBA loan for RV park purchases. Interest rates are variable and capped at a spread over the prime rate.

    The SBA 504 loan is specifically designed for fixed asset purchases, primarily real estate and equipment. It cannot be used to finance goodwill or working capital. The 504 offers long term fixed rate financing which can be attractive when you want payment certainty, but it requires 15% to 20% down and is less flexible for business acquisitions that include intangible value. For most buyers the 7(a) is the better SBA loan for RV park acquisition but your specific deal structure will determine which program fits.

    3. Lender selection is everything when pursuing an SBA loan for RV park financing

    This is the single most important piece of advice for anyone pursuing an SBA loan for RV park financing. Not all SBA lenders are the same. The SBA sets the rules but individual lenders interpret and implement those rules differently, and the difference between a lender who specializes in outdoor hospitality and one who has never financed an RV park can mean the difference between closing your deal and losing it.

    A lender who specializes in SBA loan for RV park transactions understands how to underwrite seasonal revenue. They know that occupancy drops in January and that does not mean the business is struggling. They understand cap rates in the outdoor hospitality space. They have seen the asset class before and they know how to get deals done.

    A generalist lender who has never financed an RV park will apply residential or standard commercial underwriting logic to a seasonal hospitality business and often cannot make the deal work even when the fundamentals are strong.

    I have a direct contact at a lender who finances over 100 RV park loans every single year. If you want an introduction to someone who knows this asset class inside and out and can tell you quickly whether your SBA loan for RV park deal is financeable and at what terms, reach out to me at PVIFinancial.com and I will make the connection. Live Oak Bank is also one of the most well known specialized outdoor hospitality lenders in the country and a strong starting point for any buyer exploring SBA loan for RV park options.

    4. Your personal financials matter as much as the deal

    An SBA loan for RV park acquisition is not just an underwrite of the property. It is also an underwrite of you as the borrower. Your personal credit score, your liquidity after closing, your net worth, your prior business experience, and your personal financial statement all factor into the lender’s decision.

    Most SBA lenders want to see a personal credit score of 680 or higher, though some will go lower depending on the strength of the deal. They want to see that you have sufficient liquidity after closing, meaning your down payment plus closing costs should not wipe out every dollar you have. They want to see relevant business experience, and for an RV park acquisition that means hospitality, property management, or small business ownership experience is a positive signal.

    Get your personal financial statement in order before you apply. Make sure it is current, complete, and professionally presented. A messy or incomplete personal financial statement creates doubt in a lender’s mind at exactly the wrong moment. If you want help packaging your personal financials in a way that gives a lender confidence, that is one of the services I offer at PVIFinancial.com.

    5. The deal structure affects SBA eligibility

    How your deal is structured can make or break SBA loan for RV park eligibility. There are several structural elements that buyers need to understand before they get too far into a transaction.

    Seller financing can work alongside an SBA loan for RV park financing but there are rules. If the seller is carrying a note, the SBA typically requires that note to be on full standby for a period of time, meaning the seller cannot receive payments on their note until after a certain period following closing. Not every seller is willing to accept those terms, so this needs to be discussed early.

    Entity structure also matters. The SBA has rules about who can be a borrower and what ownership structures are eligible. Make sure you have your entity structure reviewed by a lender before you finalize it.

    Finally, the allocation of the purchase price between real estate, equipment, and goodwill affects which SBA program you can use and how the loan is structured. Work with your lender early in the process to structure the deal in a way that maximizes your SBA loan for RV park eligibility.

    6. The timeline is longer than most buyers expect

    One of the most common mistakes buyers make when pursuing an SBA loan for RV park acquisition is underestimating the timeline. SBA loans take longer to close than conventional financing, and in a competitive market where sellers want certainty and speed, a longer timeline can put you at a disadvantage.

    A typical SBA loan for RV park transaction takes 60 to 90 days from application to closing, sometimes longer if there are appraisal issues, environmental concerns, or title complications. Build that timeline into your LOI and purchase agreement. Make sure your due diligence period and your financing contingency window are long enough to accommodate the SBA process without putting you in a position where you are asking for extensions under pressure.

    The best way to compress the timeline is to have your personal financial statement ready, your tax returns organized, your business plan prepared, and your lender selected before you are under contract. The more prepared you are on day one of the application process, the faster your SBA loan for RV park transaction will move.

    7. Get the deal underwritten before you apply

    The final thing every buyer needs to know about an SBA loan for RV park financing is that the lender’s underwriting and your underwriting need to tell the same story. If you submit a deal to a lender based on the seller’s NOI and the lender’s underwriter rebuilds the numbers and gets a very different picture, your loan gets denied or significantly restructured and you may lose your earnest money in the process.

    Before you apply for an SBA loan for RV park acquisition, rebuild the NOI yourself using realistic expense assumptions, stress test the occupancy, and make sure the deal supports the loan amount you are requesting at the debt service coverage ratio the lender requires. Most SBA lenders want to see a DSCR of at least 1.25, meaning the park’s NOI needs to be at least 1.25 times the annual debt service.

    If your deal does not meet that threshold at your reconstructed NOI, you have three options. Negotiate the price down, increase your down payment to reduce the loan amount, or walk away. Knowing this before you apply saves you weeks of time and protects your earnest money.

    The Small Business Administration has detailed information on both the 7(a) and 504 programs including current rates, eligibility requirements, and how to find an approved lender in your area.

    If you want help making sure your deal is lender-ready before you apply, I offer acquisition underwriting often with a 24-hour turnaround. You send me the financials and I hand you back a complete analysis including reconstructed NOI, DSCR calculation, and a clear picture of whether your deal supports the loan amount you need. Reach out at PVIFinancial.com and let’s make sure your SBA loan for RV park application is built on the right numbers.

    ~Wendi | Fractional CFO | PVIFinancial.com๎–๎€ป๎ƒ๎ƒป๎ƒน๎„

    Read this next: How to Buy an RV Park in a Competitive Market: 7 Moves That Win Deals

  • How to Buy an RV Park in a Competitive Market: 7 Moves That Win Deals

    How to Buy an RV Park in a Competitive Market: 7 Moves That Win Deals

    If you are trying to figure out how to buy an RV park in a competitive market, you are not alone, and the competition is real. The outdoor hospitality space has exploded in popularity, and the supply of quality parks for sale has not come close to keeping up with demand. Good deals get multiple offers. Sellers know their leverage. And buyers who are not prepared move slow, lose deals, and wonder what happened.

    Here is what serious buyers who know how to buy an RV park in a competitive market do differently.

    How to Buy an RV Park in a Competitive Market: 7 Moves That Win Deals

    1. You have to be underwritten before you make an offer

    This is the single biggest mistake I see new investors make. They fall in love with a deal, make an offer, and then start running the numbers. By the time they figure out what the deal is actually worth, the seller has already accepted someone else’s offer or the LOI window has closed.

    Understanding how to buy an RV park in a competitive market starts with having your numbers ready before you fall in love with a deal. That means looking at the trailing 12 months of revenue and expenses, stress-testing occupancy, modeling your financing, and building a real NOI picture, not the one the broker handed you. You need to know your max price before you enter a negotiation, not after. If you want to understand what that rebuild actually looks like, start with What is NOI? And How to Find the REAL Number in an Acquisition.

    This is the foundation of how to buy an RV park in a competitive market and the step most buyers skip entirely.

    2. Fast underwriting is a competitive advantage

    Most buyers take a week or two to run their numbers. If you can turn a full underwrite in 24 hours, you show up to every deal faster and more credible than the competition. Speed and accuracy are the two things that define how to buy an RV park in a competitive market successfully.

    This is exactly where working with a Fractional CFO who specializes in RV park acquisitions changes the game. I offer deal underwriting as a standalone service for buyers who need speed and accuracy. If you want to visually see how to buy an RV park in a competitive market, send me the financials, I build the model, and you have a decision-quality analysis often within 24 hours. You know your offer price, your cap rate, your cash-on-cash return, and your risk flags before you ever pick up the phone with the broker. Deal screening starts at just $99 and a full acquisition underwrite is priced depending on complexity. You can see the full breakdown at PVIFinancial.com.

    That is how you buy an RV park in a competitive market and actually win.

    3. Stop relying on the broker’s numbers

    Brokers represent sellers. The OM they hand you is built to make the deal look as good as possible. Expense ratios are often understated. Vacancy assumptions are optimistic. Revenue projections include upside that may or may not materialize.

    Your job is to recast those numbers based on reality. That means using actual industry expense ratios, realistic occupancy by season, market rate comparisons for the area, and your own financing assumptions. I covered exactly how this plays out in The $312,000 Mistake: What Happens When a Buyer Accepts the Seller’s NOI Without Rebuilding It. If the deal still works after your recast, you have something worth pursuing. If it only works using the broker’s numbers, walk away.

    This is one of the most important things to understand about how to buy an RV park in a competitive market.

    4. Know what you’re actually buying

    An RV park is a business, not just a piece of real estate. The land matters, but so does the revenue mix, the customer base, the online reputation, the utility infrastructure, the age of hookups, the permit status, and a dozen other operational factors that do not show up on a cap rate summary.

    Before you get too deep into any deal, make sure you understand where the revenue actually comes from. Is it seasonal or year-round? Is it heavily OTA-dependent? Are there long-term tenants subsidizing the numbers in ways that inflate NOI but limit upside? How old are the electrical pedestals? These are not afterthoughts, they are part of the underwriting. The Due Diligence Items Nobody Talks About is a good place to start, and so is Before You Fall in Love With That RV Park, Do This First. These posts will help you learn how to buy an RV park in a competitive market.

    5. Get your financing pre-organized

    Competitive sellers favor buyers who can close. If you show up to a deal still figuring out how you are going to finance it, you are already behind. Know your lender before you need them. Understand whether your deal is SBA-eligible or conventional. Have a conversation with a lender who specializes in outdoor hospitality before you are under contract so you know your parameters going in.

    A pre-organized buyer moves faster and negotiates stronger. If you want to understand what lenders are actually looking at when they evaluate a deal, read What a Lender Actually Looks at Before Approving an RV Park Loan.

    Buyers who know how to buy an RV park in a competitive market show up with their financing already figured out.

    6. Build relationships with brokers before you need them

    The best deals in outdoor hospitality do not always make it to LoopNet. Brokers who work this niche have buyers lists and they call their trusted buyers first. If you are not on those lists, you are competing over whatever is left.

    That means proactively reaching out to brokers who specialize in RV parks and campgrounds, telling them exactly what you are looking for, and following up consistently. Be someone they want to call.

    Building broker relationships before you need them is one of the most underrated strategies for how to buy an RV park in a competitive market.

    7. Make clean offers

    One of the most overlooked aspects of how to buy an RV park in a competitive market is how you present yourself as a buyer. Know your price, know your contingency timeline, and do not load up the LOI with unnecessary complexity. Sellers who have multiple offers on the table are going to choose the buyer who looks the most capable of closing, not necessarily the one with the highest price.

    A clean, well-structured offer from a credible, prepared buyer beats a messy high offer more often than people think.

    One more thing most buyers never think about until it is too late: how you present yourself financially matters as much as the offer itself. A seller with multiple LOIs on the table is going to feel more confident in the buyer whose personal financial statement is clean, current, and organized, not the one who scrambles to email over a blurry PDF at the last minute.

    I offer personal financial statement review and packaging as part of my acquisition support services. I will look at what you have, identify anything that could give a seller or lender pause, and help you put together a buyer package that signals you are serious, qualified, and ready to close. It is one of those things that costs very little and can absolutely be the difference in a competitive situation.

    To buy an RV park in a competitive market you have to be fully prepared. If you want help getting your financials buyer-ready, reach out at PVIFinancial.com.
    The bottom line

    Knowing how to buy an RV park in a competitive market is not impossible, but it is not easy either. The investors who are winning deals are the ones who are prepared before the opportunity shows up, not scrambling to get ready after it does.

    If you want help on the financial side of your next acquisition, from underwriting to deal structure to understanding what the numbers are really telling you, that is exactly what I do. Reach out at PVIFinancial.com and let’s talk about your deal.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • How to Evaluate an RV Park Deal: The 6โ€‘Step Proven System That Exposes Hidden Truths in the Numbers

    How to Evaluate an RV Park Deal: The 6โ€‘Step Proven System That Exposes Hidden Truths in the Numbers

    Knowing how to evaluate an RV park deal is the single most important skill you can develop as an outdoor hospitality investor. The market is full of parks listed at prices that only work if you accept the seller’s numbers without question. It is not that buyers are careless. It is that most buyers have never been taught a system for pulling those numbers apart and rebuilding them from scratch. They look at the asking price, glance at the occupancy rate, and trust that the broker package reflects reality. Sometimes it does. Often it does not. And the difference between those two outcomes can cost you hundreds of thousands of dollars.

    This post gives you the system I use to evaluate every deal that crosses my desk, step by step, so you can build a clear picture of what any park is actually worth before you ever make an offer. Here is the system:

    Step 1: Verify gross revenue before you do anything else

    The first step in learning how to evaluate an RV park deal is confirming that the revenue number you are working with is real. This sounds obvious but it is where most buyers skip ahead too fast.

    Ask for three years of P&Ls and the trailing 12 months of bank statements. Then match the deposits in the bank statements to the revenue reported on the P&L month by month. If the numbers do not line up, stop and ask why before you go any further. Common discrepancies include revenue running through a personal account, seasonal timing differences, or outright overstatement of income.

    Also look at the revenue trend across three years. Is it growing, flat, or declining? A park showing peak revenue two years ago and declining numbers since is a very different investment than one with steady growth. The trend tells you as much as the number itself.

    Most new investors donโ€™t realize that learning how to evaluate an RV park deal starts with understanding seasonal revenue patterns. Be sure to pay close attention to this.

    Once you have confirmed the revenue is real and the trend makes sense, write down your verified gross revenue number. That is your starting point for everything that follows, and the baseline needed in how to evaluate an RV park deal.

    A big part of learning how to evaluate an RV park deal is knowing which operational metrics actually matter and which ones are just noise, and verifying gross revenue is definitely number one.

    Step 2: Rebuild expenses from scratch

    This is the step that separates buyers who know how to evaluate an RV park deal from those who get burned. The seller’s expense number is almost never the right expense number for you as the new owner.

    Here is why. Sellers often understate expenses in ways that are entirely legal and sometimes unintentional. They may pay themselves a below-market management salary or no salary at all. They may have deferred maintenance for years. They may own their equipment outright and not account for replacement costs. They may have relationships with vendors that will not transfer to you.

    To rebuild expenses properly, go line by line through the P&L and ask these questions for each category:

    Is this expense realistic for a third-party owned and managed park? Management fees for a professionally managed park typically run 8% to 12% of gross revenue. If the seller manages it themselves and shows zero management expense, add that back in.

    Is this expense complete? Look for missing categories like capital reserves, which should be budgeted at 3% to 5% of gross revenue, and insurance, which many sellers underreport.

    Are there any one-time expenses that should be excluded or one-time revenues that should not be counted going forward?

    When you are done rebuilding expenses, most parks will show a higher expense total than the seller reported. That is normal and expected. For more on what a clean expense rebuild looks like, read RV Park Expenses That Ambush New Owners: 5 Costs Nobody Warns You About After Closing.

    This is one of the most important parts of how to evaluate an RV park deal and the step most buyers rush through.

    Step 3: Calculate your own NOI

    Once you have verified revenue and rebuilt expenses, subtract your expenses from your gross revenue. The result is your reconstructed Net Operating Income, or NOI. This is the number the entire valuation is built on, and it is almost always different from the NOI the seller or broker presented.

    Your reconstructed NOI is the only number you should use going forward. Do not go back to the broker’s NOI at any point in the analysis. If you want to understand why that matters in dollars, read The $312,000 Mistake: What Happens When a Buyer Accepts the Seller’s NOI Without Rebuilding It.

    Understanding how to evaluate an RV park deal really comes down to this step. A wrong NOI produces a wrong valuation every single time. There is no shortcut around it, and no version of how to evaluate an RV park deal that skips this step that ends well.

    Step 4: Apply a market cap rate to determine value

    Now that you have your reconstructed NOI, you can calculate what the park is actually worth. The formula is simple:

    Value = NOI divided by Cap Rate

    The cap rate is the rate of return the market expects for this type of asset in this location. RV parks and campgrounds currently trade in the 7% to 10% cap rate range depending on location, size, amenities, and quality of the revenue stream. Smaller parks in secondary markets typically trade at higher cap rates, meaning lower prices relative to income. Larger, well-located parks with strong occupancy and diversified revenue trade at lower cap rates.

    Here is a quick example. If your reconstructed NOI is $150,000 and the market cap rate for this type of park is 8%, the indicated value is $150,000 divided by 0.08, which equals $1,875,000. If the seller is asking $2,500,000, you now know exactly how far apart you are and why.

    For a deeper explanation of cap rates, read The Number That Tells You If You’re Overpaying for an RV Park Before You Make an Offer.

    Step 5: Stress test the deal

    Knowing how to evaluate an RV park deal means going beyond the best-case scenario. After you calculate value at current NOI, you need to stress test the deal by asking what happens if things go wrong.

    Run three scenarios:

    Base case: Current verified NOI at your market cap rate. This is what you calculated in step 4.

    Downside case: Reduce revenue by 15% to 20% to simulate a soft season, a platform policy change, or a key tenant leaving. Rebuild NOI with that lower revenue and see what the park is worth and whether it still cash flows after debt service.

    Stress case: Reduce revenue by 30% and add a major unexpected capital expense, a failed septic system or a full electrical pedestal replacement. Does the deal survive? Can you still service the debt?

    If the deal only works in the base case, it is a fragile deal. A park that still makes sense in the downside case is a much safer investment. For a real example of occupancy stress testing in action, read RV Park Occupancy Rate: 3 Dangerous Reasons It’s Lying to You.

    Step 6: Model your actual cash on cash return

    The final step in how to evaluate an RV park deal is calculating what you personally will make on your invested capital. Cap rate tells you what the asset is worth in the market. Cash on cash return tells you what it puts in your pocket relative to your down payment.

    Here is how to calculate it:

    Start with your reconstructed NOI. If your expense rebuild in Step 2 was done correctly, property taxes and insurance are already included as line items, which means your NOI is already net of those costs. From your NOI, subtract your annual debt service, your mortgage payment including principal and interest. The result is your pre-tax cash flow, meaning what the park actually puts in your pocket before income taxes.

    Divide that pre-tax cash flow by your total cash invested, your down payment plus closing costs plus any immediate capital improvements needed at closing. That gives you your cash on cash return.

    A healthy RV park acquisition typically targets a cash on cash return of 8% to 12% in year one. If the deal is showing 3% or 4% cash on cash at current NOI and current financing rates, the numbers are not working and you need to either negotiate the price down or walk away.

    This final calculation is where many buyers finally see clearly that how to evaluate an RV park deal is not about whether you like the park. It is about whether the numbers support the investment at the price being asked.

    The RV Industry Association tracks industry benchmarks and market data that can help you calibrate your assumptions when you are modeling a deal.

    Putting the system together

    Here is the full 6-step system in order:

    Step 1: Verify gross revenue against bank statements and check the trend.
    Step 2: Rebuild expenses from scratch using realistic third-party ownership assumptions.
    Step 3: Calculate your own reconstructed NOI.
    Step 4: Apply a market cap rate to determine indicated value.
    Step 5: Stress test with downside and stress scenarios.
    Step 6: Calculate cash on cash return on your actual invested capital.

    Every time you look at a new deal, run it through all six steps before you form an opinion on whether it works. The parks that look great after all six steps are worth pursuing. The ones that only look great after step one or two are the ones that get buyers into trouble. A good broker should be also able to explain how to evaluate an RV park deal in a way that highlights both the financials and the guest experience.

    Once you understand how to evaluate an RV park deal, the whole process of analyzing cash flow and longโ€‘term potential becomes far less intimidating.

    If youโ€™re trying to grow your portfolio, mastering how to evaluate an RV park deal can give you a major edge over other buyers.

    If you want help learning how to evaluate an RV park deal, or running this system on a specific deal, I offer acquisition underwriting and can often do it with a 24-hour turnaround. You send me the financials and I hand you back a complete model with all six steps completed, your reconstructed NOI, your indicated value, your stress test scenarios, and your projected cash on cash return. Reach out at PVIFinancial.com and let’s look at your deal together.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • RV Park Due Diligence Checklist: 10 Critical Items That Protect You From a Costly Mistake

    RV Park Due Diligence Checklist: 10 Critical Items That Protect You From a Costly Mistake

    Every serious buyer needs an RV park due diligence checklist before they get anywhere near a closing table. Due diligence is not a formality. It is the only window in the entire transaction where you have the legal right to demand the truth, verify every number, and walk away without losing your earnest money if the facts do not support the purchase. Most buyers do not use that window well. They get emotionally attached to the deal, rush through the checklist, and find out what they missed six months after they close.

    This post gives you the RV park due diligence checklist I use when I underwrite deals for buyers, so you know exactly what to look for and why each item matters. Here is what every serious buyer needs to review before they close:

    1. Three years of profit and loss statements

    The first item on any RV park due diligence checklist is the financials, and not just one year of them. You need three full years of P&Ls so you can see trends, not just a snapshot. Revenue going up is great. Revenue that peaked two years ago and has been declining since is a very different story, and one year of numbers will not show you that.

    When you get the P&Ls, do not accept them at face value. Look at the expense ratios. Most RV parks run expenses at 35% to 50% of gross revenue. If the seller’s numbers show expenses at 25%, something is being left out. Rebuilding the NOI from the actual financials is non-negotiable, and I covered exactly why in The $312,000 Mistake: What Happens When a Buyer Accepts the Seller’s NOI Without Rebuilding It.

    2. Trailing 12 months of bank statements

    P&Ls can be manipulated, intentionally or not. Bank statements cannot. Matching the deposits in the bank statements to the revenue on the P&L is one of the most important steps in your RV park due diligence checklist and one of the most commonly skipped.

    If the revenue on the P&L does not match what hit the bank account, you have a problem. Either revenue is being overstated on the P&L, some revenue is being run through a personal account and should not be counted as business income, or there are timing issues that need to be explained. Any of these scenarios changes your valuation.

    3. Current rent roll and occupancy data

    Ask for a current rent roll showing every occupied site, the rate being charged, the length of stay, and whether the guest is short term or long term. This one document tells you more about the real health of the business than almost anything else on your RV park due diligence checklist.

    Pay close attention to the mix of short term versus long term tenants. Long term tenants at below-market rates can inflate occupancy numbers while actually suppressing revenue potential and NOI. I covered why this matters in detail in Long-Term RV Guests Are Taking Over: 5 Ways It Breaks Your Books.

    4. Utility infrastructure inspection

    This is the item most first-time buyers underestimate on their RV park due diligence checklist, and it is often the most expensive surprise after closing. Electrical pedestals, water systems, sewer lines, and septic tanks are all costly to repair or replace and none of them show up on a P&L.

    Hire a licensed electrician to inspect the pedestals and panel capacity. Get the septic system pumped and inspected. Have the water system pressure-tested. If the park is on a well, get a water quality test and a yield test. The age and condition of the utility infrastructure will tell you a lot about what you are really buying and what capital you will need in years one through three. For more on what to look for, read What to Look for in RV Park Utility Infrastructure.

    5. Permits, zoning, and licenses

    A complete RV park due diligence checklist always includes a full review of permits and zoning. You need to confirm the park is legally permitted to operate at its current size and capacity, that all required business licenses are current, and that the zoning allows for continued RV park use. Do not accept the sellers statements as fact, verify these yourself.

    This matters more than most buyers realize. If a park was expanded without permits, or if a portion of the revenue comes from structures that are not permitted, you could be buying a liability. Ask for copies of all permits, certificates of occupancy for any structures on the property, and the current zoning classification. Then verify them yourself with the county.

    6. Environmental review

    No RV park due diligence checklist is complete without at least a Phase 1 environmental assessment. This is especially important if the property has any history of fuel storage, dry cleaning, or industrial use on or near the site. Environmental contamination can make a property essentially unsellable and the cleanup costs can be enormous.

    A Phase 1 is a relatively low-cost document review and site inspection by an environmental professional. If it flags anything, you move to a Phase 2, which involves actual soil and water testing. Do not skip this step to save money on due diligence.

    7. Online reputation and booking platform analysis

    The online reputation of the park is a financial asset and your RV park due diligence checklist should treat it that way. Pull all the reviews on Google, Campendium, The Dyrt, and any OTA platforms the park uses. Look at the trends. Are reviews getting better or worse over the past 12 months? What are guests consistently complaining about?

    Also look at OTA dependency. If 60% or more of bookings come through a single platform like Hipcamp or Campspot, you are buying a business with a single point of failure in its revenue stream. A platform policy change or commission increase can materially impact your income overnight. I wrote about this in The Real Cost of Online Travel Agent OTA Dependency.

    8. Deferred maintenance assessment

    Walk every inch of the property with a contractor or property inspector and document every deferred maintenance item you find. Roads, landscaping, signage, bathhouses, laundry facilities, fencing, and any structures on the property all need to be evaluated.

    Deferred maintenance is one of the most common ways a seller artificially inflates NOI. If they have not been spending money on upkeep, expenses look lower than they really are. The RV park due diligence checklist should include a line-item estimate for bringing everything up to standard, and that cost should factor directly into your offer price or your post-close capital reserve. For more on budgeting for these costs, read RV Park Capital Expenditures: 3 Budgeting Mistakes That Wreck New Owners in Year One.

    9. Title search and survey

    A clean title search confirms there are no liens, encumbrances, easements, or ownership disputes attached to the property. A survey confirms the boundaries match what you think you are buying. Both of these are standard in any real estate transaction but they are especially important in rural properties where boundary disputes and easement issues are more common.

    Make sure your title insurance covers any issues that come up and do not waive the survey even if the seller pushes back on the cost. You need to know exactly what land you are acquiring.

    10. Seller interview and transition plan

    The last item on your RV park due diligence checklist is one that many buyers overlook entirely: a structured conversation with the seller about operations. Who are the key vendors? Are there any verbal agreements with tenants not reflected in writing? What does the seller know about the property that is not in any document? You won’t know the very important answer to this one, unless you ask.

    Ask for a transition period where the seller is available to answer questions after closing. Even 30 to 60 days of email access to the previous owner can save you from costly surprises in your first months of operation. The SCORE Small Business Association also has free resources on business acquisition transitions that are worth reviewing before you sit down with a seller.

    How to use this checklist

    The RV park due diligence checklist above is most effective when you start working through it as soon as you are under contract, not in the last week of your due diligence period. Give yourself time to actually act on what you find. If something comes up in week one, you have time to negotiate a price reduction, request a repair credit, or walk away cleanly. If it comes up in the final days, you are under pressure and that is exactly where buyers make bad decisions.

    If you want help working through the financial side of your due diligence, including rebuilding NOI, stress-testing occupancy (what happens if it suddenly drops by 20%?), and building a model that reflects what you are actually buying, that is exactly what I do. A full acquisition underwrite starts at $750 and often can be turned around in 24 hours. Reach out at PVIFinancial.com and let’s make sure you know what you are buying before you sign.

    If you want the full picture, my book From Offer to Operation: The Complete RV Park Investor’s Guide includes a comprehensive 60-item due diligence checklist that covers every category in detail, from financials and infrastructure to legal, environmental, and operational items. It is the most complete RV park due diligence checklist I know of in one place, and it is built for buyers who want to walk into every deal fully prepared.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • RV Park Cash Flow Management: 7 Strategies That Stop Your Park from Sinking in the Off Season

    RV Park Cash Flow Management: 7 Strategies That Stop Your Park from Sinking in the Off Season

    RV park cash flow management is the skill most new owners do not think about until they are staring at a near-empty bank account in February wondering where all the summer money went. The good news is it is not complicated once you have a system. The bad news is almost nobody teaches you the system when you close. The owners who master RV park cash flow management are the ones who are never caught off guard, no matter what the calendar looks like.

    This post gives you that system, step by step, so you can stop guessing and start managing your money the way the numbers actually work in this business.

    Here is that system, seven strategies that keep your cash flow working for you all year:

    1. Know your baseline number before the season starts

    RV park cash flow management starts with one number: your monthly fixed cost floor. This is what it costs you to keep the lights on, the staff paid, the insurance current, and the debt serviced regardless of how many guests are in the park.

    Here is how to find it:

    Add up every expense that hits every single month no matter what. Mortgage or debt service, insurance, utilities on common areas, any salaried staff, software subscriptions, and any loan payments. Do not include variable expenses yet, just the fixed ones.

    That number is your floor. Every month your revenue needs to clear that number or you are dipping into reserves. Write it down and put it somewhere you see it every week. It is the most important number in your business.

    2. Build a 12 month cash flow map in January

    Sit down in January, before your season ramps up, and map out every single month of the year. For each month write down:

    • Expected revenue based on prior year occupancy
    • Fixed expenses
    • Variable expenses you know are coming, maintenance cycles, seasonal staff, marketing pushes
    • Any big one-time costs, equipment, capital improvements, permit renewals

    Now look at where the gaps are. Most parks will show three to four months where expenses exceed revenue. Those months are not surprises, they are scheduled. Once you can see them on paper you can plan for them instead of reacting to them.

    This map does not have to be fancy. A simple spreadsheet with 12 columns, one per month, and rows for each income and expense category is all you need. If you want to see what a clean version of this looks like, How to Do Your Monthly Financial Review: A Step by Step Guide for RV Park Owners is a good starting point.

    3. Open a dedicated cash flow reserve account

    This is the single most impactful thing you can do for RV park cash flow management and most owners skip it entirely.

    Open a separate bank account, not your operating account, and call it your Cash Flow Reserve. Every month during peak season transfer a fixed amount into it. The amount depends on your gap months but a good starting target is enough to cover two to three months of your fixed cost floor.

    Here is the rule: that account is only for covering shortfalls during slow months. It is not for equipment purchases, not for improvements, not for anything else. It is your seasonal buffer and it needs to be off limits for everything except its one job.

    If you are not sure how much to set aside, take your total slow season shortfall from your 12 month map and divide it by the number of peak months you have. That is your monthly transfer amount.

    4. Pay your slow season bills with your peak season revenue

    This sounds obvious but most owners do not actually do it systematically. RV park cash flow management works best when you think of your peak season revenue as covering the whole year, not just the months it comes in.

    Here is a simple way to think about it. If you know November through February will cost you $15,000 more than you bring in across those four months, then your summer needs to generate that $15,000 on top of covering summer expenses. That means your summer pricing, occupancy targets, and ancillary revenue need to account for the slow season too.

    When you set your rates for the season, back into them from your annual number, not just your summer number. Most owners price for summer and hope for the best in winter. Owners who are good at RV park cash flow management price for the whole year.

    5. Create a 90 day rolling cash flow forecast

    Your 12 month map is your big picture plan. Your 90 day rolling forecast is your operational tool.

    Every month update a simple three month look ahead. Take your actual bank balance today, add expected revenue for the next 90 days based on reservations and historical occupancy, subtract every known expense in that window, and see what your ending balance looks like.

    If the ending balance is below your fixed cost floor you have a problem coming and you have 90 days to address it. That might mean a promotional push to fill shoulder season inventory, deferring a non-urgent expense, or drawing from your reserve account.

    The 90 day forecast is where RV park cash flow management goes from theory to action. Do this on the first of every month without fail. It takes about 30 minutes once you have the habit and it will never let a cash crisis sneak up on you again. For more on what to review every month read The Monthly Financial Review Every RV Park Owner Should Be Doing But Almost Nobody Does.

    6. Track revenue per available site every single week

    Most owners track total revenue. Smart RV park cash flow management tracks revenue per available site, or RevPAS, because it tells you whether your pricing and occupancy are actually working together.

    Here is how to calculate it:

    Take your total revenue for the week and divide it by the number of sites you have available multiplied by 7 days. That gives you your RevPAS for the week.

    If your RevPAS is dropping it means either your occupancy is falling, your rates are too low, or both. If it is climbing you are doing something right and you want to know what so you can keep doing it.

    Track this number weekly during peak season and monthly during slow season. Put it in a simple log next to your cash flow forecast. Over time it becomes one of the most useful signals you have for understanding whether your revenue engine is healthy. I wrote more about this metric in The Three Numbers That Expose Every Problem in Your RV Park Before It Costs You Money.

    For industry benchmarking on occupancy and revenue data, RV Industry Association is a good resource.

    7. Do a monthly cash flow check in, not just a bank balance check

    Checking your bank balance is not RV park cash flow management. It is a snapshot of one moment in time and it tells you almost nothing about what is coming.

    A real cash flow check in takes about 20 minutes once a month and covers four things:

    First, compare actual revenue to what you projected for the month. Were you above or below and why?

    Second, compare actual expenses to what you projected. Were there any surprises and are they one-time or recurring?

    Third, update your 90 day rolling forecast with the new actuals.

    Fourth, check your reserve account balance against your projected slow season needs. Are you on track or do you need to adjust your transfer amount?

    That is it. Four questions, 20 minutes, once a month. If you do nothing else from this post, do this. It is the foundation of solid RV park cash flow management and it will tell you everything you need to know about the financial health of your park before a problem becomes a crisis.

    If you want help setting up your cash flow system, building your 12 month map, or doing a monthly review alongside someone who has done this with real parks, that is exactly what I do. Reach out at PVIFinancial.com and let’s get your numbers working for you.

    ~Wendi | Fractional CFO | PVIFinancial.com

  • 5 Financial Warning Signs Your RV Park Won’t Survive the RV Park market slowdown.

    5 Financial Warning Signs Your RV Park Won’t Survive the RV Park market slowdown.

    The RV park market slowdown was not on anyone’s radar during the boom years. If you got into parks between 2020 and 2025 you probably heard some version of this pitch: the industry is exploding, demand is up, new campers are flooding in, this is the best time to buy. And that was true. The industry grew at over 8% annually during that stretch. Occupancy was strong, rates were rising, and parks that were barely functional were still generating solid returns because the tide was lifting everything

    That tide has leveled off. Industry projections now point to near-zero growth through 2030, with some forecasts showing a slight revenue decline over that period. That does not mean RV parks are a bad investment. It means the era where a mediocre operation could hide behind a rising market is over. If your park is going to perform well in a flat market, it has to be built to perform, not just to exist.

    This post is about what that actually means for your financials, and the specific things I look at when I am evaluating whether a park is positioned to hold its ground or slowly erode in a maturing market. Here is what we are going to be looking at:

    What a RV Park Market Slowdown Actually Means for Your NOI

    In a growth market, you can count on some level of natural rate and occupancy increase year over year even if you do nothing. Demand is outrunning supply, so guests come to you. In a flat market, that tailwind disappears. Your NOI does not grow unless you make it grow, and your expenses will almost certainly keep climbing regardless of what revenue does.

    Utilities, insurance, labor, property taxes, and maintenance costs do not plateau just because the market does. If your revenue is flat and your expenses are rising 3 to 5 percent per year, your NOI is shrinking. A shrinking NOI means a shrinking valuation. This can happen slowly enough that you do not notice it until you are sitting across from a buyer or a lender and wondering why the number is lower than you expected.

    The parks that hold their value in a flat market are the ones where the operator is actively managing the spread between revenue and expenses, not just running the park and hoping the numbers work out at year end.

    The Metrics That Matter More Now Than They Did in 2021

    When the market was growing, occupancy was the headline number. If your park was full, you were fine. In a maturing market, occupancy is still important but it is not sufficient on its own. Here are the metrics I focus on with clients when we are trying to understand whether a park is truly healthy or just appears healthy.

    Revenue per available site, or RevPAS, tells you how much income you are generating from each site on average across the entire season, including empty nights. A park with 70% occupancy and a strong RevPAS is in a different position than a park with 70% occupancy and a weak one, usually because of rate, ancillary income, or both. If you are not tracking RevPAS you are missing a key layer of the story.

    Expense ratio is your total operating expenses divided by total revenue. In a well-run park this typically runs between 50 and 65 percent. If you are above 70 percent, your margins are thin and any revenue softness hits you hard. If you do not know your expense ratio off the top of your head, that is the first thing to calculate.

    Operating cash flow, separate from your accounting profit, tells you how much actual cash the business is generating after all operating expenses and debt service. Parks can look profitable on a P&L and still be cash-flow negative because of debt structure, deferred maintenance that is now hitting, or working capital gaps. In a flat market, cash flow discipline is everything.

    Where Operators Lose Ground Without Realizing It

    The most common pattern I see in a slowing market is what I call the quiet squeeze. Revenue holds roughly flat. The operator feels okay because nothing is obviously wrong. But expenses creep up, deferred maintenance starts accumulating, a rate increase gets skipped because it feels risky, and three years later the NOI is meaningfully lower than it was even though the park looks the same from the outside.

    The quiet squeeze is dangerous because it is gradual. You do not feel it the way you would feel a sudden drop in occupancy. You feel it when you go to refinance and the appraisal comes in lower than you expected. You feel it when a buyer makes an offer based on your actual current NOI and it is not the number you had in your head.

    The antidote is a monthly financial review that actually looks at trends, not just snapshots. I want to see revenue month over month, expense categories month over month, and NOI quarter over quarter for at least the last two years. Trends tell you things that a single month never will.

    The Operational Moves That Protect You in a Flat Market

    Surviving a plateau is not about dramatic reinvention. It is about getting very intentional about the levers you control. Here is where I focus with clients who are trying to protect their position in a maturing market.

    Rate discipline matters more than it ever did. If you have not raised rates in two years, your real revenue is declining when you factor in inflation. Even a 5 to 8 percent annual increase on new reservations keeps you moving in the right direction without shocking your regulars.

    Ancillary revenue becomes a meaningful line item. In a boom market you did not need it. In a flat market, income from storage, laundry, firewood, propane, on-site activities, or cabin rentals can be the difference between an NOI that grows and one that stagnates. These revenue streams also tend to carry high margins because your fixed costs are already covered by site revenue.

    Expense management has to be active, not passive. I review every major expense category with my clients quarterly, looking specifically for costs that have crept up without a corresponding increase in value. Insurance is a frequent culprit. So are utility costs that could be partially billed back to guests. So is software that was added during the busy years and never evaluated for ROI.

    Capital expenditure planning becomes critical. Deferred maintenance is the silent killer of NOI in a flat market. Every year you skip a repair or replacement that needs to happen, you are borrowing from your future self. When it finally comes due, it hits the P&L all at once, and it is never at a convenient time. I help clients build a rolling 3-year capital expenditure forecast so they can see what is coming and plan for it rather than react to it.

    What This Means for Your Financial Reporting

    If your books are currently set up to track revenue and expenses at a basic level and spit out a P&L once a month, that was probably sufficient when the market was doing the heavy lifting. It is not sufficient now.

    In a flat market, you need financial reporting that shows you trends over time, breaks out revenue by type and site category, tracks your key metrics monthly, and gives you enough visibility to make decisions before problems become emergencies. That is not complicated to build, but it does require intentional setup. If you are not sure whether your current reporting is giving you what you need, that is worth finding out sooner rather than later.

    The parks that will do well through this plateau are not necessarily the ones with the best locations or the newest amenities. They are the ones with operators who are paying attention and managing with intention. That starts with your numbers.

    Read this next: The Monthly Financial Review Every RV Park Owner Should Be Doing (But Almost Nobody Does)


    I cover what healthy RV park financials look like at every stage of ownership in ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49). Available at wendipvifinancial.gumroad.com/l/kqmyb and on Amazon under my name, Wendi Rook.

  • Long-Term RV Guests Are Taking Over: 5 Ways It Breaks Your Books

    Long-Term RV Guests Are Taking Over: 5 Ways It Breaks Your Books

    Long-term RV guests are changing the financial model at parks across the country. Parks that used to run almost entirely on weekend campers and short transient stays are watching their long-term population grow. Some of it is workforce housing demand, data center construction crews, traveling nurses, remote workers who found a cheap and flexible way to live. Some of it is intentional, operators who decided consistent monthly income sounded better than the weekend hustle. Either way, if your guest mix is shifting, your books need to shift with it. Most of the time they do not, and that is where the problems start.

    This post is about what actually changes on the financial side when long-term stays become a significant part of your revenue, and what you need to have in place to manage it correctly.

    Transient vs. Long-Term RV Guests: Two Completely Different Revenue Models

    When you are running primarily on transient guests, your revenue is high-frequency and variable. Someone books for two nights, pays at reservation or check-in, and leaves. Your cash comes in fast, your receivables are essentially zero, and your books reflect a stream of small completed transactions. The financial management is relatively simple.

    Long-term stays work differently. A guest who stays 30, 60, or 90 days may pay weekly or monthly. They may have a standing balance. They may be on a payment plan you set up informally because they seemed trustworthy. If you have multiple long-term guests on different billing schedules, you now have accounts receivable, and most small park operators have no system for managing that. They are tracking it in their head or on a whiteboard, and it is only a matter of time before something falls through the cracks.

    The first thing I ask when a park owner tells me they have shifted toward long-term guests is: how are you billing them and how are you tracking what they owe? The answer tells me almost everything I need to know about the health of their books.

    Income Classification Changes, and It Matters

    This is one of the most overlooked issues in the shift to long-term stays, and it has real tax and legal implications. In most states, short-term stays under 30 days are subject to transient occupancy tax, or TOT, sometimes called lodging tax or bed tax. Long-term stays, typically defined as 30 days or more, are often exempt from that tax. But the line is not always clean, and the rules vary by state and even by county.

    If you are collecting TOT on long-term guests who legally do not owe it, you are overcharging your guests and creating a liability. If you are not collecting it on guests who actually do owe it because you assumed they were long-term, you have a compliance problem. Either way, if your books are not tracking stay length and income type separately, you cannot even audit yourself to find out which situation you are in.

    Your chart of accounts needs to reflect this. I set up separate income categories for transient site revenue, long-term site revenue, and any other ancillary income. That separation is not busywork. It is what lets you run a tax report at the end of the quarter and know exactly what you collected, what was taxable, and what was not.

    Cash Flow Patterns Are Completely Different

    Here is something that surprises a lot of operators when they first make the shift. Long-term stays can feel more stable because you know someone is there for 60 days. But your actual cash flow timing gets more complicated, not less.

    With transient guests, money comes in constantly. With long-term guests, money comes in on billing cycles, and if a guest is a week late on their monthly payment, you feel it. If you have six long-term guests and two of them pay late, your bank account looks very different than your occupancy number suggests. I have seen parks with 80% occupancy show negative cash flow in a given month entirely because of timing issues on long-term collections.

    This is why your monthly financial review needs to include an accounts receivable aging report, not just a P&L. You need to know, as of today, who owes you money and how old that balance is. Seven days past due is a reminder call. Thirty days past due is a formal notice. Sixty days past due is a policy decision. None of that happens consistently without a system.

    What Your Lease or Rental Agreement Needs to Say

    Long-term guests are not just guests, they may have legal tenant rights depending on your state. Some states have very specific laws about how long someone can stay before they acquire tenant protections, including the right to a formal eviction process rather than just being asked to leave. I am not an attorney and you should absolutely talk to one if you are moving into extended-stay territory, but I can tell you from a financial standpoint that you need a written agreement with every long-term guest, without exception.

    That agreement should specify the rate, the billing cycle, what happens when payment is late, and the terms under which the stay can be ended. It protects you legally, yes, but it also protects your cash flow. When a guest knows the late fee is real and the process is documented, they pay differently than when they think it is casual.

    From a bookkeeping standpoint, every long-term guest should have their own ledger in your system. I do not care if you are using QuickBooks, a property management system, or a spreadsheet you built yourself. You need a place where you can see every transaction for that guest, what they were charged, what they paid, and what they owe. That is the minimum.

    The Revenue Mix Ratio to Watch

    Once you have your income properly categorized, you can start looking at your revenue mix as a strategic metric. What percentage of your total site revenue is coming from long-term guests versus transient? There is no universally right answer, but there are tradeoffs at every point on the spectrum.

    Heavy transient means high flexibility on rates and higher potential revenue per night, but more volatility and more operational intensity. Heavy long-term means more predictable cash flow and lower operational overhead, but less pricing power and potential legal complexity. Most operators I work with who have found a balance they like land somewhere in the 30 to 50 percent long-term range, enough to stabilize cash flow through slow seasons without giving up the rate upside on peak weekends.

    Know your number. Track it monthly. And make sure your books are set up to give it to you without you having to dig.

    Read this next: The Real Cost of Online Travel Agent (OTA) Dependency


    I cover revenue mix, income classification, and how to set up your chart of accounts for RV park operations in ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49). Available at wendipvifinancial.gumroad.com/l/kqmyb and on Amazon under my name, Wendi Rook.

  • Your RV Park Nightly Rate ($25/Night?) Is Quietly Destroying Your Park Value

    Your RV Park Nightly Rate ($25/Night?) Is Quietly Destroying Your Park Value

    Your RV park nightly rate is one of the most powerful and most underestimated levers in your entire business. Your RV park nightly rate is quietly determining what your park is worth, and most operators never see it coming until they’re sitting across from a buyer. I am going to say something that is going to sting a little. If you are charging $25 or $30 a night when the market around you supports $50 or $55, you are not just leaving money on the table every single night. You are also actively lowering the appraised value of your park. Not because anything is wrong with it, not because your occupancy is bad, not because your guests are unhappy. Simply because your nightly rate is the engine that drives your NOI, and your NOI is what determines what your park is worth to a buyer or a lender.

    Most park owners do not realize this connection until they are already in a transaction. I want you to understand it now, while you still have time to do something about it. This is what we will review:

    How Your RV Park Nightly Rate Directly Affects Your Park Value

    Unlike residential real estate, which is valued based on comparable sales, commercial properties like RV parks are valued on income. Specifically, on a metric called net operating income, or NOI. NOI is your total revenue minus your operating expenses, before debt service and depreciation. A buyer or appraiser takes that number and divides it by a cap rate, which is a market-derived percentage that reflects the risk and return profile of the asset, to arrive at value.

    The formula looks like this: Value = NOI divided by Cap Rate.

    So if your park generates $120,000 in NOI and the market cap rate for parks like yours is 10%, your park is worth $1.2 million. That is the math. Simple, direct, and completely tied to your income.

    Now here is where your nightly rate comes in. Every dollar you add to your average daily rate, across every occupied site, every night of the season, flows almost entirely to the bottom line. Your fixed costs do not change. Your mortgage does not change. Your labor does not change much. So rate increases have an outsized impact on NOI, which means they have an outsized impact on value.

    Most owners set their RV park nightly rate based on what they charged last year or what the park down the road charges, neither of which is a pricing strategy.

    What Below-Market Rates Are Actually Costing You

    Let me show you a real example of how this plays out. Say you have a 50-site park running at 70% occupancy for 200 nights a year. That is 7,000 occupied site nights per season. If you are charging $30 a night, your gross site revenue is $210,000. If the market around you supports $50 a night, your gross site revenue should be $350,000. That is a $140,000 difference in revenue, most of which becomes NOI.

    At a 10% cap rate, that $140,000 difference in NOI translates to $1.4 million in lost value. Same park. Same sites. Same guests. Just a different number on your rate board.

    I see this constantly with mom-and-pop parks that have been owned by the same family for years. The owner knows every guest by name, has not raised rates in a decade because it feels wrong, and genuinely has no idea that they have been shrinking their own net worth year after year. I am not criticizing that loyalty. I am saying the financial consequence of it is something every owner deserves to understand.

    Bringing your RV park nightly rate to market is the single highest return improvement available to most below-market parks.

    How to Find Your Gap

    Pull your average nightly rate right now. If you do not know it off the top of your head, that is the first problem, and I will come back to that. Go to Google and look up three to five comparable parks within 30 to 50 miles of you. Check their websites, check their Campspot or Hipcamp listings, check their Google profile. Write down what they are charging for a standard RV site on a weeknight and on a weekend.

    Now compare that to what you are charging. If there is a $10 gap, that is meaningful. If there is a $20 or $25 gap, you have a valuation problem sitting right there in plain sight.

    The parks you are comparing yourself to are not necessarily better than yours. They may just have an owner who did the math.

    What Your Books Should Be Tracking

    This is where the financial management piece comes in, and it is where I spend a lot of time with clients. Your average daily rate, or ADR, should be a line item on your monthly financial dashboard. Not just total revenue. Not just occupancy percentage. ADR specifically, broken out by site type if you have multiple categories.

    When you track ADR monthly, you can see trends. You can see if you are actually capturing rate increases you have implemented or if discounting and last-minute deals are eroding them. You can compare your ADR month over month and year over year. And when you sit down with a lender or a buyer, you can show them a park that is managed with intention, not just one that happens to generate income.

    If your bookkeeping is not giving you this number every month, that is a gap worth closing.

    A Word on Raising Rates

    You do not have to do this overnight, and I would not recommend it. Guests who have been coming to your park for years deserve some consideration. But there is a middle path between staying flat forever and shocking your regulars with a 40% jump. Phase your RV park nightly rate increase over two seasons rather than implementing it all at once.

    Many operators raise rates 8 to 12 percent annually on new reservations while grandfathering existing long-term guests on a slower schedule. Some parks introduce a new site category, upgraded electric, better location, improved pad, at a higher rate point, which lets the market absorb the increase without it feeling like a blanket hit to everyone.

    The bottom line is that your RV park nightly rate is not just a pricing decision. It is a financial decision that affects your NOI, your cap rate, and your asset value every single day.

    The strategy matters less than the intention. Start tracking your rate. Know your gap. Make a plan. Your future self, and your future sale price, will thank you.

    Read this next: What happens to your cap rate when you raise rates the wrong way


    I cover cap rates, NOI, and how park valuation actually works in ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49). Available at wendipvifinancial.gumroad.com/l/kqmyb and on Amazon under my name, Wendi Rook.

  • You Bought at the Peak: 4 Things Your RV Park Financials Need to Show Right Now

    You Bought at the Peak: 4 Things Your RV Park Financials Need to Show Right Now

    Your RV park financials need to tell a clear, accurate story right now, especially if you bought between 2020 and 2022 at peak prices. That is just the reality. Occupancy was record high, interest rates were low, and sellers knew exactly what they had. You probably paid a multiple that made sense at the time, and maybe it still does. But the market has shifted. Debt costs are higher, operating expenses have climbed, and the post-pandemic camping surge has normalized. If your financials are not telling a clear, accurate story right now, you are sitting on a risk you may not fully see yet.

    This is not doom and gloom. It is a call to get eyes on your numbers before someone else does it for you, whether that is a lender, a partner, or a buyer.

    Here is what I look for when I work with park owners who acquired during the boom years.

    Your NOI needs to be real, not optimistic.

    A lot of operators track revenue well but get loose on the expense side. They forget to include a management fee even if they self-manage, they skip reserves for capital expenditures, and they leave out one-time costs that are actually recurring. If your NOI looks healthy on paper but you are always scrambling for cash, those two things are telling you something.

    Here is what a clean NOI calculation actually includes. Total site revenue plus ancillary income, minus every operating expense including a management fee of 8 to 10 percent of revenue even if you manage it yourself, minus a capital expenditure reserve of at least 3 to 5 percent of revenue, minus property taxes, insurance, utilities, payroll, marketing, software, and any other recurring cost of running the park. What is left is your real NOI. Not the number that makes the park look good. The number that tells you the truth.

    Why does this matter so much right now? Because if you ever need to refinance, bring in a partner, or sell, that NOI number is what drives your valuation. A buyer or lender will reconstruct it themselves using your actual documents. If your version and their version are significantly different, the deal either falls apart or reprices against you. Better to know your real number now than to find out at the closing table.

    Your debt service coverage ratio needs room.

    If you financed at peak prices with rates that have since risen, your DSCR may be tighter than it looks on the surface. Lenders want to see at least 1.25, and most prefer closer to 1.35 or higher. If you are sitting at 1.10 or below, you need to know that now and have a plan before your next refinance conversation.

    Let me explain how DSCR works so you can calculate yours right now. Take your real NOI, the clean number we just talked about, and divide it by your annual debt service, which is your total principal and interest payments for the year. If your NOI is $180,000 and your annual debt service is $150,000, your DSCR is 1.20. That is below what most lenders want to see and it leaves you very little cushion if revenue softens or expenses spike.

    If your DSCR is tight, you have a few levers. You can raise rates to increase NOI. You can cut expenses that are not generating value. You can add revenue through ancillary income or shoulder season capture. Or you can refinance into a longer amortization to reduce your annual debt service, though that costs you more over time. None of these are simple, but knowing your number is the first step to making a plan.

    Your revenue mix matters more than it used to.

    During the boom, parks could run on transient weekend traffic and still hit their numbers. That window is narrowing. I look at what percentage of revenue is coming from long-term stays, from shoulder season, and from ancillary income. If you are still 90 percent dependent on peak-season transient guests, your income is more fragile than your P&L suggests.

    A healthy revenue mix in a maturing market looks something like this. Peak season transient at 60 to 70 percent of total revenue. Shoulder season at 15 to 20 percent. Long-term and extended stay at 10 to 20 percent. Ancillary income, storage, laundry, propane, cabin rentals, at 5 to 15 percent. Those percentages will vary by market and park type, but the point is diversification. No single revenue stream should be carrying the entire financial model.

    If you do not know your revenue mix right now, pull your last 12 months of site revenue and break it out by month and by guest type. That one exercise will tell you more about your financial vulnerability than almost anything else you could look at.

    Your books need to be audit-ready, not catch-up ready; your RV park financials need to shine.

    If you had to hand your financials to a lender or buyer today, would they hold up? Commingled accounts, missing receipts, cash transactions that were never recorded, these are the things that kill deals and tank valuations. The time to clean them up is not when you need something. It is now, while you have runway.

    Audit-ready books mean a few specific things. Your business accounts are completely separate from your personal accounts with no commingling. Every transaction has documentation, a receipt, an invoice, a bank record that ties back to what is in your books. Your revenue matches your bank deposits and your tax returns within a reasonable margin that can be explained. Your expense categories are consistent and logical so that someone who has never seen your books can understand what they are looking at.

    If your books are not there yet, the path forward is not complicated but it does take time. Start with a bank reconciliation going back at least 12 months. Get every transaction categorized correctly. Make sure your chart of accounts reflects the actual revenue and expense categories of your business. If you are too far behind to do it yourself, hire someone to get you current. The cost of a cleanup is almost always less than the cost of a bad refinance or a repriced deal.

    Buying at the peak was not a mistake. Not knowing where you stand right now is the actual risk. Get your financials in front of someone who understands this asset class and can tell you the truth.

    If you want a second set of eyes on your numbers, that is exactly what I do.

    Read this next: What a Lender Actually Looks at Before Approving an RV Park Loan


    I cover the financial side of RV park ownership in depth in my book, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49), including how to read your own financials the way a lender does. Available at wendipvifinancial.gumroad.com/l/kqmyb and on Amazon under my name, Wendi Rook.

  • RV Park Cash Flow: The 1 Month Your Books Lie to You and How to Catch It

    RV Park Cash Flow: The 1 Month Your Books Lie to You and How to Catch It

    RV park cash flow is most dangerous not in your slowest month, but in the month right after your peak season ends. Your bank account still looks healthy from the summer, your books are showing strong revenue, and everything feels like it is working.

    That feeling is the lie.

    What your books are not showing you in that moment is what is coming. The slow months ahead. The fixed costs that continue regardless of occupancy. The capital contributions you may have skipped during the rush of peak season. The reserve account that looks adequate right now and will not look adequate in February.

    The month your books lie to you the most is the first month after your best month. And if you do not know how to read what is actually there, you will make decisions based on a financial picture that is already out of date.

    Why peak season creates RV park cash flow and a false sense of security

    During peak season, cash comes in fast. Reservations are full, sites are occupied, the camp store is moving product, and the bank balance climbs in a way that feels like confirmation that everything is working. For most RV park owners, this is the best the business looks all year.

    The problem is that peak season revenue has to do more than cover peak season expenses. It has to carry the entire operation through the months when revenue drops but costs do not. Insurance does not pause in November. Loan payments do not skip January. Utilities do not stop because the sites are empty. Any year-round staff you have does not work for free in the off-season.

    If you spent peak season looking at a healthy bank balance and making decisions based on that number without modeling what the next six months actually require, you have set yourself up for a cash flow problem that will feel sudden but was entirely predictable.

    What your books are not telling you in October

    Your October P&L will show strong revenue if your peak season ran through September. It may show your best month of the year. On paper everything looks fine.

    What it will not show you is that November through March will generate a fraction of that revenue while carrying most of the same fixed costs. It will not show you the gap between what you have in the bank today and what you need in the bank to get through the slow season comfortably. It will not show you whether your reserve account is adequately funded for the capital event that always seems to happen at the worst possible time.

    A P&L is a rearview mirror. It tells you what happened. It does not tell you what is coming. And in a seasonal business, what is coming matters more than what just happened.

    The number your books should be showing you but probably are not

    The financial metric that matters most at the end of peak season is not your revenue. It is your forward cash position. Specifically, what does your cash balance need to be right now to cover every fixed expense, every debt obligation, every planned capital contribution, and a reasonable buffer for the unexpected through the end of your slow season?

    That number is not on your P&L. It is not on your balance sheet in a form most owners look at. It lives in a forward cash flow projection that most RV park owners have never built, which means most RV park owners are making post-peak-season decisions without knowing whether they can actually afford to make them.

    This is how owners end up dipping into reserve accounts to cover operating expenses in January. It is how capital projects that should have been funded from peak season revenue get deferred again. It is how a business that had a great summer ends up in a cash squeeze by spring that nobody saw coming, even though it was visible six months earlier to anyone who was looking at the right numbers.

    The seasonal cash flow trap

    Here is the pattern I see repeatedly. Owner has a strong peak season. Bank balance looks good in October. Owner makes a discretionary purchase, takes a distribution, or simply stops making reserve contributions because the account already looks healthy. November arrives. Revenue drops by 60 to 70 percent. Fixed costs continue. The bank balance starts declining faster than expected. By February the owner is managing cash flow week to week instead of month to month.

    The summer was not the problem. The October decision made without a forward cash flow model was the problem.

    Peak season revenue is not profit until you have confirmed it covers everything the slow season requires. Before that confirmation, it is a float.

    What to do differently

    Before peak season ends, build a month by month cash flow projection through the end of your slow season. Use your actual fixed cost structure. Use conservative revenue estimates for the slow months based on prior year performance, not hope. Calculate the cash reserve you need to carry the operation through comfortably and compare it to what you actually have.

    If the number works, great. Make informed decisions from that position. If the number does not work, you need to know that in October, not in February when the options are limited and the pressure is real.

    Your books will tell you what happened last month. Your job is to use that information to understand what is coming next. In a seasonal business those are two completely different conversations, and only one of them actually protects you.

    The month your books lie to you the most is the one where everything looks fine. That is the month to look harder.


    Read this next: The Monthly Financial Review Every RV Park Owner Should Be Doing But Almost Nobody Does


    If you want the full framework for buying, managing, and understanding the financials on an RV park acquisition, I wrote ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49) specifically for investors who want to get this right. You can get it direct here: https://wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

  • RV Park Maintenance Costs: 3 Expensive Surprises Nobody Warns You About at Closing

    RV Park Maintenance Costs: 3 Expensive Surprises Nobody Warns You About at Closing

    RV park maintenance costs are the silent killer that nobody warns you about at closing. You got the deed, the title commitment, the closing statement, maybe an equipment list.

    What you almost certainly did not get was a real maintenance schedule. Not a real one. Not a document that told you when the septic was last pumped, when the electrical pedestals were last inspected, when the roof on the bathhouse was last replaced, or when the water lines were last pressure tested.

    And if nobody gave it to you, there is a good chance nobody had it. Which means right now you are operating infrastructure you cannot fully see, on a timeline you do not know, with capital exposure you have not quantified.

    That gap is costing you money. It may be about to cost you a lot more.

    The problem with inherited infrastructure; RV Park Maintenance costs.

    Every physical system in your park has a lifespan. Septic systems. Electrical distribution. Water lines. Roofs. Roads. HVAC in any structures. Pump stations. Every one of them is somewhere on a curve between brand new and end of life, and when you closed you inherited whatever point on that curve each system happened to be at.

    The previous owner knew where those systems were, at least roughly, because they had been living with them for years. They knew the septic had been giving them trouble. They knew the main electrical panel needed attention. They knew the bathhouse roof had been patched twice and was probably good for one more season. They knew all of that and almost none of it made it into the seller disclosure or the deal package.

    You are now the owner of systems you did not build, cannot fully see, and have no documented history on. And the clock on all of them is running whether you are tracking it or not.

    What deferred maintenance actually looks like from the inside

    It does not usually announce itself. It accumulates quietly while you are focused on occupancy, reservations, guest experience, and the hundred other things that demand attention in the first year of ownership.

    A pedestal that trips occasionally. A water pressure issue in the back loop that guests mention in reviews but has not caused a real problem yet. A bathhouse drain that runs slow. A road section that gets soft after heavy rain. None of these feel urgent. Each one is telling you something.

    What they are telling you is that the system behind them is closer to failure than it was when you bought the park. And because you have no maintenance history, you do not know how close.

    The failure, when it comes, is never at a convenient time. It is peak season weekend. It is a holiday Friday. It is the morning your highest-rated guest of the year is checking in. And instead of running your park you are managing an emergency repair at emergency pricing, writing apology notes, and watching your review score take a hit that will outlast the repair by two years.

    The cost nobody puts in the pro forma

    Emergency repairs cost more than scheduled maintenance. That is not an opinion, it is a procurement reality. A contractor called on a Saturday morning during peak season charges differently than one scheduled six weeks in advance on a Tuesday. Parts sourced overnight cost more than parts ordered on a normal timeline. And the revenue lost while a system is down, sites that cannot be occupied, amenities that cannot be used, is a cost that never shows up anywhere but your bank account.

    Owners who run preventive maintenance schedules spend less over time than owners who run reactively. The systems last longer. The repairs are smaller. The emergencies are fewer. And the capital reserve contributions that fund planned replacements are predictable rather than catastrophic.

    The math on preventive maintenance is not complicated. The reason more owners do not do it is that building the schedule requires work that nobody handed you at closing.

    What a real maintenance schedule actually covers

    A functional preventive maintenance program for an RV park is not complicated but it has to be comprehensive. It covers every major system on a documented inspection and service interval.

    Septic systems should be inspected and pumped on a schedule appropriate to capacity and usage, not when they start showing signs of distress. Electrical systems, including individual site pedestals and receptacles, should be inspected annually by a qualified electrician. Water lines and pressure systems need regular testing. Roofs on all structures need annual inspection and documented repair history. Roads need seasonal assessment and grading before problems develop into guest complaints.

    Beyond the major systems, the smaller items add up. Playground equipment inspections. Laundry machine service. HVAC filter schedules. Fire extinguisher certifications. Generator testing if you have backup power. Each of these is minor in isolation. Together they represent the operational foundation that keeps a park running smoothly and keeps guests writing the kinds of reviews that fill sites.

    Building the schedule you should have received at closing

    If you do not have a maintenance schedule, build one now. Start with a physical walkthrough of every system on the property and document what you find. Age, condition, last known service date if you can determine it, and your best estimate of remaining useful life. That inventory is your starting point.

    From that inventory, build a twelve-month maintenance calendar with specific tasks, assigned responsibility, and estimated cost. Put it in a format someone other than you can follow, because eventually someone other than you will need to.

    Then fund it. Maintenance tasks that are on a schedule and budgeted for get done. Maintenance tasks that depend on available cash when the time comes get deferred. Deferred maintenance is how you end up in the same position as the seller you bought from, operating infrastructure on borrowed time and hoping nothing fails before you can get to it.

    The seller did not give you a maintenance schedule at closing. That is not an excuse to operate without one. It is the first problem you need to solve.


    Read this next: The Expense Category Most RV Park Owners Forget to Budget For Until It Wrecks Their First Year


    If you want the full framework for buying, managing, and understanding the financials on an RV park acquisition, I wrote ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49) specifically for investors who want to get this right. You can get it direct here: https://wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

  • RV Park Deal Analysis: 5 Red Flags That Made Me Walk Away From a $1.6M Park Yesterday

    RV Park Deal Analysis: 5 Red Flags That Made Me Walk Away From a $1.6M Park Yesterday

    RV park deal analysis is where deals die, and yesterday one died on my desk. I sat down with a package on a 23-site park asking $1.6 million and walked away. I am not going to name the park or the location. What I am going to do is walk you through exactly what I saw, because if you are actively looking at deals right now there is a reasonable chance something with the same fingerprints is sitting in your inbox.

    I walked away. Here is why.

    The financials on this RV park deal analysis told two different stories

    The package came with what I can only describe as a handmade P&L. Not a formal financial statement. Not something pulled from accounting software. A document that someone built themselves, by hand, to present the park in the best possible light.

    The numbers showed roughly $85,000 in NOI across each of the prior four years, then a jump to $199,000 this year. The seller presented that $199,000 as the number to underwrite to.

    When NOI more than doubles in a single year after four years of flat performance, that is not a trend. That is a question. And it is a question that needs a verifiable answer before you go any further.

    Any serious RV park deal analysis has to start by asking why that number moved so dramatically and whether the answer holds up under scrutiny.

    When I adjusted the numbers, the story changed immediately

    I rebuilt the NOI from what they gave me. Before I even got to management fees or real estate taxes, I had already adjusted the presented $199,000 down to $152,000. That $47,000 gap came from the numbers themselves, before accounting for the expenses that were missing entirely from the P&L.

    Then I added back a market-rate management fee. It was not in the expenses anywhere, because the current owner self-manages. On a park this size that is a real cost that belongs in any honest underwriting.

    Then I looked for real estate taxes. They were not there either. On a $1.6 million asking price asset. That is not an oversight. That is a choice someone made when they built the P&L, and it is the kind of choice that inflates NOI in exactly the way that benefits a seller and misleads a buyer.

    By the time I added both of those back, the number I was actually underwriting to looked very different from $199,000.

    That gap between the seller’s number and the real number is what the RV park deal analysis is supposed to find, and it is why the work matters before you ever make an offer.

    November and December were estimated

    For the last two months of the year, the P&L showed revenue listed as estimated based on an average of the previous ten months.

    That is not how financials work. You do not average your way to a year-end number and present it as performance data in a deal package. November and December for most RV parks are slow months. Averaging them against peak season revenue inflates the annual figure in exactly the way that benefits a seller and misleads a buyer.

    If the actual numbers were not available, the right answer is to say so. Substituting an estimate that produces a better annual total is not a financial statement. It is a guess dressed up as one.

    This is exactly the kind of red flag that a thorough RV park deal analysis is designed to surface, and exactly why you should never accept a seller’s financial package at face value without rebuilding the numbers yourself.

    The operations were, generously speaking, informal

    This park took reservations by phone only. No online booking. No property management software. No digital payment processing.

    Rent collection happened when people paid by cash or check. Sometimes the maintenance guy collected it. I say sometimes because the maintenance guy was also living in the one cabin on the property for free in exchange for his services, and his involvement in collections appeared to be, based on what was presented to me, somewhat optional.

    There was no formal rent collection system. There were no documented processes. There was no way to verify that the revenue reported on the handmade P&L bore any reliable relationship to the cash that actually changed hands at this park over the past year.

    When you cannot trace revenue to a reservation system, a payment processor, or a bank deposit pattern that holds up to scrutiny, you do not have verified financials. You have a number someone wrote down.

    The occupancy told a different story than the revenue

    Last month, six of the park’s 23 sites were unoccupied. That is a 26 percent vacancy rate on a small park that is supposedly generating dramatically higher NOI than it has in any of the prior four years. And that vacancy was not the outlier. The occupancy at this park swings wildly, which means the presented number is not a stabilized figure. It is a peak number being presented as if it were normal.

    When I see occupancy swings that dramatic on a small site count with no formal reservation or payment infrastructure, I want to know what is actually driving the revenue spike this year. I did not get a satisfying answer.

    The upside pitch did not hold up either

    The seller’s position on the $1.6 million asking price leaned heavily on an adjacent acre with ten lots already laid out for expansion. The implication was that the development potential justified the premium over what the current financials would support.

    I understand the logic. I do not agree with the math.

    Undeveloped lots are not revenue. They are a capital project with an unknown timeline, unknown permitting risk, unknown infrastructure cost, and zero guarantee of the occupancy needed to justify the investment once built. You do not pay for lots that do not yet exist as if they were producing income. You price the asset on what it actually generates today and negotiate separately for any legitimate upside that can be quantified.

    At $1.6 million, with a presented NOI that I adjusted down significantly before even accounting for missing expenses, with no formal reservation or payment system, with estimated months in the annual financials, and with a maintenance situation I cannot adequately describe with professional language, this deal was not priced on reality. It was priced on a story.

    Why I am telling you this

    Because someone is going to look at this deal when doing their RV park deal analysis. Maybe they already have. And if they have not done this kind of line-by-line analysis on the financials, they might see a park with a big NOI number, an expansion opportunity, and a motivated seller and think they found something.

    They did not find something. They found a deal that needs to be priced correctly before it becomes a good investment, and right now it is not priced correctly.

    This is the work. Not just reviewing the numbers the seller gave you, but pressure testing every line, identifying what is missing, understanding what the operations actually look like behind the headline number, and being willing to walk away when the story does not hold up.

    I walked away yesterday. I will look at the next one tomorrow.


    Read this next: The Seller’s Pro Forma Is Not Your Pro Forma


    If you want the full framework for buying, managing, and understanding the financials on an RV park acquisition, I wrote ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49) specifically for investors who want to get this right. You can get it direct here: https://wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

  • RV Park Rate Increase Mistakes: 3 Costly Ways Operators Destroy Their Own Cap Rate

    RV Park Rate Increase Mistakes: 3 Costly Ways Operators Destroy Their Own Cap Rate

    An RV park rate increase is one of the most powerful levers available to an owner. Done correctly it can add hundreds of thousands in asset value without a single capital improvement. Done incorrectly it can erode occupancy, damage your reviews, and quietly destroy the NOI you were trying to build

    Most of the conversation in RV park investing circles focuses on the upside of raising rates. What gets less attention is how raising rates the wrong way can hurt you, and how the damage often does not show up where you expect it to.

    First, understand what your cap rate actually reflects

    Your cap rate is a function of your NOI and your asset value. When NOI goes up, asset value goes up at the same multiple. When NOI goes down, so does your value. This is the math that makes rate increases so compelling on paper.

    A $10 per night rate increase across 60 sites at 150 occupied nights per year is $90,000 in additional gross revenue. At a 40 percent expense ratio that flows to roughly $54,000 in additional NOI. At an 8 cap that represents approximately $675,000 in added asset value. The math is real and it is why rate discipline gets talked about so much.

    What the math does not capture is what happens to occupancy when you raise rates faster than your market, your product, or your guest base can absorb.

    The occupancy leak nobody models

    When you raise rates aggressively, some guests leave. That is not always a bad thing. If you are replacing budget-conscious guests with higher-rate guests who book more consistently and leave better reviews, the trade is often worth making.

    The problem is when the guests who leave are not replaced. When you raise rates 30 percent in year one at a park that has not had a capital improvement in a decade, you are asking guests to pay premium rates for a product that does not yet support them. Some will pay it once. Most will not come back. And the reviews they leave on their way out will affect your ability to fill those sites at the new rate for longer than you expect.

    Occupancy loss at higher rates can easily produce lower total revenue than the original rate at full occupancy. A 20 percent occupancy drop on a rate increase that was supposed to add $90,000 in revenue can turn into a net revenue loss before you have processed what happened.

    The review problem compounds the math problem

    Here is where it gets worse. Occupancy loss from a rate increase that outpaced your product shows up in your financials within a season. The review damage shows up on Google and Campendium immediately and stays there for years.

    Guests who feel they overpaid for an experience do not write neutral reviews. They write detailed ones. And a pattern of reviews citing value concerns at a park with recently increased rates is one of the most difficult reputational holes to climb out of, because every future guest reading those reviews is doing the math before they book.

    Recovering review scores after a mispriced rate increase typically takes two to three years of consistent operational improvement and deliberate review management. During that window you are competing for bookings at a disadvantage against parks with cleaner profiles, which puts downward pressure on the occupancy you need to justify the rate.

    What a Smart RV Park Rate Increase Actually Looks Like

    Rate increases should be tied to something. A capital improvement that genuinely upgrades the guest experience. A market analysis showing your rates are materially below comparable parks in your trade area. A site-type differentiation strategy that prices premium pull-throughs and waterfront sites differently from standard back-ins.

    Incremental increases that the market can absorb are almost always more effective than large single-year jumps. A five to eight percent annual increase compounded over three years gets you to roughly the same place as a 25 percent increase in year one, with a fraction of the occupancy risk and none of the review exposure.

    Segment before you increase. Not every site in your park supports the same rate. Raising rates uniformly across all site types leaves money on the table at your best sites and creates value objections at your weakest ones. Know what each site type is worth and price accordingly.

    And time it right. Rate increases implemented mid-season on existing reservations create guest friction that is disproportionate to the revenue gained. Increase rates at the start of a new booking season when guests are making fresh decisions, not in the middle of a stay they already budgeted for.

    The cap rate conversation buyers need to have

    If you are buying a park where the pitch includes significant rate upside, pressure test that assumption before you underwrite to it. Ask what comparable parks in the trade area are actually charging. Ask what the current guest mix looks like and whether that mix will support a rate increase or simply leave when one happens. Ask what capital improvements are planned and on what timeline, because rate increases without product improvement are a short-term revenue strategy with long-term consequences.

    The upside is real. The risk is real too. The buyers who execute rate strategies well are the ones who tied the increase to something the guest could see, feel, and justify paying for.

    Rate increases that outpace the product do not build asset value. They borrow against it.


    Read this next: Should You Raise Rates After Acquiring an RV Park? How to Know When the Numbers Support It


    If you want the full framework for buying, managing, and understanding the financials on an RV park acquisition, I wrote ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49) specifically for investors who want to get this right. You can get it direct here: https://wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

  • Fractional CFO Confession: The Market Took My Retirement Once. Here Is What I Built With $500 Instead.

    Fractional CFO Confession: The Market Took My Retirement Once. Here Is What I Built With $500 Instead.

    I became a fractional CFO because I lived the version of business ownership where the stakes were real and the margin for error was thin. In 2008 I watched my 401K shrink in real time like a lot of people did. And I decided I was not going to let that happen again

    Not out of anger, just out of clarity. If I was going to have financial security in retirement, I was going to have to build it myself. I was starting over from scratch this time. There was no 401K left.

    So I started a business. With an idea, a goal, and about $500.

    The Part Nobody Talks About

    I did not quit my job and leap. I am not that person. I stayed in my medical field career for two full years while I built the business on the side, because I was scared and because I was practical and because I knew that burning the boats sounds romantic until you have bills due.

    When I finally did go full time it was because the business had earned it, not because I was feeling brave. That distinction matters. Courage is not the absence of fear. It is making the next right move anyway, carefully, with your eyes open.

    For a while it worked. I got focused, I got traction, and the business grew.

    And then the market shifted and someone else’s decisions nearly destroyed everything I had built.

    When Outside Forces Burn It Down

    The first time it happened I watched competition flood the online space and commoditize what I had spent years building. The model that had been working stopped working almost overnight. I had to pivot, rebuild, and find a new angle fast.

    I did. And it worked again.

    Then it happened a second time. Bigger money entered my space, the wholesale model I had built dried up, and I was staring at another moment of having to decide whether to walk away or go all in on something different.

    I went all in. This time on a full retail strategy.

    What I know now is that watching your business get undercut by forces completely outside your control is one of the most clarifying experiences an entrepreneur can have. You find out very quickly what you are actually made of. And you find out that starting over is not the same as failing. Starting over with the knowledge you have accumulated is actually a significant advantage if you are willing to use it.

    The Decision That Changed Everything

    Somewhere in the middle of all of that, after watching two near-destructions and knowing it could happen again at any time, I made a decision that turned out to be one of the smartest things I have ever done.

    I started spreading my risk.

    I became a private money lender. First trust deeds secured by real estate, earning consistent returns on capital I had worked hard to accumulate, backed by an asset I could evaluate and understand. It was not glamorous. It was intentional. I was not going to have all of my financial security sitting in one place ever again.

    That lending business has now been running for over eight years. I have deployed more than four million dollars. And it generates legacy income that does not depend on me showing up and grinding every day.

    How It Ended and What Came Next

    The retail business I rebuilt after that second near-destruction became the strongest version of what I had been building all along. I exited with over 500 accounts and a multi-million dollar outcome.

    I am not telling you that to impress you. I am telling you because in 2008 I was sitting with a depleted retirement account, and I knew the only person I could rely on to get it back was myself. And I chose myself. Scared, practical, deliberate, one move at a time.

    What a Fractional CFO Actually Builds On

    What I do now is help other entrepreneurs build the financial clarity and discipline that makes outcomes like that possible. The Fractional CFO work, the underwriting, the bookkeeping, all of it comes from having lived the version of business ownership where the stakes were real and the margin for error was thin.

    I know what it feels like to not have visibility into your numbers and to be making decisions anyway. I know what it costs. And I know what changes when you finally have a clear picture of where you actually stand.

    That is what PVI Financial is built on. Not theory. Not a credential on a wall. Thirty years of real decisions with real money on the line.

    If you are building something and you want a financial partner who has actually been where you are, I would love to talk. The free financial health check at pvifinancial.com is the best place to start.

    And if you have not grabbed a copy of my book yet, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49), it covers the full financial and operational management framework for running your park with the discipline it deserves. You can get it direct here: wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

    Read this next: “What is a Fractional CFO and Does Your Small Business Need One”

  • Why I Work With Entrepreneurs and Not Corporations

    Why I Work With Entrepreneurs and Not Corporations

    I have been asked more than once why I do not go after corporate clients. The contracts are bigger, the engagements are longer, and the budgets are not a conversation. On paper it makes sense.

    But I have never been drawn to it and I have finally stopped pretending I might be.

    I work with entrepreneurs. Specifically, I work with experienced entrepreneurs, people who have already built something real, who know what they are doing, and who mostly just need clarity and a nudge in the right direction. That is my sweet spot and I am not apologetic about it.

    The Corporate World Moves Too Slow for Me

    I have nothing against large organizations. But the reality of working inside or alongside them is that decisions require committees, changes require approvals, and by the time everyone has weighed in the moment has often passed. There are too many rules, too many layers, and too much energy spent managing the process instead of solving the problem.

    Entrepreneurs do not work that way. When an entrepreneur sees something clearly they move. When you show them a number that changes the picture they act on it. That responsiveness is not just more efficient, it is more satisfying. I can see the impact of the work in real time because the person I am working with is actually using it.

    I Am a Cheerleader, But Only for People Who Are Already Running

    I genuinely love cheering people on. I believe in what my clients are building and I bring real energy to that. But I am not a coach for someone who is still deciding whether to start. I am not the right fit for someone who needs to be convinced to take action.

    The people I do my best work with are already in motion. They have built something, they are running it, and they have hit a point where the financial side of the business needs to catch up with everything else. They are not looking for someone to hold their hand. They are looking for someone to look at the numbers with them, tell them the truth, and help them figure out the next right move.

    That person I can help enormously. And that work energizes me in a way that nothing else does.

    Why Experience Changes Everything

    There is a particular kind of conversation I love. It happens when I am working with someone who has been in business long enough to know what they do not know. They are not defensive about the gaps. They are not pretending the problems are not there. They just want clarity, and they are ready to do something with it once they have it.

    That is a very different conversation than the one where someone needs to be convinced that their financials matter or that the number they think they have is not the number they actually have. I am not the right person for that convincing. I would rather spend that energy going deep with someone who is already a believer and just needs the right information to make their next move confidently.

    What That Looks Like in Practice

    The clients I work with best are the ones who come to me with real businesses, real decisions, and real stakes. Maybe they are about to acquire something and they need the numbers underwritten before they commit. Maybe cash flow has gotten tight in a way they cannot fully explain and they need someone to find it. Maybe they have been running on instinct for years and they are finally ready to have a real financial dashboard that tells them what is actually happening every month.

    In every one of those situations what I am really doing is giving someone who is already capable the visibility they need to perform at the level they are already capable of. That is the work. And honestly it never gets old.

    If you are an experienced business owner who is ready for that kind of clarity, the free financial health check at pvifinancial.com is the best place to start. Fill out the form and let’s talk.

    And if you have not grabbed a copy of my book yet, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49), it covers the full financial and operational management framework for running your park with the discipline it deserves. You can get it direct here: wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

    Read this next: “What is a Fractional CFO and Does Your Small Business Need One”

  • CFO Help Without the CFO Price Tag.

    CFO Help Without the CFO Price Tag.

    CFO help is a lot easier to get and costs a lot less than you think.

    One of the most common things I hear from business owners is some version of this: “I know I need more financial help but I’m not ready for a big monthly commitment.” And I get it. Not every business is at the stage where a full retainer makes sense, and not every financial problem requires ongoing support to solve.

    That is exactly why I built out a full menu of project-based and ร  la carte CFO work – so you can get the CFO help you need. You can get high-level financial expertise for a specific problem, a specific decision, or a specific moment in your business, without signing up for anything ongoing.

    Here is what CFO help actually looks like.

    Business Financial Audit ($1,000 to $2,000)

    This is where a lot of owners start. If you have a nagging sense that something is off in your financials but you cannot put your finger on it, an audit gives you a clear picture of where you actually stand. What is working, what is not, where money is leaking, and what needs to be fixed. CFO help is the answer. It is a diagnosis before a prescription.

    Cash Flow Rescue Plan ($1,000 to $1,500)

    If cash flow is tight right now and you need a clear path forward, this is the engagement. I look at your current cash position, your upcoming obligations, and your revenue timeline, and I build you a concrete plan for stabilizing and improving your cash flow. Not theory. CFO help will give you clarity. An actual plan with specific actions.

    KPI Dashboard Build-Out ($2,000 to $3,000)

    If you are making decisions without real-time visibility into your numbers, a custom KPI dashboard changes that. I build it around your specific business, your specific revenue drivers, and the metrics that actually matter for how you operate. Once it is built, you have a tool you use every month.

    Financial Model Build ($1,500 to $15,000)

    For businesses planning a significant move, whether that is expansion, a new revenue stream, a construction project, or a major operational change, a financial model lets you stress-test the decision before you commit to it. The range reflects the complexity of what you are modeling. This is where CFO help can determine whether the project is a home-run or turn and run!

    New Construction ROI Model ($1,500 to $15,000)

    Specific to owners considering adding cabins, glamping units, amenity buildings, or other capital improvements. Before you spend the money, you need to know what the return looks like, how long the payback period is, and whether the project actually pencils at realistic occupancy and rate assumptions. I can answer those questions for you. I am CFO for a modular cabin company.

    Deal Screening / Deal Review ($500 to $750)

    If you are looking at an acquisition and you want a fast, experienced read on whether the numbers make sense before you go deeper, this is a one-time review. I look at the financials, flag the issues, and tell you what I see. CFO help for quick reviews starts at just $99. Fast, focused, and actionable.

    Acquisition Underwrite ($750 to $1,500)

    A full underwriting goes deeper than a screening. I build out the adjusted NOI, model the debt structure scenarios, identify the red flags, and give you a clear picture of what the deal actually looks like before you make an offer. This is the work that keeps you from overpaying or closing on a deal that looks better on paper than it performs in real life.

    Strategic Expense Recovery (Free Audit)

    This one surprises people. Most businesses are paying for things they do not need, have duplicate subscriptions, vendor relationships that have not been renegotiated in years, or expense categories that have crept up without anyone noticing. I find it. The audit is free because the savings speak for themselves.

    Hourly Advisory ($175 to $225/hour)

    Sometimes you just need an hour with someone who knows their numbers and can help you think through a decision clearly. No project scope, no deliverable. Just a focused conversation with a Fractional CFO who has actually built, run, and exited a business and deployed millions in real estate capital.

    And If You Are Ready for Ongoing Support

    If any of these conversations turns into something bigger, or if you realize what you actually need is consistent monthly visibility and strategy, that is what my Essential, Growth, and Strategic retainer tiers are built for. Starting at $1,500 a month, you get a real financial partner, not just a report.

    The right level of CFO help is whatever solves your actual problem.

    If you are not sure what that is, the free financial health check is the best place to start. Fill out the form at pvifinancial.com and let’s figure it out together.

    And if you have not grabbed a copy of my book yet, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49), it covers the full financial and operational management framework for running your park with the discipline it deserves. You can get it direct here: wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

    Read this next: “What is a Fractional CFO and Does Your Small Business Need One”

  • What a Lender Actually Looks at Before Approving an RV Park Loan

    What a Lender Actually Looks at Before Approving an RV Park Loan

    If you have ever tried to get a loan on an RV park and felt like the process was opaque, you are not imagining it. Commercial lending on outdoor hospitality assets is more specialized than a residential mortgage, and lenders are evaluating factors that are not always obvious from the outside. Understanding what they are actually looking for changes how you prepare, and how you show up to that conversation.

    The Property Has to Make Sense on Its Own

    The first thing a commercial lender evaluates is the property’s ability to service the debt from its own income. They are not primarily interested in your personal income or your net worth as a primary repayment source. They want to see that the park itself generates enough NOI to cover the debt payment with a reasonable cushion.

    That cushion is measured by the Debt Service Coverage Ratio, or DSCR. Most conventional commercial lenders want to see a DSCR of at least 1.25, meaning the property generates $1.25 in NOI for every $1.00 of annual debt service. Some SBA lenders will go to 1.15. Below that, the deal typically does not work regardless of how strong everything else looks.

    This is why NOI accuracy matters so much before you walk into a lending conversation. If your books are not clean, the lender cannot confidently calculate your DSCR, and an uncertain DSCR almost always gets discounted in your favor, not the lender’s.

    Your Financials Need to Be Verifiable

    Lenders do not take your word for income. They want to see at least two to three years of tax returns for the business, trailing twelve month profit and loss statements, bank statements that reconcile to your books, and in many cases a rent roll or occupancy history.

    If your books have been kept inconsistently, if you have been running personal expenses through the business, or if there are revenue streams that show up in your bank account but not in your P&L, those discrepancies become problems. The lender’s underwriter will find them, and when they do, it raises questions about the integrity of everything else in the file.

    Clean, consistent, well-organized financials do not just make you look professional. They reduce the friction in underwriting, shorten the timeline, and give the lender confidence that the income they are underwriting is real.

    The Property Itself Gets Scrutinized

    Beyond the financials, lenders look hard at the physical asset. Infrastructure condition matters because a lender does not want to finance a park that has a $200,000 utility replacement sitting in the near future. Environmental considerations matter, particularly for properties with on-site fuel storage, older septic systems, or adjacent land uses that create contamination risk.

    Market position matters too. A lender wants to understand who your guests are, how competitive your market is, and whether your occupancy is driven by genuine demand or by unsustainably low rates. A park with strong occupancy at market rates in an underserved area looks very different to a lender than a park with strong occupancy because it is the cheapest option in a crowded market.

    Your Personal Financial Profile Still Matters

    Commercial lending on a small park is not purely asset-based. The lender is also evaluating you as the operator. They want to see a personal financial statement, a reasonable personal credit profile, and evidence that you have the liquidity to support the business through lean periods.

    For SBA loans specifically, they will also look at your management experience. If you have never operated a hospitality business before, being able to show a management plan, an advisory team, or relevant transferable experience strengthens the file considerably.

    How to Prepare Before You Apply

    The best thing you can do before approaching a lender is build a clean, current financial package. That means up-to-date books, a trailing twelve month P&L, a current balance sheet, bank statements, and a clear narrative of the business that explains the numbers in plain language. If there are anomalies in your financials, a one-page explanation attached to your package is far better than letting the underwriter discover them without context.

    The owners who move through commercial lending the fastest are the ones who show up prepared. Not just with the numbers, but with the story the numbers tell. That is where having a Fractional CFO in your corner before you apply makes a real difference. I have relationships with RV Park lenders, and help get you pointed in the right direction.

    And if you have not grabbed a copy of my book yet, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49), it covers the full financial and operational management framework for running your park with the discipline it deserves. You can get it direct here: wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

  • How to Calculate Break-Even for Your RV Park (And Why It Changes Everything)

    How to Calculate Break-Even for Your RV Park (And Why It Changes Everything)


    Break-even is one of those terms that gets used a lot in business conversations but rarely gets defined precisely enough to be useful. Most people have a general sense of what it means. Fewer people know their actual break-even number, and almost nobody is tracking whether they have truly crossed it.

    For RV park owners, this matters more than it does in most businesses. Seasonal revenue, high fixed costs, and the gap between a strong summer and a slow winter make break-even awareness a genuine operational necessity, not just a finance concept.

    What Break-Even Actually Means

    Break-even is the point at which your total revenue equals your total expenses. Below it, you are losing money. Above it, you are generating profit. Simple in theory. Complicated in practice, because not all expenses behave the same way.

    Your fixed costs stay constant regardless of occupancy. Debt service, insurance, property taxes, management salaries, utilities with base minimums, and software subscriptions are examples. These bills arrive whether you have 10 rigs on property or 80.

    Your variable costs move with revenue. OTA commissions, credit card processing fees, cleaning supplies, and seasonal labor scale up when business is strong and down when it is slow.

    True break-even accounts for both. It is the revenue number at which your fixed costs are fully covered and your variable costs, scaled to that revenue level, are also covered. Everything above that number is profit.

    Why Seasonal Parks Have a Break-Even Problem

    A park that generates 70% of its annual revenue between Memorial Day and Labor Day is not operating at break-even in October. It is drawing down the cash reserves it built during peak season to cover fixed costs that do not stop just because the rigs do.

    This means a park can be profitable on an annual basis and still run dangerously low on cash in the off-season. The break-even question in outdoor hospitality is not just annual. It is monthly. You need to know which months you cover your costs from operations and which months you are living off of summer’s earnings.

    How to Calculate Your Break-Even

    Start with your total monthly fixed costs. Add those up and that number is your floor. Every month, no matter what, you need at least that much revenue coming in or you are going backward.

    From there, calculate your variable cost ratio. If your variable costs run at roughly 30% of revenue, then for every dollar you bring in, 70 cents is available to cover fixed costs and profit. Divide your total fixed costs by that 70 cents per dollar and you get your break-even revenue number.

    Run this calculation for each month of the year using your actual fixed cost schedule and your historical variable cost ratios. What you end up with is a monthly break-even map that tells you exactly where you are vulnerable and how much cushion your peak season needs to build.

    What to Do With the Number

    Once you know your monthly break-even, a few things become clear. You can see how much cash reserve you need to carry into the slow season to cover the months you will not break even from operations. You can set a minimum acceptable occupancy target for each month. And you can make smarter decisions about off-season rate strategy, because you know exactly what revenue you need to hit instead of guessing.

    The park owners who weather slow seasons without stress are almost always the ones who knew their break-even number going in and planned their cash position accordingly. The ones who get surprised are almost always the ones who never ran the math.

    If you want help building your break-even model, that is one of the first things I build with every new client. It is not complicated, but it is foundational, and having it changes how confidently you run your business.

    And if you have not grabbed a copy of my book yet, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49), it covers the full financial and operational management framework for running your park with the discipline it deserves. You can get it direct here: wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.

    Read this next: “Why Your RV Park’s Best Season Can Also Be Its Biggest Financial Risk”

  • The Monthly Financial Review Every RV Park Owner Should Be Doing (But Almost Nobody Does)

    The Monthly Financial Review Every RV Park Owner Should Be Doing (But Almost Nobody Does)

    Let me ask you something. When was the last time you sat down with your financials, not to pay bills, not to check your bank balance, but to actually review how your business performed last month against how you expected it to perform?

    If you are like most RV park owners the honest answer is either not recently or not ever in any structured way. You know roughly what came in. You know roughly what went out. You have a general sense of whether it was a good month or a slow one. But you do not have a formal monthly review process and you definitely do not have a document that shows you exactly where you are relative to your original projections.

    That gap is costing you. Not just in missed opportunities to catch problems early, but in the compounding cost of making operating decisions without accurate, current financial information.

    Here is the monthly financial review every RV park owner should be doing, what it covers, how long it takes, and why it is the single highest return use of one hour of your time every month.

    Why Monthly and Not Quarterly

    A lot of small business owners review their financials quarterly because that is what their accountant asks for. Quarterly is better than never but it is not enough for a seasonal hospitality business.

    In an RV park a single month can represent 20 to 30 percent of your annual revenue. A problem that surfaces in month one of peak season and is not caught until a quarterly review has already cost you two months of peak season performance before you even know it exists. By the time you identify it and course correct you may have lost half your peak season.

    Monthly review catches problems while they are still small. It also catches opportunities while they are still actionable. That is the whole point.

    Set a Standing Date and Keep It

    Pick one day every month and commit to it. The 10th works well for most operators because it gives you enough time after month end for your books to be closed and reconciled. Put it on your calendar as a recurring appointment and treat it like a meeting you cannot cancel.

    The review does not work if it only happens when you get around to it. It works because it happens every single month without fail, good months and slow months alike.

    What the Review Covers

    The monthly financial review has five components and in a well-run operation with clean books it takes 30 to 60 minutes start to finish.

    Revenue by stream versus prior month and prior year

    Start with the top line. What did the park generate in total revenue last month? How does that compare to the same month last year? How does it compare to your pro forma projection for that month?

    Then break it down by revenue stream. How did transient nightly revenue perform? Long-term tenant revenue? Cabin or glamping revenue if applicable? Utility recovery? Store and ancillary income?

    Every revenue stream has its own story. Transient nightly revenue down 12 percent from last year might mean a pricing issue, a marketing issue, a competitive issue, or a weather issue. You cannot know which one it is until you look at the individual line and ask the question. A blended revenue number tells you something happened but not what.

    Expenses versus budget and prior year

    Go through every expense category and compare it to your budget and to the same month last year. You are looking for two things: line items running significantly above budget and line items running suspiciously below budget.

    Above budget items need an explanation. Was it a one-time repair? A vendor price increase? A staffing overtime situation? Understanding why an expense is elevated tells you whether it is a problem to address or a normal variation to absorb.

    Below budget items need just as much attention. A maintenance line running 40 percent below budget in the middle of peak season almost always means maintenance is being deferred, not that the park suddenly got cheaper to maintain. Deferred maintenance is a future capital expense hiding in a current period variance.

    NOI versus pro forma

    After revenue and expenses, calculate your actual NOI for the month and compare it to what you projected in your original underwriting. This is the number that tells you whether the park is performing to the thesis you bought it on.

    If your actual NOI is consistently running below your pro forma projection you have a fundamental performance gap that needs to be understood and addressed. Is it a revenue problem? An expense problem? A mix problem? The monthly review is where you identify which one it is early enough to do something about it.

    Cash position and 30/60/90 day forecast

    After you have reviewed the income statement, look at your cash position. What is your current operating account balance? What is your capital reserve balance? What is your tax reserve balance?

    Then project forward 90 days. Based on your expected revenue and known upcoming expenses, what will your cash position look like at the end of month one, month two, and month three? Are there any months where cash gets tight? Any large expenses coming up that need to be planned for?

    This forward-looking piece is what separates a financial review from a financial autopsy. The autopsy tells you what happened. The forecast tells you what is coming so you can prepare for it rather than react to it.

    Key operating metrics

    Finish with your operating metrics. Occupancy rate for the month compared to prior year and pro forma. Average daily rate (ADR) compared to prior year and pro forma. Revenue per available site night. These three numbers together tell you more about the operational health of your park than any single line on the income statement.

    If occupancy is up but ADR is down you have a pricing opportunity. If ADR is up but occupancy is down you have a marketing or demand issue. If both are up but NOI is flat you have an expense problem. The metrics point you toward the question worth asking.

    What to Do With What You Find

    The monthly review is not just a reporting exercise. Every variance has a story and your job is to understand the story well enough to make a decision.

    Ahead of projection on revenue? Great. What drove it and can you replicate it next month? Behind on occupancy? Why, and what specific action are you taking to address it? Maintenance running above budget for the third month in a row? That is a pattern worth investigating before it becomes a capital surprise.

    Document your findings every month in a simple running log. What was the result, what was the variance, what is the explanation, and what if anything are you doing about it. That log becomes one of your most valuable operational documents over time. It shows you patterns, it informs your planning, and if you ever sell the park it demonstrates to buyers that the asset was actively managed by an owner who knew their numbers.

    The 30 to 60 Minute Investment

    If your books are clean, your chart of accounts is set up properly for an RV park, and your pro forma tracking document is current, this entire review takes 30 to 60 minutes. One hour a month on a multi-million dollar investment is not a burden. It is the minimum responsible stewardship of an asset that size.

    If the review consistently takes longer than that, the problem is usually the books. A chart of accounts that is not structured for RV park operations forces you to do manual translation every time you review your financials. A bookkeeper who is not familiar with outdoor hospitality produces reports that require interpretation rather than analysis. Both are fixable problems and fixing them pays dividends every single month going forward.

    If you want help setting up the monthly review process for your park, or want a fractional CFO to run it with you every month so you always have a clear picture of where you stand, reach out at pvifinancial.com. That is exactly what I do.
    And if you have not grabbed a copy of my book yet, ๐—™๐—ฟ๐—ผ๐—บ ๐—ข๐—ณ๐—ณ๐—ฒ๐—ฟ ๐˜๐—ผ ๐—ข๐—ฝ๐—ฒ๐—ฟ๐—ฎ๐˜๐—ถ๐—ผ๐—ป: ๐—ง๐—ต๐—ฒ ๐—–๐—ผ๐—บ๐—ฝ๐—น๐—ฒ๐˜๐—ฒ ๐—ฅ๐—ฉ ๐—ฃ๐—ฎ๐—ฟ๐—ธ ๐—œ๐—ป๐˜ƒ๐—ฒ๐˜€๐˜๐—ผ๐—ฟ’๐˜€ ๐—š๐˜‚๐—ถ๐—ฑ๐—ฒ ($49), it covers the full financial management framework including everything you need to run your park with the discipline it deserves.

    You can get it direct here: wendipvifinancial.gumroad.com/l/kqmyb, or Amazon has it too, just search author Wendi Rook.


    You might want to read this next: “Your bank balance is lying to you”

  • I Have Never Owned an RV Park. Here Is Why I Am the Person You Want Looking at Your Deal.

    I Have Never Owned an RV Park. Here Is Why I Am the Person You Want Looking at Your Deal.


    I get this question more than you might think. Sometimes it is asked directly. Sometimes I can just feel it hanging in the air when I am talking to a buyer or an owner for the first time.

    You have never owned an RV park. So why should I listen to you? Just the other day someone commented on one of my Facebook posts “why should we listen to you? What makes you special over all the other mentors out there teaching about RV parks?”

    It is a fair question and I want to answer it honestly, because I think the honest answer is actually more useful to you than the polished version.

    I am a real estate investor who has built and sold a seven figure real estate portfolio over the last 30 years. I am a private money lender who has put over $4 million into first trust deeds secured by real estate over the last 8 years. I bootstrapped a seven figure business from $500 and built it into something worth selling. And I am a Fractional CFO and bookkeeper who lives in business financials every single day. That combination of skills is exactly what you need when you are evaluating an RV park deal, and it is not a combination you find very often in one person

    Here is what I mean by that.

    The Investor Lens

    When I look at an RV park deal, I am not looking at it as a consultant who has read about investing. I am looking at it as someone who has personally been through the acquisition process, understands what it feels like to have real money on the line, and knows the difference between a deal that looks good on paper and a deal that actually holds up when you start pulling on the threads.

    I have walked away from deals that did not pencil. I have pushed through deals that had problems because the problems were quantifiable and the price reflected them. I have been the person sitting at the closing table wondering if I did enough diligence. That experience does not come from a textbook and it changes how you look at everything.

    The Lender Lens

    Eight years of lending on real estate has taught me something that most people on the buyer side never fully appreciate. The lender sees everything. Every deal that came across my desk as a private money lender came with a story the borrower was telling me about why it was a good investment. My job was to look past the story and evaluate the collateral, the numbers, and the risk.

    When you have spent years on the lender side of the table, you develop a very specific kind of skepticism about financial presentations. You learn to ask where a number came from before you accept it. You learn that the most important information in any deal package is often what is missing, not what is there. That skepticism is exactly what a buyer needs when they are evaluating a seller’s financials.

    I did not have to take somebody’s word for what a property was worth. I had to verify it independently, every single time, because my own money was on the line if I got it wrong. That discipline is built into how I approach every underwriting engagement I take on for a client.

    The CFO and Bookkeeper Lens

    This is the one people underestimate the most.

    I spend my professional life inside the financials of small businesses. I know what clean books look like and I know what messy books look like. I know the difference between a P&L that was prepared to accurately reflect the business and one that was prepared to tell a specific story to a specific audience. I know where expenses get buried, how revenue gets overstated, and which line items are the first places a seller cleans up before putting a park on the market.

    I also know what it takes to build the financial infrastructure to run a business properly after you close. Not just the acquisition, but the day-to-day systems, the reporting, the cash flow management, the bank account structure, the chart of accounts that actually gives you visibility into how the business is performing. Most buyers close on a park and then figure this part out as they go. The ones who have it in place from day one make better decisions faster and avoid the expensive lessons that come from flying blind in the first year of ownership.

    So Why Not Just Hire Someone Who Owns Parks?

    You can. There are operators out there with direct park ownership experience who offer consulting services. That experience is genuinely valuable, particularly on the operational side.

    But ownership experience alone does not make someone qualified to pressure test your financial assumptions, rebuild a seller’s NOI from the source documents, identify what is missing from a set of financials, or set up the bookkeeping infrastructure that turns your new acquisition into a manageable business. That work requires a specific financial skill set, and it is the skill set I have been building for over a decade across real estate, lending, and CFO work.

    I bring three lenses to every RV park deal I look at. The investor who understands what is at stake. The lender who has been trained to verify everything. And the CFO who knows what the numbers are supposed to look like and what to do when they do not.

    That combination is what I offer. And I think it is exactly what most buyers in this space are missing.

    If you are evaluating a park right now and want that combination working for you before you commit, reach out at pvifinancial.com.

    And if you have not already grabbed a copy of my book, From Offer to Operation: The Complete RV Park Investor’s Guide ($49), it is everything you want to know about how to evaluate, acquire, and run an RV park, plus a bonus report with 34 red flags to verify before you close so you are not buying someone else’s problem.

    You can get it direct here: https://wendipvifinancial.gumroad.com/l/kqmyb

    Or if you prefer Amazon has it too, just search author Wendi Rook.

    ~Wendi | Fractional CFO | PVIFinancial.com

    Read this next “The Two Line Items That Will Wreck Your First RV Park Deal”

  • Your Chart of Accounts Is Lying to You (And It Is Costing You More Than You Think)

    Your Chart of Accounts Is Lying to You (And It Is Costing You More Than You Think)

    Most RV park owners who are using QuickBooks have the same problem. They opened the software, picked the closest industry template, answered a few setup questions, and started categorizing transactions. The books are technically getting done. The bank reconciles every month. Their accountant is happy.

    And they have absolutely no idea what their business is actually telling them.

    The chart of accounts is the backbone of your entire bookkeeping system. It is the structure that determines how every dollar of income and every dollar of expense gets categorized, reported, and ultimately analyzed. Get it right and your financials become a management tool that tells you exactly where you are and what to do about it. Get it wrong and you have a document that satisfies your tax preparer and tells you almost nothing else.

    For RV parks specifically, getting it wrong is the default. Here is why, and what to do about it.

    The Generic Template Problem

    QuickBooks and most bookkeeping software offer industry templates when you set up a new company file. There is no RV park template. There is no outdoor hospitality template. So owners pick the closest thing, usually something in the general services or hospitality category, and start from there.

    The problem is that a generic hospitality chart of accounts was not designed around the revenue and expense structure of an RV park. It does not distinguish between your transient nightly revenue, your long-term monthly tenant revenue, your seasonal site revenue, and your cabin or glamping income. It lumps all of those into a single revenue line called something like “Sales” or “Service Revenue.”

    That single line number tells you that money came in. It tells you nothing about where it came from, which revenue stream is growing, which is shrinking, which is performing above your underwriting assumptions, and which is dragging the whole operation.

    For a business where the revenue mix is one of the most consequential variables in both operations and valuation, that is a significant blind spot.

    What a Proper RV Park Chart of Accounts Actually Looks Like

    A chart of accounts built specifically for an RV park breaks revenue down by stream so you can actually manage each one. At minimum, you want separate income accounts for transient nightly site revenue, weekly site revenue, monthly long-term tenant revenue, seasonal site revenue, cabin and glamping revenue if applicable, utility recovery income, camp store and retail sales, laundry and vending income, and any event or group booking revenue.

    Each of those lines tells a different story. Your transient nightly revenue tells you whether your rate and occupancy are moving in the right direction for short-term guests. Your long-term tenant revenue tells you whether your monthly base is stable or eroding. Your utility recovery income tells you whether your pass-through on electrical costs is covering what you are actually spending. None of that is visible if everything lives in one bucket called “Revenue.”

    The expense side needs the same level of specificity. Payroll should be broken down by function, management, maintenance, and guest services, not pooled into a single payroll line. Utilities should separate electricity, water, sewer, trash, and internet rather than combining them into one utilities expense. Maintenance should distinguish between routine maintenance, repairs, and capital improvements, because those three things are financially and tax-wise very different from each other.

    Why This Matters for More Than Just Reporting

    Clean, properly structured financials do three things beyond keeping your accountant satisfied.

    First, they make you a better operator. When you can see month over month that your transient nightly revenue is up 12 percent but your long-term tenant revenue is down because two sites turned over, you can make a deliberate decision about how to fill those sites rather than just watching the total revenue number and hoping for the best.

    Second, they protect you at resale. When you eventually sell the park, a sophisticated buyer or their CFO is going to request financials and rebuild the NOI from the source. If your books are structured so that every revenue stream and every meaningful expense category is clearly broken out, that process takes days instead of weeks and gives the buyer confidence in your numbers. That confidence translates into a smoother transaction and a stronger price. If your books are a mess of generic categories that require significant interpretation, buyers discount for the uncertainty.

    Third, they are what lenders actually want to see. If you ever refinance, apply for an SBA loan, or bring in a capital partner, your financials need to tell a clear story about the performance of the asset. A lender looking at a single revenue line and three or four expense buckets cannot underwrite your park accurately. A lender looking at a detailed, properly segmented set of financials can. That difference can be the difference between getting the terms you want and not getting the loan at all.

    The Fix Is Not Complicated, But It Has to Be Done Right

    Rebuilding a chart of accounts mid-stream in an existing QuickBooks file is not a weekend project, but it is also not as painful as it sounds when it is done by someone who knows what they are doing. The bigger issue is doing it right the first time, before you have 18 months of transactions categorized into a structure that does not serve you.

    If you are setting up books for a new acquisition, build the chart of accounts before you categorize a single transaction. If you are already operating and your books are on a generic template, the right time to fix it is now, before you need those financials to do something important.

    What I do at PVI Financial is set up bookkeeping systems specifically for RV park owners, with a chart of accounts built around how this asset class actually operates, not how a generic software template assumes it does. Whether you want someone to set it up and hand it back to you, or you want ongoing fractional CFO support to manage it month to month, the conversation starts at pvifinancial.com.
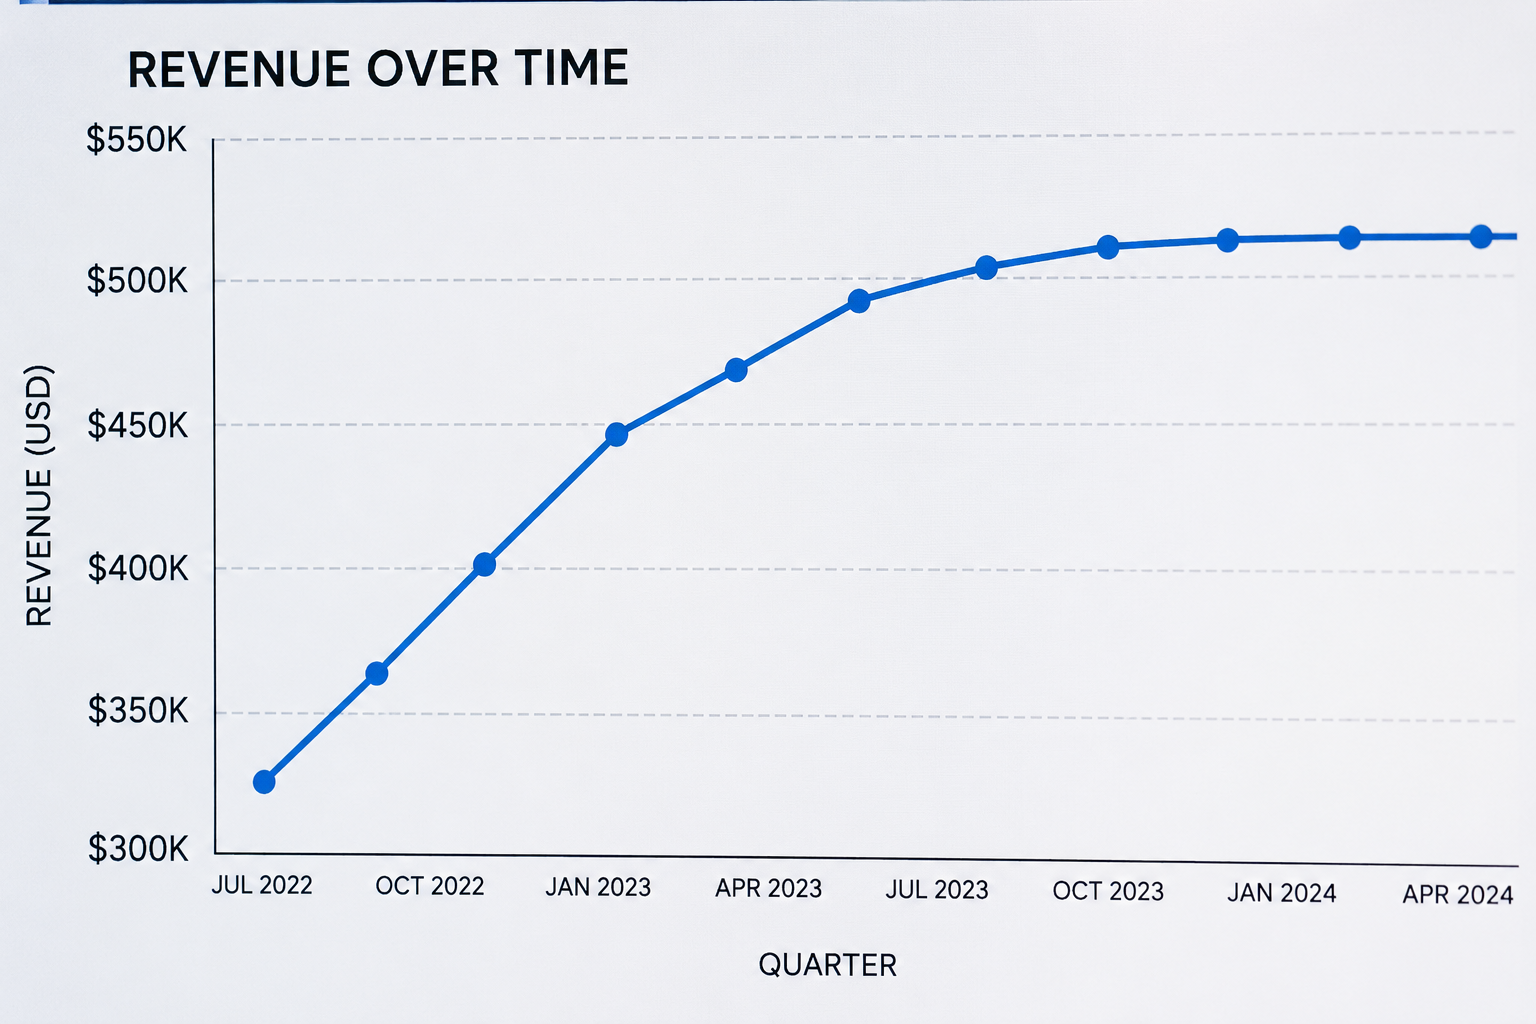
    And if you are still in the acquisition phase and want to understand what clean financials should look like before you buy a park, grab a copy of my book, From Offer to Operation: The Complete RV Park Investor’s Guide ($49). It covers the full picture from underwriting through operations, including a bonus report with 34 red flags to verify before you close so you are not buying someone else’s problem.

    You can get it direct here: https://wendipvifinancial.gumroad.com/l/kqmyb

    Or if you prefer Amazon has it too, just search author Wendi Rook.

    ~Wendi | Fractional CFO | PVIFinancial.com

    If you liked this, you might want to read this next “Your Bank Balance is Lying To You”

    Click here to Download my free guide, “The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer”

  • The Seller’s Pro Forma Is Not Your Pro Forma

    The Seller’s Pro Forma Is Not Your Pro Forma

    Every RV park listing comes with a pro forma. A clean one page summary showing gross revenue, expenses, NOI, and a cap rate that makes the deal look compelling. It is professionally formatted. The numbers add up. And it was built entirely to sell you the park.

    That is not your pro forma. That is the seller’s story.

    Here is what I mean by that.

    A pro forma is only as honest as the assumptions behind it. And the seller’s assumptions are always the most optimistic version of the truth. Not necessarily because anyone is lying. But because every single line item in that document was built from the seller’s cost structure, the seller’s relationships, the seller’s management style, and the seller’s years of accumulated advantages that will not transfer to you at closing.

    Let me show you what I mean.

    The seller self manages the park. No management fee in the expenses. Looks lean and efficient. But you are not moving to that park to work 60 hours a week. You need a manager. Add $40,000 to $60,000 in annual expenses that are nowhere on that pro forma.

    The seller has had the same insurance broker for 20 years. Grandfathered rate. Not available to new buyers. Your quote comes in $8,000 higher. Not on the pro forma.

    The seller’s maintenance guy has been coming out for half price for years because they are old friends. He retires when the seller does. Your maintenance costs double. Not on the pro forma.

    The seller has not put meaningful money back into the property in five years. No CapEx line item because nothing major has broken yet. But the electrical pedestals are aging, the bathhouse fixtures are worn, and the roads need grading. All of that is coming out of your pocket in year one. Not on the pro forma.

    By the time you rebuild the NOI honestly, adding real management costs, market rate expenses, normalized CapEx, and actual vacancy, that 8% cap rate on the flyer is often a 5% cap rate in reality. And at the asking price that is a completely different deal.

    So how do you build your own pro forma?

    This is the part most buyers skip because it feels complicated. It is not. It is methodical. Here is exactly how I do it.

    Step 1 โ€” Start with verified gross revenue.

    Do not use the number on the flyer. Ask for three years of bank statements and tax returns and build the revenue from actual deposits, not reported income. Look at each revenue stream separately. Site rentals, laundry, store sales, event income. Know which ones are recurring and which ones are one time. If the seller cannot provide bank statements that match the reported revenue that is a red flag before you even get to expenses.

    Step 2 โ€” Apply a real vacancy rate.

    Most pro formas use 5% vacancy or less. The reality for most parks is closer to 8 to 12% depending on seasonality and market. This is one variable that sellers almost universally get wrong in a pro forma.

    A seller’s pro forma is typically built on either current peak occupancy, historical best year occupancy, or a stabilized projection that assumes everything goes right. What it rarely accounts for is a realistic vacancy factor based on the actual seasonal patterns of that specific park in that specific market.

    Before you accept any revenue projection at face value, pull the monthly occupancy numbers for the last three years and build your own occupancy assumption from the bottom up. If the park runs at 90 percent in July and 20 percent in January, your annual average is not 55 percent and your cash flow model needs to reflect the monthly reality, not the annual average.

    A pro forma that ignores vacancy is not a financial model. It is a best case scenario dressed up as a projection.

    Step 3 โ€” Rebuild every expense line from scratch.

    Do not accept the seller’s expense numbers. Go line by line and ask yourself one question for each item. Is this what I would actually pay? Here is what to examine:

    Property taxes: Call the county assessor and confirm the current tax bill. Ask whether a sale would trigger a reassessment. In some states a sale resets the assessed value and your tax bill goes up significantly.

    Insurance: Get your own quote before you make an offer. Do not use the seller’s number.

    Management: If you are not self managing add 8 to 12% of gross revenue as a management fee regardless of whether it is in the current expenses. If you are self managing, add it anyway and then decide if the deal still works. Because someday you will not want to self manage and you need to know the park can support that cost.

    Maintenance: Industry standard is 5 to 8% of gross revenue for a well maintained park. If the seller is showing less than that ask why. If the park has deferred maintenance budget more.

    CapEx reserve: This is the one most buyers skip entirely. Every major system in an RV park has a finite lifespan. A healthy CapEx reserve is typically 3 to 5% of gross revenue set aside annually for future capital needs. If the seller has no CapEx in their expenses they have been withdrawing equity from the property and handing you the bill.

    Utilities: Get the actual utility bills for 24 months. Not the seller’s estimate. The actual bills.

    Payroll: Get the actual payroll records. Know who is on payroll, what they make, and whether any of them are family members being compensated below or above market.

    Step 4 โ€” Add your debt service.

    This is where most deals either work or fall apart. Take your actual financing terms, the real loan amount, the real interest rate, the real payment, and model it against the NOI you just rebuilt. Not the seller’s NOI. Yours. The debt service coverage ratio should be at least 1.25. I want to see 1.5 or above before I feel comfortable.

    Step 5 โ€” Model the seasonality.

    Build a 12 month cash flow projection, not just an annual total. Map revenue and expenses month by month. Identify your worst cash month. Make sure you have enough reserves to cover it. A park that generates 80% of its revenue in three months needs a financial cushion that most buyers do not account for until they are sitting in month 9 with an empty park and a full expense load.

    Step 6 โ€” Stress test the assumptions.

    Run the numbers at 10% lower revenue than your projection. Run them at 10% higher expenses. If the deal still works under those scenarios you have a margin of safety. If it only works when everything goes exactly as planned, it is too thin.

    When you have done all six of those steps you have your pro forma. Not the seller’s version. Yours. Built from real numbers, real costs, and assumptions that reflect what this park will actually look like under your ownership.

    That is the number that tells you what the deal is worth. And that is the only number that matters when you are deciding whether to make an offer.

    The seller’s pro forma tells you what they want you to believe. Your pro forma tells you what you are actually buying.

    If you want to go deeper on what to look for before you close; (and to protect yourself) you might want to pickup a copy of my $49 book “From Offer to Operations: The Complete RV Park Investor’s Guide”. This guide covers exactly this and a lot more, and it could save you from a very expensive mistake!

    You can get it direct here: https://wendipvifinancial.gumroad.com/l/kqmyb

    Or if you prefer Amazon has it too, just search author Wendi Rook.

    ~Wendi | Fractional CFO | PVIFinancial.com

    If you liked that one, read this next “What is NOI and How to Find the Real Number in an Acquisition”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • What Your P&L Is Trying to Tell You Before You Buy

    What Your P&L Is Trying to Tell You Before You Buy

    Every seller hands you a P&L. Most buyers glance at the revenue number, nod, and move on. That’s a mistake that can cost you everything.

    A P&L is not just a scorecard of what a business earned. It’s a story. And if you know how to read it, that story will tell you whether the deal in front of you is as good as it looks, better than it looks, or a disaster waiting to happen.

    Here’s what to look for before you make an offer.

    Revenue Trends Matter More Than Revenue Totals

    A business that did $800,000 last year sounds great. But was that up from $600,000 the year before or down from $1.2 million? Direction matters as much as the number itself. Always ask for two to three years of P&Ls so you can see the trend, not just a snapshot. A business in decline can still show impressive trailing numbers while the foundation is quietly crumbling underneath.

    Expense Lines Tell You How the Business Was Really Run

    Look at every expense category and ask whether it makes sense for the size and type of business. Payroll as a percentage of revenue, cost of goods as a percentage of revenue, marketing spend, maintenance, utilities. If any category looks unusually low compared to industry norms ask why. Sometimes expenses are being deferred, maintenance skipped, staff underpaid, or costs run through a different entity entirely. Low expenses on paper can mean a capital problem waiting for you on day one of ownership.

    One Time Items Can Inflate the Picture

    Sellers love to show you their best year. What they don’t always volunteer is that their best year included a one time contract, an insurance payout, a PPP loan that hit as income, or a related party transaction that won’t repeat. Always ask what was unusual about any year that looks significantly better than the others. Normalized earnings, what the business actually produces in a typical year, is what you’re buying.

    Owner Compensation is Almost Never What It Appears

    In a small owner operated business the owner’s salary, or lack of one, dramatically affects what the P&L shows. Some owners pay themselves very little and run personal expenses through the business. Some pay themselves above market to reduce taxable income. You need to recast the financials with a fair market owner salary to understand what the business actually earns after replacing the owner’s labor. This is called a recasted or adjusted P&L and it’s the number that should drive your valuation.

    Gross Margin is Your Early Warning System

    Gross margin is revenue minus the direct cost of delivering that revenue. It tells you how efficiently the business converts sales into profit before overhead. If gross margin is shrinking year over year it means either prices aren’t keeping up with costs or the cost of delivery is rising. Either way it’s a problem that gets worse after you own it, not better.

    What the P&L Can’t Tell You

    Here’s the part most buyers miss. A P&L only shows you what was recorded. If bank accounts weren’t connected, if expenses were paid in cash, if revenue was deposited without being invoiced, none of that shows up. A clean looking P&L on a poorly kept set of books is not a clean business. It’s a clean looking document sitting on top of an unknown mess.

    This is why underwriting a deal means going beyond the P&L. Bank statements, tax returns, reconciliation history, and a proper review of the books behind the numbers will tell you far more than the summary document the seller hands you at the first meeting.

    The P&L is where the conversation starts. Not where it ends.

    If you’re looking at a deal right now and want a second set of eyes on the numbers, that’s exactly what I do. I offer a free initial review. Let’s talk.

    ~Wendi | Fractional CFO | PVIFinancial.com

    Click here to read: “The Hidden Financial Risk of Buying a Mom-and-Pop Operation”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • Your Bank Balance is Lying to You

    Your Bank Balance is Lying to You

    This isn’t a hypothetical. This is a real story about a real business owner who almost let her company slip through her fingers because of one habit that’s more common than you’d think.

    She was running her business by her bank balance.

    Every morning she’d check what was in the account, decide what she could spend, pay what felt urgent, and move on. No budget. No forecast. No real picture of what was coming in or going out beyond what she could see on her phone screen.

    For a while it worked. Business was good, work was flowing, and the balance stayed healthy enough that nothing felt alarming. But then the slow season hit.

    In her industry slow periods are normal and expected. But because she had never tracked her cash flow or planned around the seasonal dip, she had no idea it was coming until it was already there. Equipment loan payments didn’t slow down just because new work did. Payroll didn’t pause. Fixed expenses kept showing up like clockwork while the incoming revenue slowed to a trickle.

    So she did what a lot of business owners.

    She reached for the credit cards.

    By the time I came in the business had racked up credit card debt just to cover normal operating expenses. And the worst part was none of it was necessary. The slow period was predictable. The cash crunch was avoidable. But without a system to see it coming there was no way to prepare for it.

    The first thing we did was build a 90 day cash flow forecast.

    Not complicated. Not fancy. Just a clear picture of every dollar expected to come in and every dollar expected to go out over the next three months. When we laid it out she could see exactly where the gaps were, when new work would hit the account, and how to sequence her payments to get ahead of the debt instead of just treading water.

    She signed new work right around that time and with the forecast in place she could see exactly how to deploy that revenue strategically. Within 90 days she had paid off the credit card debt, cleared past due balances that had been lingering, and walked into the next quarter with cash in reserve for the first time in a long time.

    The credit card debt was the cost she could measure.

    The stress, the sleepless nights, the decisions made from a place of panic instead of clarity, that cost doesn’t show up on a P&L but every business owner who has been there knows exactly what it feels like.

    A 90 day cash flow forecast is one of the most valuable tools I build for my clients. It’s not complicated and it doesn’t take too long but the visibility it gives you changes everything. Running your business without one is like driving at night with no headlights and hoping the road stays straight.

    If you’re running your business by your bank balance right now you’re not alone. But you don’t have to stay there.

    I offer a free initial financial review. Let’s talk.

    ~Wendi | Fractional CFO | PVIFinancial.com

    Click here to read “What is a Fractional CFO and Does Your Small Business Need One”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • Nobody talks about the month after they closed on their RV park.

    Nobody talks about the month after they closed on their RV park.

    They post the keys. They post the sign. They post the big smile in front of the entrance with the caption “we did it” and 200 people like it and leave fire emojis in the comments.

    What they do not post is the phone call two weeks later when the manager who knew every single tenant, every quirky electrical panel, every vendor relationship, and every unwritten rule about how that park actually ran, calls to say she is not coming back. She was loyal to the previous owner. Not to you.

    They do not post the septic inspection they skipped because the seller said it was fine and they were already two weeks past the deadline and everyone just wanted to close.

    They do not post the moment they sit down with the actual financials and realize that the previous owner had been running that park on a handshake with the same three vendors for fifteen years. The landscaper who charged half of market rate because they were old friends. The electrician who came out at midnight for almost nothing because he owed the owner a favor. The insurance broker who had grandfathered them into a policy that no longer exists for new buyers. Those numbers were real. They just were not your numbers. And nobody told you that before you signed.

    They do not post the moment they realize that what looked like a lean, efficiently run operation was actually an operation built entirely around one person’s relationships, one person’s sweat, and one person’s decades of accumulated goodwill that evaporated the day the deed transferred.

    Nobody posts that part.

    I have talked to buyers who are living that story right now. Not one or two. Several. And here is what they all have in common. They are not careless people. They are not inexperienced people. They did their research. They read the books. They listened to the podcasts. They underwrote the deal three different ways and it cash flowed every time.

    But they made their final decisions while they were excited. And excitement is the most expensive state of mind in commercial real estate.

    When you are excited you round up on revenue and round down on expenses. When you are excited the manager seems dependable and the infrastructure seems solid and the seller seems trustworthy and the market seems strong. When you are excited you see the upside and you file the concerns away under “we will figure it out.”

    And then you close. And the excitement fades. And the business does not care about your excitement at all. It just needs to be run.

    Here is the thing nobody tells you before you buy your first RV park.

    The deal does not hurt you. The assumptions do.

    You assumed the revenue would hold. You assumed the manager would stay. You assumed the expenses reflected reality. You assumed the NOI on the flyer was built the same way you would build it. You assumed the infrastructure was as solid as it looked on the surface tour. You assumed that what worked for the previous owner under their cost structure and their debt load and their management style would work the same way for you.

    And every single one of those assumptions felt completely reasonable at the time.

    This is not a story about bad deals. Most of the parks I see are decent assets. The land is real. The income is real. The demand is real. This is a story about what happens when someone buys a business without a clear and honest picture of what it actually costs to run it under new ownership, with new debt, and without the institutional knowledge that walked out the door at closing.

    The gap between the seller’s story and your reality is where deals go sideways. Not at closing. After.

    The buyers who do well are not smarter than the ones who struggle. They are not luckier. They do not have some special access to better deals. They just had someone in their corner before they signed who was willing to tell them the uncomfortable version of the story. Someone who rebuilt the NOI from scratch instead of accepting it. Someone who asked the hard questions about the manager and the infrastructure and the revenue mix before it was too late to walk away or renegotiate.

    Someone whose job it was to be the calm voice in the room when everyone else was caught up in the excitement of the deal.

    If you are looking at a park right now and something feels off but you cannot quite put your finger on it, that feeling is worth paying attention to. It is usually your gut doing the underwriting your spreadsheet missed.

    And if you want someone to look at the numbers with you before you decide, that is exactly what I do.

    ~Wendi | PVI Financial | Fractional CFO and Bookkeeping Services for Small Business and Outdoor Hospitality

    Read this next “The Hidden Financial Risks of Buying a Mom and Pop Operation”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • The 5 Things Your Bookkeeper Should Be Telling You But Isn’t

    The 5 Things Your Bookkeeper Should Be Telling You But Isn’t

    Most small business owners assume that if they have a bookkeeper, their finances are under control. The bills are getting paid, the receipts are getting entered, and somebody is reconciling the bank account every month. That’s enough, right?

    Not even close.

    You can read “What Good Bookkeeping Actually Looks Like” here.

    A bookkeeper records what happened. That’s their job and a good one does it accurately and consistently. But recording history is not the same as helping you understand it, act on it, or use it to grow. And if your bookkeeper is only doing the first part, you’re leaving the most valuable piece on the table.

    Here are five things your bookkeeper should be telling you but probably isn’t.

    Your Cash Flow is About to Get Tight

    A good bookkeeper doesn’t just reconcile last month, they’re looking ahead. If your receivables are slow, your payables are stacking up, and your bank balance is about to feel it, you should know that before it happens, not after. If nobody is flagging upcoming cash crunches for you, you’re flying blind every single month.

    Your Margins Are Shrinking and Here’s Why

    Revenue going up but profit not keeping pace? That’s a margin problem and it shows up in the numbers before you feel it in your gut. Your bookkeeper should be comparing your gross margin month over month and flagging when expenses in a specific category are creeping up. If they’re just entering transactions without analyzing trends, you’re missing the early warning system your business needs.

    You Have a Revenue Concentration Problem

    If the majority of your revenue is coming from one client, one location, one revenue stream, or one season, that’s a risk. A bookkeeper who understands your business should be able to see that in your P&L and bring it to your attention. Diversification isn’t just a strategy conversation, it starts with knowing what your numbers actually show.

    Your Books Aren’t Audit Ready

    Most business owners don’t think about this until they need financing, attract a buyer, or get a letter from the IRS. By then it’s too late to fix things cleanly. Your bookkeeper should be maintaining your file as if someone could walk in tomorrow and ask to see everything. Reconciled accounts, documented transactions, clean categorization, no mystery balances sitting unresolved for months.

    You’re Leaving Tax Deductions on the Table

    A bookkeeper who is paying attention to your business will notice things. Equipment that should be depreciated. Home office expenses that aren’t being tracked. Mileage that’s never recorded. Vehicle use that’s partially business. These aren’t aggressive tax strategies, they’re legitimate deductions that disappear if nobody is watching for them. Your bookkeeper should be flagging these throughout the year, not leaving it all for your CPA to sort out in April.

    So What’s the Difference?

    The difference between a bookkeeper and a fractional CFO is exactly this. A bookkeeper maintains the record. A fractional CFO uses the record to help you run a better business. They bring you the insights, flag the risks, and help you make decisions based on real data instead of gut feel.

    If you’ve never had someone in your corner doing that, you don’t know what you’re missing. And your bottom line is probably feeling it.

    Want to know what that level of financial support actually looks like for your business? I offer a free initial review. Let’s talk.

    ~Wendi | Fractional CFO | PVIFinancial.com

    Click here to read “What is a Fractional CFO and Does Your Small Business Need One?”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • The Number That Tells You If You’re Overpaying for an RV Park Before You Make an Offer

    The Number That Tells You If You’re Overpaying for an RV Park Before You Make an Offer

    Most buyers look at the asking price, see the NOI on the broker’s flyer, do some quick math, and decide the deal makes sense. I get it. The numbers look clean. The cap rate looks reasonable. The cash flow looks solid.

    But here is the thing. That is not underwriting. That is the seller’s story. And the seller’s story is always the best version of the truth.

    The number that actually tells you whether you are overpaying is not on any flyer. You have to build it yourself. And most buyers never do.

    What most buyers actually do

    They take the NOI the broker provides, divide it by the asking cap rate, and decide if the price feels right. Maybe they run it through a quick calculator. Maybe they check the debt service and see that it cash flows on paper.

    That is it. Deal made.

    And then six months after closing they are sitting at their kitchen table wondering why the numbers do not look anything like what they were shown. Not because they were lied to. Because nobody rebuilt the numbers honestly before they signed.

    The number that actually matters

    Your reconstructed NOI. Not the seller’s NOI. Yours.

    Built from verified income, real vacancy, market rate management costs, honest CapEx, accurate expenses, and a debt structure you can actually survive. That number, divided by what you are paying, is the only cap rate that matters.

    Everything else is marketing.

    The three things that inflate almost every seller’s NOI

    I have underwritten a lot of RV park deals. And I see the same three things inflating the NOI on almost every single one.

    The first one is no management fee. The current owner self manages the park. They take no salary, they charge no management fee, and their expenses look lean and efficient. Except you are not them. If you plan to hire a manager, or if you ever want to sell this park to someone who will not self manage, that NOI is overstated by $40,000 to $60,000 a year on a park doing $500,000 in revenue. That is not a small number.

    The second one is deferred CapEx. The seller has not put meaningful money back into the property in years. Roads, bathhouses, electrical, roofs, equipment. None of it shows up as an ongoing expense because they have just been letting things age. But you are going to inherit all of it. And in your first few years of ownership you will pay for every dollar they did not spend.

    The third one is below market expenses. Long term vendors, family deals, owner relationships that disappear the day you close. The insurance agent who gave them a deal because they have been friends for 20 years. The maintenance guy who works cheap because the owner does half the work himself. Those numbers are not your numbers.

    What the reconstructed NOI usually looks like

    Let me give you a real example of how this plays out.

    A park is advertised at a 9% cap rate. Looks great on paper. Buyer gets excited. But when you rebuild the NOI honestly, adding a market rate management fee, normalizing CapEx, adjusting the vendor expenses to what a new owner would actually pay, and running real vacancy numbers, that 9% cap rate becomes a 5.5% cap rate.

    At the asking price that is a completely different deal. At a 5.5% cap rate you are now overpaying by hundreds of thousands of dollars for the same cash flow. And you will not find that out until after you close.

    That is not a hypothetical. That is what I see on a regular basis.

    This is the sentence I want you to write down:

    The price you pay is permanent. The NOI you inherit is not.

    The price you agree to on day one is locked in. You cannot go back and renegotiate it when the numbers do not pan out. But the NOI is not fixed. It can go up and it can go down, and the seller has every incentive to show you the version where it goes up.

    Your job before you make an offer is to figure out what the NOI actually looks like under your ownership, with your costs, your management structure, and your debt. Not the seller’s version. Yours.

    That reconstructed NOI is the number that tells you if you are overpaying. And it is the only number that matters.

    If you want help rebuilding the numbers on a deal you are looking at before you make an offer, that is exactly what I do – Acquisition Underwriting for RV parks. Reach out at pvifinancial.com before you sign anything.

    ~Wendi | Fractional CFO | PVIFinancial.com

    If you liked this, read this next “What is NOI and How to Find the Real Number in an Acquisition”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • The One Financial System Every RV Park Owner Needs Before They Close

    The One Financial System Every RV Park Owner Needs Before They Close

    Set this up before day one and thank yourself later

    In the RV park acquisition community there’s a pattern I see over and over again.

    Buyers spend months doing due diligence. They verify the T12, they walk the property, they review the lease agreements and utility infrastructure and staffing model. They are thorough, careful, and smart.

    And then they close, and they have absolutely no financial system in place to manage the asset they just bought.

    The books are a mess from the transition. The bank accounts are commingled. Nobody knows what the first month actually produced because there’s no baseline reporting structure. And by the time they figure it out they’re already three months in and flying blind on a multi-million dollar investment.

    It’s one of the most common gaps I see in new acquisitions. And it’s completely avoidable.

    Here’s the financial system every RV park owner needs to have in place before, or immediately after, they close.

    Step 1: Get your banking structure right from day one

    Before you receive a single dollar of revenue you need at least three separate bank accounts:

    Operating account. This is your day to day account. Revenue comes in here. Operating expenses go out from here. Payroll, utilities, supplies, management fees, all paid from this account.

    CapEx reserve account. Every month transfer 5% of gross revenue into this account and don’t touch it for anything other than capital improvements and major repairs. This account is your future roof, your aging electrical hookups, your road resurfacing. Fund it from month one even when everything looks fine.

    Tax reserve account. Set aside a percentage of net income every month for taxes. The exact percentage depends on your entity structure and tax situation, so talk to your CPA, but a general starting point is 25-30% of net profit. Nothing creates more stress than a surprise tax bill you didn’t plan for.

    This three account structure eliminates more financial stress than almost anything else I recommend. When your operating account tells you what you actually have available to spend, not a commingled number that includes your CapEx and tax reserves, you make better decisions. It will also save you from paying expensive bookkeeping clean up fees.

    Step 2: Set up your bookkeeping system immediately

    Get QuickBooks Online or your preferred bookkeeping software set up and connected to your bank accounts before you close or within the first week after. Every transaction from day one should flow through your books.

    I know this sounds basic but new owners often let the first month or two slide because they’re busy getting the operations figured out. Then they have a backlog of transactions to clean up and no clean baseline to measure performance against.

    Your first month of ownership is your most important baseline. Capture it cleanly.

    Set up your chart of accounts to reflect the specific revenue and expense categories of an RV park, including site type revenue, utility income, amenity fees, staffing, utilities, maintenance, management fees, insurance, and debt service as separate line items. A generic chart of accounts designed for a retail business will not give you the visibility you need.

    Step 3: Build your pro-forma tracking document

    Take the pro-forma you used during underwriting and turn it into a living monthly tracking document. Every month you enter your actual results alongside your projections and calculate the variance.

    This document is your single most important management tool in year one. It tells you whether you’re on track, where you’re ahead, and where you’re behind, and it forces you to ask why on both sides.

    Ahead on occupancy? Great, what drove that and can you replicate it? Behind on rate? Why, is it a pricing issue, a mix issue, or a market issue? Every variance has a story and understanding the story is how you manage the asset instead of just watching it.

    Step 4: Establish your monthly reporting rhythm

    Pick a day and commit to reviewing your financials every single month on that day without fail the 10th of the month works well for most operators.

    Your monthly review should cover your P&L for the month compared to pro-forma and prior year, your cash position and 30/60/90 day forecast, your occupancy and rate by site type compared to pro forma, your expense ratio and any line items running above budget, and your CapEx reserve balance and any upcoming capital needs.

    The whole review should take 30 to 60 minutes if your books are clean and your reporting is set up properly. That’s one hour a month to stay on top of a multi-million dollar investment. There is no better return on your time.

    Step 5: Know your numbers before your lender asks for them

    If you have a loan on the property, seller carry, bank financing, or otherwise, your lender will likely require periodic financial reporting. But more importantly you want to be the person who knows your numbers cold before anyone asks.

    Lenders get nervous when borrowers don’t know their own financials. They get confident when a borrower calls them proactively and says here’s where we are, here’s what’s working, here’s what we’re watching. That relationship dynamic matters, especially if you ever need flexibility from your lender.

    Know your numbers. Own your numbers. Be the most informed person in the room about your own asset.

    The bottom line

    The financial system I just described is not complicated. It doesn’t require a finance degree or expensive software. What it requires is intentionality, setting it up before the chaos of ownership sets in and committing to maintaining it consistently.

    The RV Park operators who build real lasting wealth are the ones who treat the financial side of their business with the same seriousness as the operational side. They know their numbers. They track the right metrics. And they never let more than 30 days go by without a clear picture of where they stand.

    You can absolutely build this yourself. And if you want help setting it up, or want someone to manage it for you so you can focus on running the park, that’s exactly what I help new owners build. I’d love to work with you from day one.

    Visit me at https://www.pvifinancial.com and let’s talk about getting your financial foundation right from day one.

    ~Wendi | PVI Financial | Fractional CFO & Bookkeeping Services for Small Business & Outdoor Hospitality

    If you found value in that one, click here to read “What Good Bookkeeping Actually Looks Like and Why Most Small Businesses Don’t Have It”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • Why Your RV Park’s Best Season Can Also Be Its Biggest Financial Risk

    Why Your RV Park’s Best Season Can Also Be Its Biggest Financial Risk

    And what to do about it before the shoulder season hits

    Ask any RV park owner what their favorite time of year is and they’ll tell you summer. The sites are full, the revenue is flowing, the energy is high and everything feels great.

    And then September arrives.

    For a lot of RV park owners the shoulder season is when the financial chickens come home to roost. The cash that felt abundant in July suddenly has to stretch a lot further. Expenses don’t drop as fast as revenue does. Payroll still runs. Debt service still runs. Insurance still runs. And if you didn’t manage your peak season cash wisely you can find yourself in a surprisingly tight spot on a property that just had its best revenue months of the year.

    I call this the peak season trap. And it catches more new owners than almost anything else.

    Here’s how to avoid it.

    Understand your revenue curve before you close

    Every RV park has a seasonality profile. Some are heavily summer weighted with 60-70% of annual revenue coming in May through August. Others have a more even distribution with strong spring and fall shoulder seasons. Some have winter demand driven by snowbirds or proximity to ski areas.

    Before you close on any RV park acquisition you should understand exactly what the monthly revenue distribution looks like over a full year. Don’t just look at the annual T12 number, break it down month by month.

    Ask for monthly revenue data going back at least two years. Map it out. Understand when the peaks are, when the valleys are, and how deep those valleys go. That monthly revenue curve is your cash flow roadmap for the first year of ownership.

    Build your budget around the valleys, not the peaks

    This is the mindset shift that separates financially savvy operators from ones who get caught short.

    When you’re in peak season it’s tempting to make spending decisions based on current cash flow. Revenue is strong, the bank account looks healthy, and there are always improvements to make and expenses to approve.

    But your peak season cash has to carry you through the valley. Every dollar you spend in July is a dollar that isn’t available in November.

    Build your annual budget starting from your lowest revenue month. Make sure your fixed costs, debt service, payroll, insurance, utilities, can be covered in your worst month with your lowest expected revenue. Everything above that is your operating cushion and your growth fund.

    If your worst month revenue can’t cover your fixed costs you have a structural problem that needs to be addressed, whether that’s adding long term tenants for stable monthly income, reducing fixed costs, or building a larger cash reserve before you close.

    Use peak season to fund your reserves

    Peak season is not just when you make money. It’s when you build the financial cushion that protects you the rest of the year.

    Here’s the system I recommend for every RV park owner going into their first peak season:

    Every week during peak season calculate what percentage of your monthly revenue target you’ve hit. Once you’ve covered your projected monthly operating expenses, debt service, and CapEx reserve contribution, every additional dollar should be split between your tax reserve and your operating cash cushion.

    The goal is to exit peak season with enough cash in your operating account to cover at least three months of fixed expenses. That cushion is your shoulder season safety net.

    If you hit that target and still have surplus cash, that’s when you think about reinvestment, improvements, or distributions. Not before.

    Watch your expense timing carefully

    One of the most common mistakes new RV park owners make is front loading expenses into peak season without thinking about the cash flow timing.

    You want to repave the entrance road. You want to upgrade the bathhouse. You want to add a new amenity. All of those are valid investments, but if you execute them during peak season you’re consuming cash at exactly the moment you should be building it.

    In general capital improvements and major discretionary expenses are better timed for the shoulder season or off season when your operations are quieter and your team has more bandwidth. Your cash will thank you.

    Plan for the transition before it happens

    Most new owners don’t start thinking about shoulder season until they’re in it. By then it’s too late to adjust.

    The time to plan for the shoulder season is during peak season, when revenue is strong and you have the mental space to think clearly. Build your shoulder season budget in July. Know exactly what your cash position needs to look like on September 1st to get you comfortably through to the following spring.

    Then manage toward that number intentionally for the rest of peak season.

    The bottom line

    Seasonality is one of the great joys of the outdoor hospitality business. There is something genuinely wonderful about a full park on a summer weekend. But it’s also one of the great financial risks, because the math of a seasonal business is unforgiving if you’re not managing it intentionally.

    The owners who thrive long term are the ones who use their best months to protect their worst months. They budget from the valley up, they build their reserves during peak season, and they never let a strong July lull them into decisions that hurt them in November.

    You can absolutely do this. And if you want a financial partner who tracks your seasonality with you, builds your cash flow forecast, and makes sure you’re set up for every season, I’d love to work with you.

    Visit me at https://www.pvifinancial.com to get started with a free Financial Health Check.

    ~Wendi | PVI Financial | Fractional CFO & Bookkeeping Services for Small Business & Outdoor Hospitality

    If this resonates you will want to read this next: “Why Profitable Businesses Run Out of Cash”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • How to Analyze a Seller Carry Deal and Whether the Terms Actually Work for You

    How to Analyze a Seller Carry Deal and Whether the Terms Actually Work for You

    Because seller financing sounds great until you run the actual numbers

    If you spend any time in the creative real estate space you hear about seller carry deals constantly. And for good reason, when they’re structured well they can be genuinely transformative. Lower barriers to entry, flexible terms, no bank approval required, and a motivated seller who wants the deal to work as much as you do.

    But here’s what doesn’t get talked about enough. Seller carry deals can also be structured in ways that look attractive on the surface and quietly destroy your returns underneath. The terms matter enormously and not all seller financing is created equal.

    I’ve analyzed a lot of these deals. Here’s how I think through them and what I look for before I ever say yes.

    What is a seller carry deal?

    For anyone newer to the concept, a seller carry deal, also called seller financing or an owner carry, is when the seller of a property acts as the lender instead of a bank. Rather than you going to a bank to borrow the purchase price the seller carries a note and you make payments directly to them over time.

    The appeal is obvious. No bank qualification process, potentially lower interest rates than conventional financing, more flexible terms, and a seller who is often motivated to make the deal work because they’re receiving monthly payments rather than a lump sum.

    The risk is equally obvious once you understand it. The terms are entirely negotiable which means they can be structured in your favor or against you depending on how well you understand what you’re agreeing to.

    The four numbers that determine whether a seller carry deal actually works

    Before I get excited about any seller carry deal I run four numbers. All four have to make sense together or I keep negotiating or I walk.

    1. The interest rate

    Seller carry deals typically come with interest rates somewhere between 5% and 8% in today’s market though this varies widely. The rate matters because it directly determines your monthly payment and therefore your cash flow.

    A $3,000,000 seller carry note at 5% interest only for 10 years costs you $12,500 per month. The same note at 7% costs you $17,500 per month. That $5,000 monthly difference is $60,000 per year that comes directly out of your cash flow.

    Always model the payment at the actual proposed rate and make sure your NOI can absorb it with adequate cushion. Which brings me to the second number.

    2. The debt service coverage ratio

    The DSCR is especially critical in seller carry deals because the terms are flexible and sellers sometimes propose payment structures that look affordable without being sustainable.

    Divide your adjusted NOI by your annual debt service. I want to see at least 1.5x coverage, meaning my NOI covers the payments by 50%. Anything below 1.25x and I’m either renegotiating the terms or walking away.

    A seller carry deal with a 1.05x DSCR looks like it works on paper. But one bad month, one unexpected expense, one occupancy dip, and you’re behind on your payments to the seller. That’s not a position you want to be in.

    3. The balloon payment

    Most seller carry deals have a balloon payment, a point in time where the remaining balance becomes due in full. Common balloon terms are 3, 5, 7, or 10 years.

    The balloon is where a lot of buyers get into trouble. They structure a deal that cash flows well for 5 years and then discover they can’t refinance or sell at the balloon date under favorable conditions. Maybe the market shifted. Maybe their credit situation changed. Maybe interest rates moved and conventional financing no longer pencils.

    Before you sign any seller carry agreement you need a clear plan for what happens at the balloon date. Can you refinance with a conventional lender at that point? Will the property have realistically appreciated enough to sell? Can you negotiate an extension with the seller if needed?

    Never assume the balloon will take care of itself. Plan for it from day one.

    4. The amortization schedule

    This one surprises a lot of newer investors. A seller carry note can have an interest only payment structure, a fully amortizing structure, or something in between. The difference matters enormously for your cash flow and your equity building.

    An interest only note means every payment goes entirely to interest and your principal balance never decreases. Your monthly payment is lower which helps cash flow but you’re not building equity through paydown and you’ll owe the full original balance at the balloon date.

    A fully amortizing note means each payment includes both principal and interest. Your payment is higher but your balance decreases over time and you’re building equity with every payment.

    Neither structure is automatically better. It depends on your cash flow situation, your hold period, and your exit strategy. What matters is that you understand exactly what you’re agreeing to and have modeled both scenarios.

    The terms that are negotiable and the ones that matter most

    Everything in a seller carry deal is negotiable. Here are the terms worth fighting hardest for:

    The interest rate is obviously important but it’s not always the most important. A slightly higher rate with a longer balloon and no prepayment penalty can be better than a lower rate with a short balloon and a penalty for paying it off early.

    The prepayment penalty is one people often overlook. If you plan to refinance or sell before the balloon date a prepayment penalty can cost you significantly. Always ask about prepayment terms and try to negotiate them out entirely or limit them to the first year or two.

    The balloon date itself is worth negotiating hard on. Longer is almost always better because it gives you more time to stabilize the asset, build your cash reserves, and position yourself for a favorable refinance or sale.

    A real world example

    Let me walk you through how I analyzed the seller carry on an RV park deal recently.

    The property had an adjusted NOI of approximately $400,000. The seller carry was structured at approximately $220,000 in annual debt service on a $4,500,000 purchase price.

    DSCR: $400,000 divided by $220,000 equals 1.82x. Healthy coverage with good cushion.

    Cash flow after debt service: $180,000 annually or $15,000 per month.

    After a 5% CapEx reserve of $25,000 annually the free cash flow was $155,000 per year.

    The terms worked mathematically. The deal ultimately didn’t close for reasons unrelated to the financing structure but the seller carry terms themselves were workable and the numbers supported them.

    That’s what a properly analyzed seller carry deal looks like. The numbers tell a clear and consistent story at every level.

    The bottom line

    Seller carry deals are a powerful tool when they’re structured correctly and analyzed rigorously. They can open doors that conventional financing closes and create win-win situations for both buyer and seller.

    But the flexibility that makes them attractive is the same flexibility that can get you into trouble if you don’t know what you’re analyzing. Know your four numbers. Understand your balloon. Negotiate your terms. And make sure the deal works not just at closing but at every point in your hold period.

    If you want help analyzing the terms of a seller carry deal you’re looking at I would love to work through the numbers with you. That’s exactly the kind of analysis that can save you from a deal that looks good and isn’t, or give you the confidence to move forward on one that truly is.

    Visit me at https://www.pvifinancial.com and let’s look at your deal together.

    ~Wendi | PVI Financial | Fractional CFO & Bookkeeping Services for Small Business & Outdoor Hospitality

    Click here to read “I Have Analyzed Dozens of RV Park Deals, Here is What I Look At Before I Look At Anything Else”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • Why Your Books and Your Guest Experience Are Actually the Same Thing

    Why Your Books and Your Guest Experience Are Actually the Same Thing

    Want to understand what good books actually look like first? Start here, “What Good Bookkeeping Looks Like”

    This one might surprise you.

    When most people think about bookkeeping they think about compliance. Taxes. Staying out of trouble. Necessary but boring back office stuff that has nothing to do with the actual guest experience.

    But here’s what I’ve seen over and over working with hospitality and outdoor property owners. The owners who have clean financial visibility make better decisions. And better decisions, almost without exception, lead to a better guest experience. Let me explain what I mean.

    When your books are a mess you make reactive decisions.

    You raise rates because you feel like you need more revenue, not because the data supports it. You cut maintenance because the bank balance looks low, not because it’s actually the right call. You delay an amenity upgrade because you’re not sure if you can afford it, even though the numbers might actually support it if you could see them clearly.

    Reactive decisions frustrate guests. They notice when maintenance slips. They notice when the pool equipment hasn’t been updated. They notice when your pricing feels random compared to the experience you’re delivering.

    Now flip it.

    When your numbers are clean and current you can see exactly what each revenue stream is generating. You know your cost per occupied site. You know which amenities are pulling their weight and which ones aren’t.

    Think about it this way. A $5 per night rate increase on a 100 pad park running at 75% occupancy is 75 occupied sites per night. That’s $375 per night, $11,250 per month, $135,000 per year in additional gross revenue straight to your bottom line. Small moves on rate add up fast when you have the volume to back them up. But if you don’t know your data, you can’t even consider this logically, and if you price by gut feel instead of numbers you may find your guests heading down the street to someone who figured it out.

    That clarity lets you make intentional decisions instead of reactive ones. And intentional decisions protect and improve the guest experience because you’re investing where it actually matters instead of cutting blindly or spending without a plan.

    There’s another side to this too.

    Industry leaders in the outdoor hospitality space talk about the danger of mixing investor language with guest language. When owners are so focused on squeezing NOI and talking about yield optimization, guests start to feel like a transaction instead of a vacationer. The best operators are the ones who use the financial data internally to run a smarter business while still showing up for guests as a place that genuinely cares about the experience.

    Clean books make that possible. They give you the confidence to invest in the right places because you actually know what you can afford and what will move the needle.

    Your guest experience is a reflection of how well you run your business financially.

    The two are not separate.

    If your books can’t tell you where to invest, how to price, or which parts of your operation are profitable, you’re making those decisions blind. And your guests will eventually feel it.

    Want to know what financial clarity actually looks like for a hospitality property? I offer a free initial review. Let’s talk.

    Ready to look at the numbers behind your property? Read this next, “What Squeezed NOI Actually Looks Like”

  • What Squeezed NOI Actually Looks Like (And How to Fix It)

    What Squeezed NOI Actually Looks Like (And How to Fix It)

    New to NOI? Read this first, What is NOI, then come back here.

    You’ve probably heard the term NOI thrown around constantly in the investment space. Net Operating Income. The number everyone uses to value a property, qualify for financing, and measure performance.

    But what happens when NOI stops growing and starts shrinking?

    That’s called squeezed NOI and it’s happening across the outdoor hospitality space right now. Revenue softening while expenses keep climbing. The gap between what comes in and what goes out getting tighter every month. And a lot of new owners who bought at peak valuations in 2020 to 2022 are now staring at a financial picture that looks nothing like what the pro forma said.

    So what does squeezed NOI actually look like in real life?

    It looks like this:

    Your occupancy is solid but your net is shrinking. You raised rates a little but utilities, insurance, payroll and maintenance ate the increase before it hit the bottom line. You’re busy but you don’t feel profitable. Your bank balance looks ok but you can’t figure out where the money went.

    Sound familiar?

    Here’s what’s usually driving it:

    Expenses that were never properly tracked or categorized so you don’t even know where the leaks are. Rate structures that haven’t been pressure tested against actual cost increases. Revenue streams that are underleveraged, amenities, add-ons, extended stays, that are generating activity but not optimized for profitability. And books that can’t tell you which part of the business is making money and which part is dragging everything down.

    Here’s how you fix it:

    First you have to be able to see it clearly. That means clean books, real numbers, and a P&L that breaks down revenue and expenses by category, not just one big blended picture. You cannot fix what you cannot measure.

    Second you look at every expense line and ask whether it’s fixed, variable, or discretionary. Fixed costs are what they are. Variable and discretionary costs are where you find the margin.

    Third you look at revenue per site, per night, per guest, and ask honestly whether you’re leaving money on the table. Most properties are. Not because owners are lazy but because they’re too busy operating to step back and analyze.

    Fourth you build a simple 12 month forward projection so you’re not reacting to the numbers every month, you’re anticipating them.

    This is exactly the kind of work a fractional CFO does. Not just recording what happened but helping you understand why it happened and what to do about it.

    Squeezed NOI is a warning, not a death sentence. But you have to catch it early and you have to have the right financial visibility to act on it.

    If your books can’t tell you where your margin is going, that’s the first thing to fix.

    Questions about your NOI picture? I offer a free initial financial review. Let’s talk.

    ~Wendi | Fractional CFO | PVIFinancial.com

    If your NOI is getting squeezed there’s a good chance cash flow is feeling it too. Read this next: “Why Profitable Businesses Run Out of Cash and How To Make Sure Your’s Doesn’t”

    Click here to Download my free guide, The 5 Numbers Every RV Park Buyer Must Know Before Making an Offer

  • The Hidden Financial Risks of Buying a Mom-and-Pop Operation

    The Hidden Financial Risks of Buying a Mom-and-Pop Operation

    You found the deal. You closed it. You’re fired up and ready to go.

    And then you open the books.

    If you’ve recently acquired a small business or hospitality property, an RV park, a resort, a retail operation, there’s a good chance you inherited more than you bargained for financially. Not because the seller was necessarily dishonest. But because most mom-and-pop operations were never run with clean books to begin with.

    Here are some of the most common things I find hiding in inherited QuickBooks files:

    ๐Ÿ”ด Bank accounts that aren’t connected to the books. Multiple checking accounts, a savings account, credit cards, and only one of them actually flows through the accounting software. That means a significant portion of real business activity is either missing entirely or manually entered with no reconciliation. The P&L looks like it has expenses. But none of it can be verified. You can’t make good decisions on numbers you can’t trust.

    ๐Ÿ”ด Payroll liabilities recorded incorrectly. Negative payroll liability balances are a red flag. It usually means someone was recording tax payments by going directly into the bank register instead of using the proper payroll workflow. The taxes may have actually been paid, but the books can’t prove it without a CPA reconciling IRS transcripts against what the software shows.

    ๐Ÿ”ด Employee loans buried as business expenses. This one comes up more than you’d think. A loan to an employee gets quietly written off as an operating expense instead of being run through payroll as taxable compensation. The prior owner may have filed a tax return with that entry in it. Now it’s sitting in your inherited file. Know what’s in there before anyone touches it.

    ๐Ÿ”ด Depreciation recapture exposure. When you buy an LLC outright you may be stepping into the prior owner’s accumulated depreciation, which means when those assets are eventually sold the IRS will recapture that depreciation as ordinary income regardless of who took the original deductions. This is a conversation to have with your CPA before you close, not after. Understanding what you’re buying and how it’s structured can significantly impact your long term tax picture.

    ๐Ÿ”ด Balance sheet accounts that are pure fiction. Inventory balances from years ago never updated. Loans that were paid off at closing still showing as liabilities. Assets with no supporting documentation. A balance sheet that looks complete but reflects nothing about the real state of the business you just bought.

    So What Do You Do About It?

    Don’t panic and don’t start fixing things randomly. A wrong entry in the wrong place makes a mess worse.

    Get your closing statement and purchase agreement in hand before anyone touches anything. That document establishes what you actually bought, what liabilities you assumed, and what your opening balances should look like.

    Draw a clean line at your acquisition date. Archive the prior owner’s history. Build your books forward from day one of YOUR ownership with correct opening balances established by a CPA.

    And understand that this isn’t just a cleanup, it’s a new owner setup. One of the most important investments you’ll make in your first 90 days.

    The money you spent to acquire that business deserves a financial foundation that actually reflects reality. You can’t make smart decisions on rates, staffing, capital improvements, or exit strategy if your books are built on someone else’s mess.

    Get the foundation right first. Everything else flows from there.

    Questions about what you inherited? I offer a free initial file review. Let’s talk.

    ~Wendi | Fractional CFO | PVIFinancial.com

    Click here to read “What Good Bookkeeping Looks Like and Why Most Small Businesses Don’t Have It”

    Click here to read “How To Structure Your First 90 Days as a New RV Park Owner”

  • What Is a Fractional CFO and Does Your Small Business Need One?

    What Is a Fractional CFO and Does Your Small Business Need One?

    If you have heard the term fractional CFO floating around lately and wondered what it actually means, you are not alone. It is one of those phrases that sounds more complicated than it is. Let me break it down in plain language and help you figure out whether it is something your business actually needs right now.

    First, what is a CFO?

    A Chief Financial Officer is the senior financial leader of a company. In a large corporation the CFO oversees everything from financial reporting and cash flow management to strategic planning, capital raises, and investor relations. They are the person in the room who understands not just what the numbers say but what they mean and what to do about them.

    A full time CFO at a large company can earn $200,000 to $500,000 per year or more. For most small businesses that is simply not a realistic option.

    So what is a Fractional CFO?

    A fractional CFO gives you access to that same level of financial expertise without the full time salary, benefits, and overhead. You get a seasoned financial professional working with your business on a part time or project basis, for a fraction of the cost.

    The word fractional simply means you are getting a portion of their time rather than all of it. You pay for what you need, when you need it.

    What does a fractional CFO actually do?

    This is where it gets interesting because the answer is different for every business. A fractional CFO is not your bookkeeper. They are not your tax preparer. They are the person who takes all of that financial data and turns it into something you can actually use to run your business better.

    In practical terms that might look like:

    A monthly CFO report that tells you exactly where your money went, where it is going, and what you should do about it. A 30/60/90 day cash flow forecast so you are never surprised by what is coming. A KPI dashboard that tracks the metrics that actually matter for your specific business. Strategic guidance on pricing, expenses, debt, hiring, and growth decisions. Deal analysis and acquisition underwriting if you are a real estate investor or looking to buy a business. A cash flow rescue plan if things have gotten off track and you need to stabilize fast.

    Think of it this way. Your bookkeeper tells you what happened. Your CPA helps you file your taxes. Your fractional CFO helps you figure out what to do next.

    How is a fractional CFO different from a bookkeeper?

    I get this question a lot, especially from clients who have had a bookkeeper for years and are happy with their books. Clean books are essential. But clean books alone do not tell you whether your business is healthy, whether you are pricing your services correctly, whether you have enough cash to make it through a slow season, or whether you are leaving money on the table every single month.

    A bookkeeper looks backward. A fractional CFO looks forward.

    I started as a bookkeeper. I am good at it and I still offer it. But I made the shift to fractional CFO work because I kept seeing the same thing over and over. Business owners with clean books who had absolutely no idea what their numbers were telling them. No cash flow visibility. No KPI tracking. No strategic thinking about where the money was going or where it needed to go. Just a P&L that showed up once a month that nobody really knew how to use.

    That gap is exactly what a fractional CFO fills.

    Does your small business need one?

    Here are some honest signals that the answer might be yes:

    Your business is generating revenue but you still feel like you never have enough cash. You make financial decisions based on your bank balance rather than a forward looking picture. You have no idea what your profit margins actually are by product or service. You are growing but the growth feels chaotic and financially stressful rather than exciting. You are thinking about acquiring a property or business and want someone in your corner who can analyze the deal. You are heading into a busy season and have no plan for managing the cash that comes in. You have never had anyone really dig into your expenses to find what is being wasted.

    If any of those sound familiar, a fractional CFO is probably worth a conversation.

    What does it cost?

    Fractional CFO engagements vary widely depending on the scope of work and the complexity of your business. Monthly retainers typically range from $1,500 to $15,000 per month. Newer or simpler businesses will be on the lower end of that range. Project based work is also available for one time needs like deal analysis, financial model builds, or cash flow rescue plans.

    The better question is not what does it cost but what is it worth. If a fractional CFO identifies $50,000 in recoverable expenses, helps you avoid a bad acquisition, or gives you the financial clarity to make one better decision per month, the fee pays for itself many times over.

    How do you get started?

    At PVI Financial I work with small business owners and real estate investors who are ready to stop guessing and start making decisions from a place of clarity. I offer a free financial health check to start, so you can see exactly where your business stands before committing to anything.

    If you are curious whether a fractional CFO makes sense for your business, reach out at pvifinancial.com. The conversation is free and you will walk away with more clarity than you had before regardless of whether we work together.
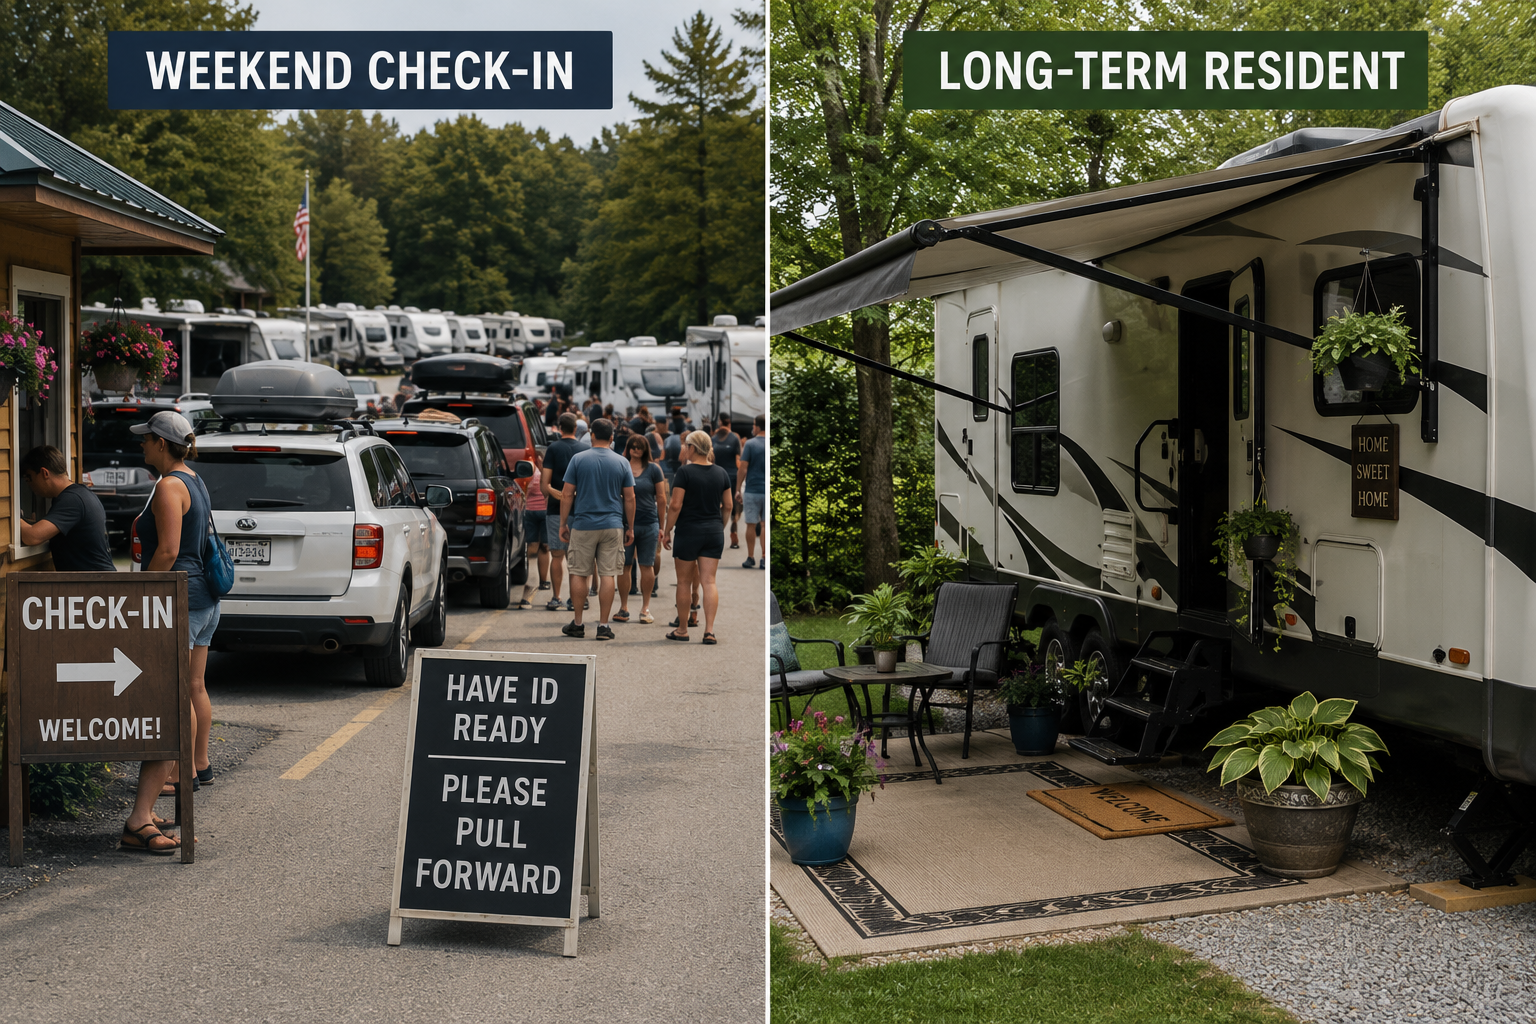
    That is a promise.

    Wendi Rook is the founder of PVI Financial, a fractional CFO and bookkeeping practice serving small business owners and outdoor hospitality operators. She is a private money lender, real estate investor, and former long time business owner with a multi-seven figure exit. She helps business owners find clarity in their numbers and confidence in their decisions.

    Enjoyed this post? Click here to read “Why Profitable Businesses Run Out of Cash and How To Make Sure Yours Doesn’t”

  • Why Profitable Businesses Run Out of Cash and How to Make Sure Yours Doesn’t

    Why Profitable Businesses Run Out of Cash and How to Make Sure Yours Doesn’t

    The most dangerous financial surprise in business isn’t losing money. It’s running out of cash while making it.

    If I told you a business could be profitable on paper and still run out of cash and fail, you might think I was exaggerating.

    I’m not.

    It happens more often than you think and it happens to good businesses run by smart people who are working hard and growing. In fact, growth is one of the most common triggers for a cash crisis. The faster a business grows the more cash it consumes, and if the financial infrastructure isn’t in place to manage that consumption things can unravel surprisingly fast.

    Understanding why profitable businesses run out of cash is one of the most important things you can do as a business owner. So, let’s talk about it.

    First, what’s the difference between profit and cash flow?

    This is where a lot of business owners get tripped up and it’s not your fault because the language of business finance can be genuinely confusing.

    Profit is an accounting concept. It’s the difference between your revenue and your expenses as recorded in your profit and loss statement. It’s real in the sense that it reflects actual economic activity, but it doesn’t always reflect actual cash in your bank account.

    Cash flow is exactly what it sounds like. It’s the actual movement of money in and out of your business. Cash in when customers pay you. Cash out when you pay your bills, your employees, your vendors, and your lender.

    The gap between profit and cash flow is where the danger lives.

    Here’s how a profitable business runs out of cash

    Let me give you a few real world scenarios that play out every day in small businesses.

    Scenario 1, the slow paying customer

    Your business invoices $50,000 in a month. That revenue shows up on your P&L and makes the month look profitable. But your customers take 60-90 days to pay. Meanwhile your expenses, payroll, rent, supplies, are due right now. You’re profitable on paper but cash poor in reality. This is called an accounts receivable gap and it’s one of the most common cash flow killers in service businesses.

    Scenario 2, the growth trap

    Your business is growing fast. You need to hire ahead of revenue, buy more inventory, invest in equipment, and take on more overhead to support the growth. All of that investment goes out before the revenue from that growth comes in. Your P&L looks great because revenue is climbing. Your bank account tells a very different story. This is called growing broke and it has taken down businesses that were genuinely thriving on paper.

    Scenario 3, the seasonal squeeze

    Your business has a strong season and a slow season. You make most of your money in a few months and then have to stretch that cash across the rest of the year. If you spend too aggressively during your peak season you hit the slow season with insufficient cash reserves and suddenly profitable annual numbers don’t pay this month’s bills.

    Scenario 4, the tax surprise

    Your business has a great year. Revenue is up, profit is up, everything looks amazing. And then your CPA tells you that you owe $40,000 in taxes that you didn’t plan for. If you’ve been spending based on your bank balance without setting aside a tax reserve that $40,000 can create a genuine crisis even in a healthy business.

    How to make sure this doesn’t happen to you

    The good news is that cash flow problems are almost always preventable with the right systems in place. Here’s what those systems look like.

    Know your cash flow forecast, not just your P&L

    Your profit and loss statement tells you what happened. Your cash flow forecast tells you what’s coming. Every business owner should have a rolling 90-day cash flow forecast that shows projected cash in, projected cash out, and projected ending cash balance for each week or month.

    This one tool eliminates more financial surprises than anything else I know. When you can see a cash crunch coming 60 days out you have time to act. When you find out about it the day it happens you don’t.

    Separate your accounts

    Keep your operating cash, your tax reserve, and your CapEx or growth reserve in separate accounts. When everything sits in one account your bank balance is a misleading number that includes money that’s already spoken for. Separate accounts give you clarity about what you actually have available to spend.

    Invoice fast and collect faster

    The faster you get invoices out the faster cash comes in. If slow paying customers are creating a cash flow gap look at your invoicing terms and your collections process. Even shortening your payment terms from net 30 to net 15 can meaningfully improve your cash position.

    Build a cash reserve

    Every business should have a minimum of two to three months of operating expenses sitting in a dedicated reserve account that you don’t touch for day-to-day spending. This reserve is your buffer against seasonal slowdowns, unexpected expenses, slow paying customers, and any of the other scenarios I described above.

    Building this reserve takes time and discipline but it is one of the most important things you can do for the long term health of your business.

    Watch your receivables aging

    If customers owe you money that’s more than 30 days old that’s a cash flow risk. Review your accounts receivable aging report every month and follow up proactively on anything past due. Money that’s sitting in an invoice instead of your bank account is not working for your business.

    The bottom line

    Cash is oxygen for a business. You can survive a bad month on the P&L. You cannot survive running out of cash.

    The business owners who build real lasting financial health are the ones who understand the difference between profit and cash flow, who forecast their cash position consistently, and who build the systems that protect them from the surprises that take other businesses down.

    This is not complicated. But it does require intentionality and the right financial infrastructure.

    If you want help building a cash flow management system for your business, or if you want someone to forecast and track your cash position every month so you always know exactly where you stand, that’s exactly what I do.

    Visit me at https://www.pvifinancial.com and let’s make sure your business never runs out of cash.

    ~Wendi | PVI Financial | Fractional CFO & Bookkeeping Services for Small Business & Outdoor Hospitality

    Click here to read How To Structure Your First 90 Days as an RV Park Owner

  • 5 Financial Mistakes New RV Park Owners Make in Year One

    5 Financial Mistakes New RV Park Owners Make in Year One


    And how to avoid the ones that quietly kill your returns

    Buying an RV park or glamping property is one of the most exciting things you can do as a real estate investor. The cash flow potential is real, the asset class is growing, and if you buy right you can own a business that practically runs itself with the right systems in place.

    But year one is where a lot of new owners quietly get into trouble โ€” not because the deal was bad, but because they didn’t have the right financial infrastructure in place from day one. I’ve seen it happen, and I’ve cleaned up the aftermath. Here are the five mistakes I see most often and exactly how to avoid them.

    1. Assuming the seller’s numbers will just continue

    When you buy a stabilized RV park the trailing 12 months of financials look great. Occupancy is solid, revenue is consistent, NOI is healthy. And then you close and six months later you’re scratching your head wondering where the money went.

    Here’s what happens: ownership transitions are disruptive. Staff changes, booking patterns shift, returning guests who were loyal to the previous owner don’t come back, and small operational details that the seller handled intuitively don’t get transferred in a two-week handoff.

    The mistake is assuming the T12 numbers are a guarantee rather than a baseline. They’re a starting point. Your job in year one is to protect that baseline while you learn the business โ€” not to immediately start optimizing for growth.

    What to do instead: build a 12-month financial model before you close that stress-tests the numbers. What happens if occupancy drops 10% in year one? What happens if you lose your property manager? What’s your cash position in each scenario? Know your downside before you close, not after.

    2. Not separating operating cash from your personal cash fast enough

    This sounds obvious but it happens constantly โ€” especially to first time hospitality operators who are used to residential real estate where the cash flows are simpler.

    An RV park generates revenue daily. Weekends, holidays, and peak season dump cash into your account fast and it feels great. The problem is that cash has to carry you through the shoulder season, cover payroll, fund your CapEx reserve, and service your debt โ€” all at the same time. When it’s all sitting in one account it’s very easy to look at a healthy balance in July and make spending decisions that leave you scrambling in November.

    What to do instead: from day one set up separate accounts for operating cash, CapEx reserve, and tax reserve. Fund each one according to a monthly plan. Your operating account is the only one you spend from day to day. This one simple system eliminates more financial stress than almost anything else I recommend to new operators.

    3. Skipping the CapEx reserve

    RV parks are physical assets. Things break, wear out, and need replacing โ€” roofs, electrical hookups, water systems, roads, amenities. A well-run park budgets 5% of gross revenue annually into a dedicated CapEx reserve account.

    New owners skip this because the cash feels tight in year one and the roof looks fine right now. Then year three arrives and they’re facing a $60,000 electrical infrastructure repair with no reserve and a cash flow that can’t absorb it.

    What to do instead: fund your CapEx reserve from month one even if it feels premature. Treat it like a non-negotiable expense, not an optional savings account. Your future self will thank you.

    4. Not tracking the right KPIs for your specific property type

    Most new RV park owners track revenue and expenses. That’s bookkeeping. What you actually need is a dashboard of KPIs that tell you whether your business is healthy, growing, or starting to slip โ€” before it shows up as a problem in your P&L.

    For an RV park or glamping property the KPIs that matter most are:

    • Occupancy rate by site type (glamping vs RV vs tent โ€” they tell very different stories)
    • Average nightly rate by site type
    • Revenue per available site (RevPAS)
    • Operating expense ratio (excluding debt service)
    • Cash runway โ€” how many months of expenses does your current cash cover?

    If you’re not tracking these monthly you’re flying blind. And flying blind in year one โ€” when you’re still learning the business โ€” is how small problems become expensive ones.

    What to do instead: set up a monthly KPI dashboard from day one that tracks these numbers consistently. This is exactly what I build for every client โ€” a clean, simple report that shows you what’s happening in your business at a glance so you can spot trends early and act before small problems become expensive ones. If you’re not sure where to start visit me at pvifinancial.com and let’s talk.

    5. Waiting too long to get financial help

    This is the big one and honestly the one I feel most strongly about.

    Most new RV park owners wait until something goes wrong to get financial help. They try to manage it themselves, they rely on their CPA for year-end guidance, and they don’t build real financial visibility into their operation until they’re already in trouble.

    The problem with that approach is that by the time the problem is visible in your financials it’s usually been building for months. Cash flow issues, occupancy slippage, expense creep โ€” these things don’t appear overnight. They show up slowly and then all at once.

    Year one is exactly when you need the most financial support โ€” not because you’re bad at business, but because you’re learning a new asset class while simultaneously trying to protect your investment and service your debt. That’s a lot to carry without a financial partner who knows the numbers as well as you do.

    What to do instead: get a fractional CFO or financial advisor in place before you close or in the first 30 days after. Someone who will build your reporting infrastructure, track your KPIs, flag problems early, and give you a clear picture of your financial position every single month. The cost of that support is a fraction of what one missed problem in year one can cost you.

    The bottom line

    Buying a great RV park or glamping property is the beginning, not the end. The operators who build real wealth in this asset class are the ones who treat the financial side of the business with the same seriousness as the operational side.

    Know your numbers. Track the right metrics. Build the right systems from day one. And don’t wait until something goes wrong to ask for help.

    If you’re buying or have recently bought an RV park or outdoor hospitality property and want to talk through your financial setup, I’d love to connect. The first conversation is always free.

    โ€” Wendi | PVI Financial | Fractional CFO & Bookkeeping Services for Small Business & Outdoor Hospitality https://pvifinancial.com

    Click here to read “How to Structure Your First 90 Days as a New RV Park Owner “